


- If you have been wondering whether P10 is priced attractively right now, you are not alone. Many investors are asking the same question about what they are really paying for with this stock.
- P10 shares last closed at US$10.33, with recent returns of 4.4% over the past week, 1.2% over the past month, 4.4% year to date, and a 17.6% decline over the past year and 7.6% decline over three years.
- Recent market attention on P10 has been shaped by ongoing discussion around its role in the diversified financials space and how investors assess listed alternative asset managers generally. This backdrop helps explain why the stock has seen mixed shorter term and longer term returns as views on risk and opportunity have shifted.
- Against that context, P10 currently records a valuation score of 0 out of 6. We will unpack this using several common valuation approaches, then wrap up with a different way of looking at value that many investors find even more useful.
P10 scores just 0/6 on our valuation checks. See what other red flags we found in the full valuation breakdown.
Approach 1: P10 Excess Returns Analysis
The Excess Returns model looks at whether a company is expected to earn more on its equity than the return investors require. If the return on equity is below that required return, the model typically points to a lower intrinsic value.
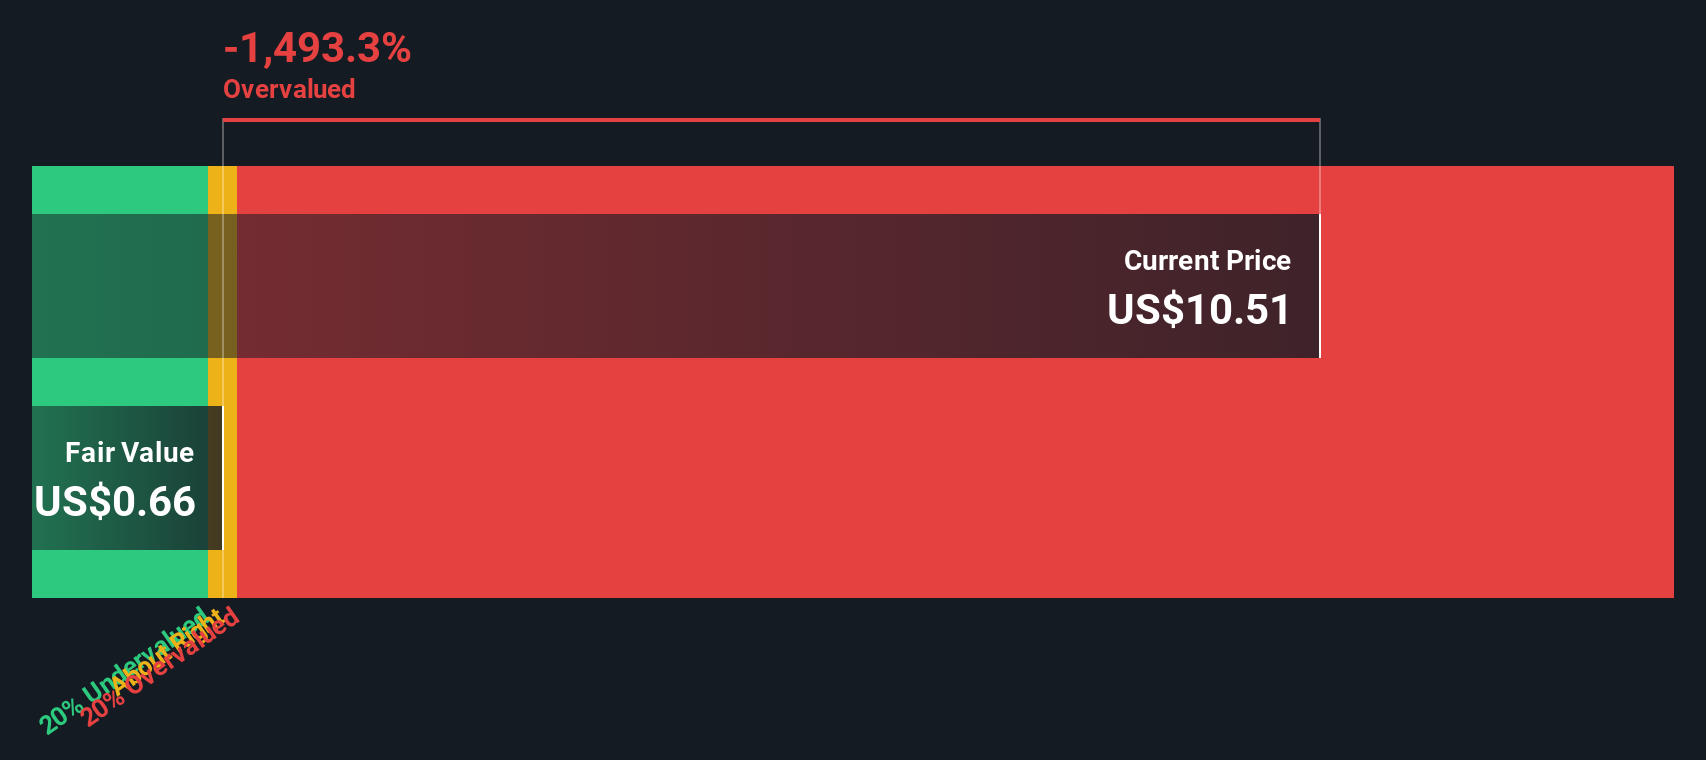
For P10, the starting Book Value is $3.14 per share, with a Stable EPS of $0.18 per share, based on the median return on equity from the past 5 years. The Average Return on Equity is 3.98%. Against this, the model uses a Cost of Equity of $0.44 per share, which leads to an Excess Return of $0.26 per share in the red. In other words, the earnings assumed in the model do not fully cover the required return on shareholders’ capital.
The Stable Book Value is $4.54 per share, using weighted future Book Value estimates from 2 analysts, and the model converts these inputs into an estimated intrinsic value per share of about $0.51.
Compared with the latest share price of US$10.33, this Excess Returns estimate suggests P10 is very expensive on this measure.
Result: OVERVALUED
Our Excess Returns analysis suggests P10 may be overvalued by 1913.5%. Discover 879 undervalued stocks or create your own screener to find better value opportunities.
Approach 2: P10 Price vs Earnings
For a profitable company like P10, the P/E ratio is a straightforward way to think about what you are paying for each dollar of current earnings. It links directly to the business you actually own today, rather than long range forecasts.
What counts as a “normal” P/E really depends on how investors view growth potential and risk. Higher expected earnings growth or lower perceived risk can justify paying a higher multiple, while slower growth or higher risk typically points to a lower, more cautious P/E.
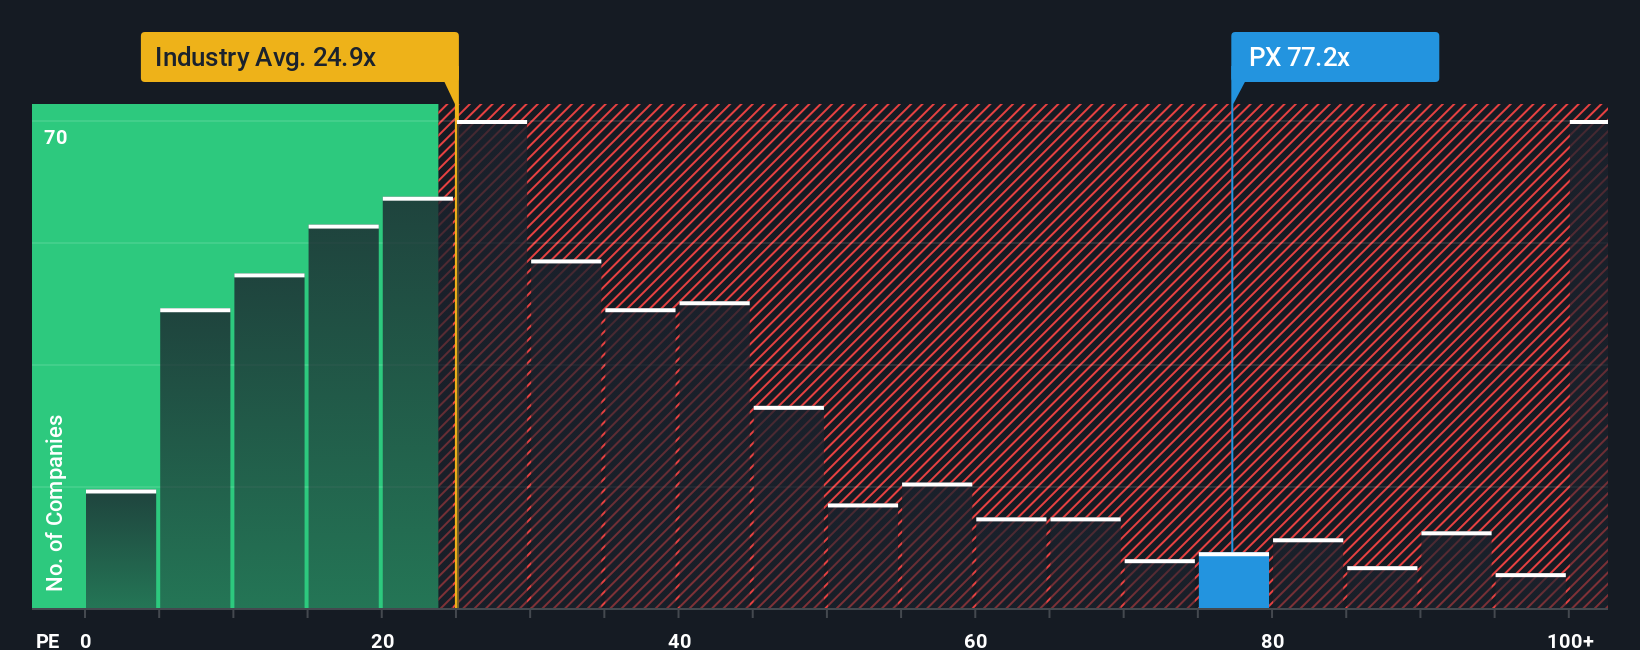
P10 currently trades on a P/E of 74.13x. That sits well above the Capital Markets industry average of 25.61x and also above the peer group average of 8.60x. Simply Wall St’s “Fair Ratio” is a proprietary P/E estimate that reflects factors like earnings growth, risks, profit margins, industry and market cap, rather than just simple comparisons with peers.
Because the Fair Ratio blends these fundamentals into a single number, it can often be a more tailored benchmark than raw industry or peer averages. On this view, P10’s current P/E of 74.13x is higher than its Fair Ratio, which points to the shares looking expensive on this metric.
Result: OVERVALUED
P/E ratios tell one story, but what if the real opportunity lies elsewhere? Discover 1444 companies where insiders are betting big on explosive growth.
Upgrade Your Decision Making: Choose your P10 Narrative
Earlier we mentioned that there is an even better way to understand valuation, so let us introduce you to Narratives, a simple tool on Simply Wall St’s Community page that lets you link your view of P10’s story to a set of revenue, earnings and margin forecasts. You can then turn those into a fair value and compare that fair value to today’s share price to help you decide whether you think it is a buy or a sell. You can also see that view automatically update when new information, like news or earnings, is added. As a result, one investor might build a Narrative that lines up with a fair value near US$18.00, while another might anchor their expectations closer to US$12.00, even though they are looking at the same company.
Do you think there's more to the story for P10? Head over to our Community to see what others are saying!

This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com