


- In the second quarter of 2026, United Fire Group, Inc. reported revenue of US$383.73 million and net income of US$33.37 million, both higher than a year earlier, with diluted EPS from continuing operations rising to US$1.29.
- Across the first half of 2026, the company’s higher revenue and earnings versus the prior year highlight improved profitability from its core insurance operations.
- With earnings from continuing operations improving meaningfully, we’ll now assess how this stronger profitability affects United Fire Group’s existing investment narrative.
Find 51 companies with promising cash flow potential yet trading below their fair value.
United Fire Group Investment Narrative Recap
To own United Fire Group, you need to believe it can keep turning its core property and casualty book into consistent underwriting profits while managing volatile catastrophe losses. The latest quarterly beat supports the near term earnings catalyst, but also sharpens focus on whether higher climate related events could pressure loss ratios and unsettle margins.
Among recent announcements, the steady quarterly dividend of US$0.20 per share in May 2026 stands out alongside the stronger earnings run rate. Together, they frame how management is balancing reinvestment needs, capital strength and shareholder returns at a time when analysts still see earnings declining, even as revenue is forecast to grow.
Yet beneath the stronger results, investors should be aware that rising climate related catastrophe risk could still...
Read the full narrative on United Fire Group (it's free!)
United Fire Group's narrative projects $2.4 billion revenue and $93.4 million earnings by 2029. This requires 18.1% yearly revenue growth and a $47.6 million earnings decrease from $141.0 million today.
Uncover how United Fire Group's forecasts yield a $57.00 fair value, a 5% upside to its current price.
Exploring Other Perspectives
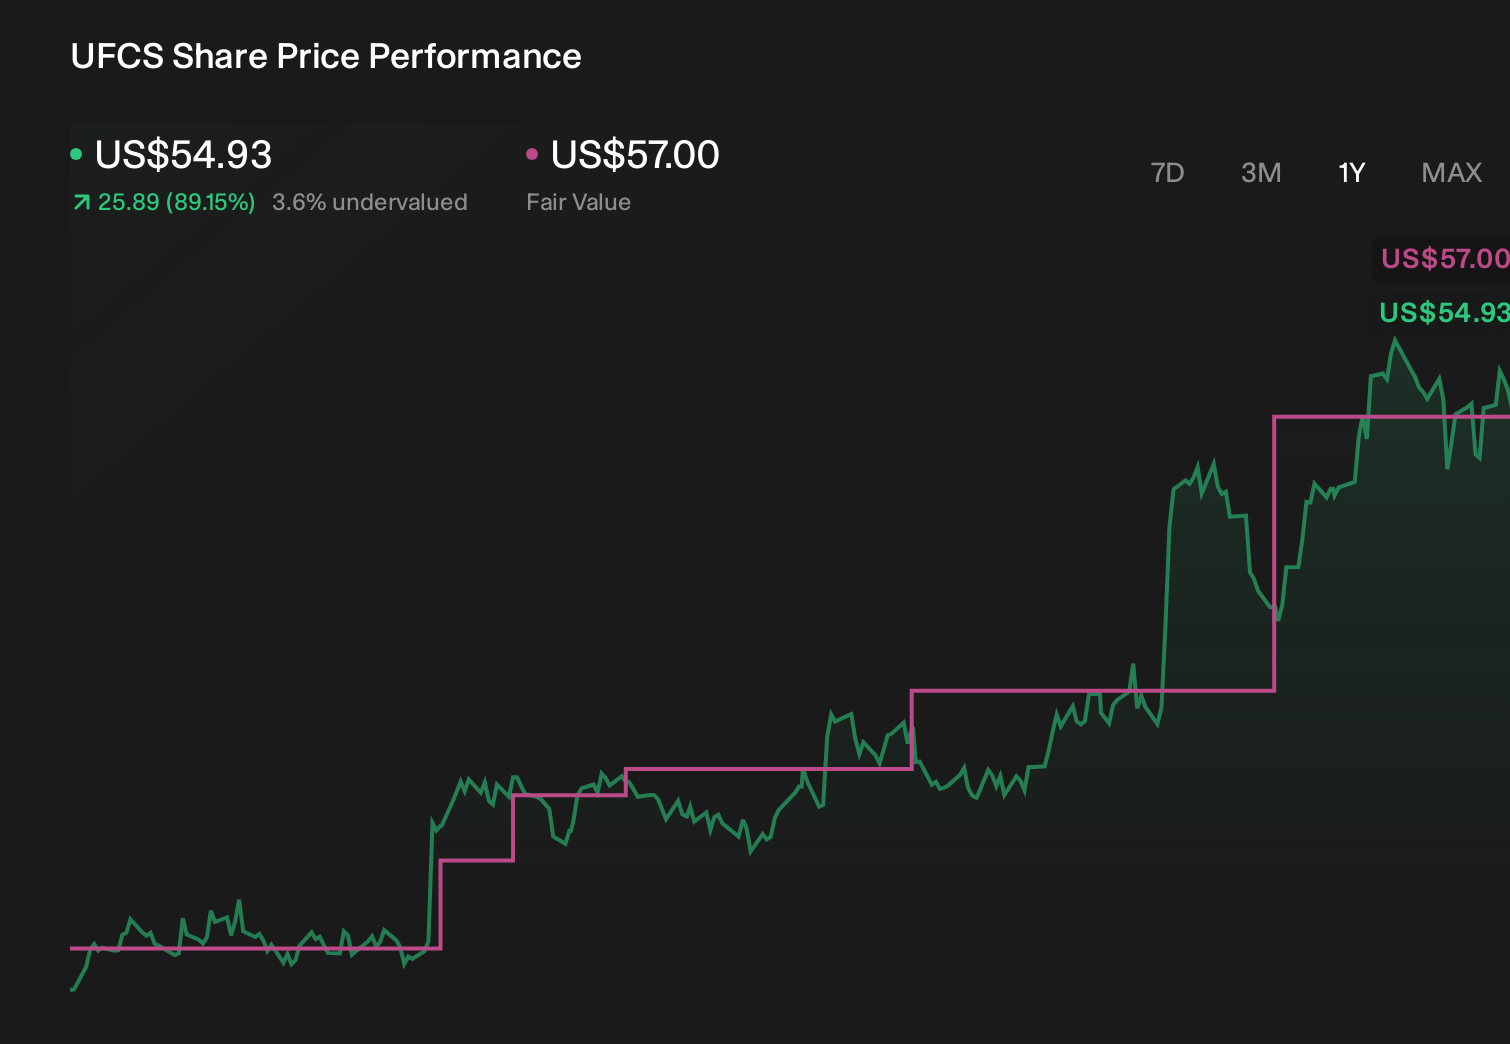
One member of the Simply Wall St Community currently pegs United Fire Group’s fair value at US$57, showing how a single view can differ from analyst targets and market pricing. You may want to weigh that against the risk that more frequent climate related losses could pressure underwriting performance and reshape expectations for the business over time.
Explore another fair value estimate on United Fire Group - why the stock might be worth as much as $57.00!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your United Fire Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- Our free United Fire Group research report provides a comprehensive fundamental analysis summarized in a single visual - the Snowflake - making it easy to evaluate United Fire Group's overall financial health at a glance.
Looking For Alternative Opportunities?
Early movers are already taking notice. See the stocks they're targeting before they've flown the coop:
- We've uncovered the 8 dividend fortresses yielding 5%+ that don't just survive market storms, but thrive in them.
- Capitalize on the AI infrastructure supercycle with our selection of the 56 best 'picks and shovels' of the AI gold rush converting record-breaking demand into massive cash flow.
- The future of work is here. Discover the 35 top robotics and automation stocks leading the charge in AI-driven automation and industrial transformation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com