


NPK International (NPKI) is back in focus after announcing the planned retirement of long serving Chief Financial Officer Gregg Piontek and the appointment of Matthew Warren as Chief Accounting Officer.
Recent trading suggests some investors are reassessing NPK International after the leadership announcement, with the share price down 11.95% over the past 90 days but still up 9.01% year to date and supported by a very strong 5 year total shareholder return of 362.81%.
Scan how other infrastructure and industrial solution stocks with resilient balance sheets are reacting to leadership shifts through our curated list of solid balance sheet and fundamentals (23 results) as you assess where NPK International now fits in your portfolio.
NPK International now trades well below analyst targets after the CFO succession news, yet the stock’s multi year run and recent pullback point in opposite directions. Is the discount a real opportunity or a warning sign?
Most Popular Narrative: 35.1% Undervalued
NPK International closed at $13.19 against a widely followed fair value estimate of $20.33, so the narrative framework sees a wide gap to its modeled worth.
Strong and flexible balance sheet with ample liquidity allows continued investment in fleet expansion, operational efficiency, and share repurchases, while also enabling potential strategic acquisitions. This supports both revenue growth and shareholder returns (EPS uplift from buybacks), and underpins the company's undervaluation relative to forward growth prospects.
Want to understand why this valuation view stretches so far beyond today’s $13.19 price tag? The narrative leans on compounding earnings, firming margins, and a richer profit multiple years from now.
Result: Fair Value of $20.33 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the bullish NPK International story can fray if large infrastructure projects are delayed or if harder to predict product sales soften at the wrong time.
Find out about the key risks to this NPK International narrative.
Another View: What NPK International’s P/E Is Telling You
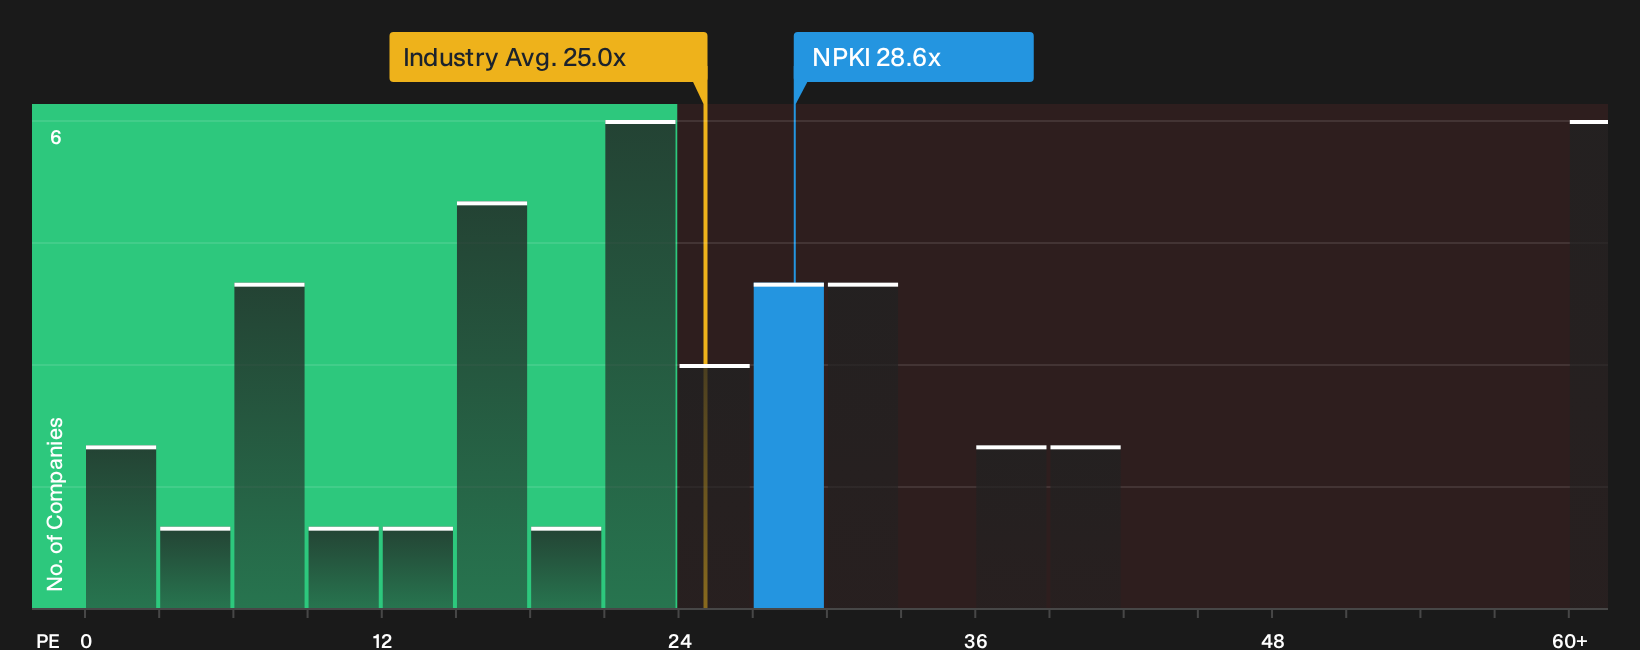
The bullish narrative around NPK International leans on analyst models, yet the share price paints a more complicated picture. On a P/E of 28.6x, the stock trades above both its own fair ratio of 22.3x and the US Trade Distributors average of 25.1x, which points to valuation risk rather than a clear bargain. This raises the question of whether that premium reflects genuine conviction in the story or expectations that have already run ahead of the fundamentals.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on NPK International so far, right? If you want to move quickly and ground your own view in hard data, start with the 2 key rewards.
Looking for more investment ideas beyond NPK International?
If you only watch NPK International, you risk missing other opportunities. Put a small slice of time into scanning fresh ideas that might better fit your goals.
- Target potential mispricings by reviewing companies that screen as undervalued on both quality and price through the 33 high quality undervalued stocks.
- Build a steadier income stream by focusing on businesses identified as dividend fortresses in the 6 dividend fortresses.
- Raise your quality bar by filtering for companies with strong balance sheets and fundamentals using the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com