


Barrick Mining (TSX:ABX) has drawn fresh attention after its corporate name change from Barrick Gold. This shift broadens the focus beyond gold toward a wider mix of mined materials and revenue sources.
Recent trading has been choppy, with Barrick Mining’s share price slipping 2.31% on the day and 4.59% over the past week. However, a 7.76% 30-day share price return and very large 5-year total shareholder return of 193.02% suggest long-term momentum has been strong, even as short-term sentiment cools around the CA$60.14 level.
Scan beyond Barrick Mining and see how it compares with 35 elite gold producer stocks that is riding similar commodity and multi-asset momentum.
So is that recent slide at Barrick Mining a verdict on the new, broader business mix, or just cooler sentiment catching up with a stock that has surged over 5 years? The valuation now becomes the real point of focus.
Most Popular Narrative: 8.5% Undervalued
The most followed narrative currently pegs Barrick Mining’s fair value at CA$65.74, which sits modestly above the CA$60.14 close, framing the recent pullback as a valuation gap rather than a breakdown.
Significant ongoing expansion of both gold and copper production capacity, particularly at Lumwana and via organic growth at Fourmile and Reko Diq, positions Barrick to capture elevated long-term demand for gold (as a financial hedge during geopolitical uncertainty/inflation) and copper (driven by electrification and infrastructure investment), supporting top-line revenue growth over the coming decade.
Read the complete narrative. Read the complete narrative.
Want to see what underpins that valuation uplift for Barrick Mining? The current fair value hinges on a specific earnings path, paired with a tighter margin profile and a future P/E that assumes investors stay willing to pay up for consistent execution. Curious which revenue and profit assumptions have the biggest impact on that CA$65.74 figure and how sensitive it is to even small changes in outlook? The full narrative lays out the entire blueprint behind that 8.5% gap.
Result: Fair Value of CA$65.74 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Barrick Mining story can break if political disruption at key sites or tighter ESG rules push costs higher and squeeze those forecast margins.
Find out about the key risks to this Barrick Mining narrative.
Another View: SWS DCF Flags a Different Story
The analyst narrative leans on a fair value of CA$65.74 for Barrick Mining, but the SWS DCF model tells a cooler story. On that cash flow view, Barrick Mining’s estimated value sits at CA$48.33, which would make the current CA$60.14 price look stretched rather than cheap.
That kind of gap reflects more cautious assumptions about how much free cash Barrick Mining might generate and what investors may be willing to pay for it. It raises a simple question for you: Do you trust the earnings path that underpins the analyst target, or the more conservative cash flow math that points to less upside?
Look into how the SWS DCF model arrives at its fair value.
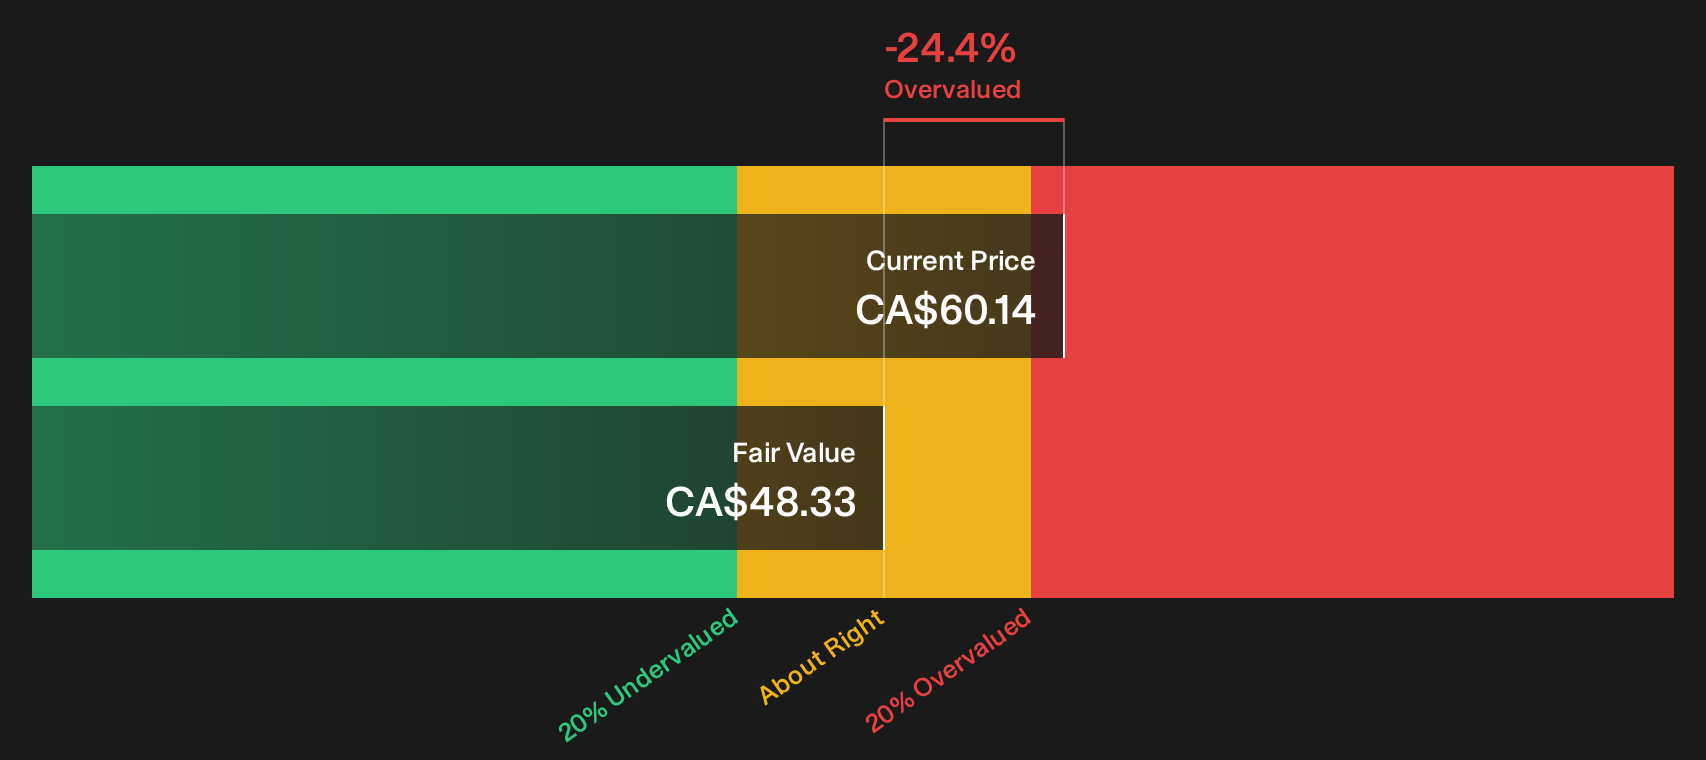
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Barrick Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Barrick Mining is clearly mixed, with both risks and rewards on the table. Consider reviewing the data for yourself and weighing the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Barrick Mining?
Do not stop with Barrick Mining. Use the Simply Wall Street Screener to quickly spot other opportunities that match the kind of portfolio you want to build.
- Target value first and scan a curated 6 high quality undervalued stocks that may offer stronger fundamentals than the headlines suggest.
- Prioritise resilience and stress test your portfolio with a 1 resilient stocks with low risk scores that focuses on steadier business profiles.
- Hunt for tomorrow's potential standouts by scanning a 9 high quality undiscovered gems before the crowd pays attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com