


Lam Research (LRCX) is back in focus after Barometer Capital Management flagged the stock as a key positive contributor in Q2 2026, citing strong exposure to memory equipment tied to AI demand.
Lam Research shares have cooled in recent weeks, with the 30-day share price return down 8.6% and the 90-day move down 18.7%. The stock still carries a strong year to date share price gain of 61.2% and a one year total shareholder return of 156.4%. Momentum has therefore eased near the US$298.22 level as investors digest the raised wafer fabrication equipment outlook, heavier AI related spending, and the step up in dividends and buybacks.
Spot under-the-radar peers riding the same AI equipment wave as Lam Research by scanning our hand picked 89 AI infrastructure stocks.For Lam Research at around US$298, the question is whether the recent pullback already offers a reasonable entry or if the run up in AI expectations argues for patience until the valuation resets further.
Most Popular Narrative: 29.6% Undervalued
Lam Research is priced at $298.22 while the most followed narrative on the stock points to a fair value of $423.85. This frames the recent pullback very differently.
Lam has greater operating leverage to memory and layer-count growth than any of them, and it owns the specific process steps, high-aspect-ratio etch, through-silicon via formation, copper electrofill, that HBM stacking and 3D NAND scaling physically require. When the constraint is vertical scaling, Lam is the constraint.
Read the complete narrative. Read the complete narrative.
If you want to understand why that fair value comes out so far above the share price, focus on three things. The revenue path that narrative sketches through the wafer equipment cycle. The margin structure it assumes stays in place. And the valuation multiple it uses on those earnings that links Lam Research to some of the most highly rated chip equipment stocks.
Result: Fair Value of $423.85 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Lam Research’s AI memory pitch can weaken if hyperscaler capex slows or if policy changes hit China demand and disrupt that upgrade path.
Find out about the key risks to this Lam Research narrative.
Another View on Lam Research Valuation
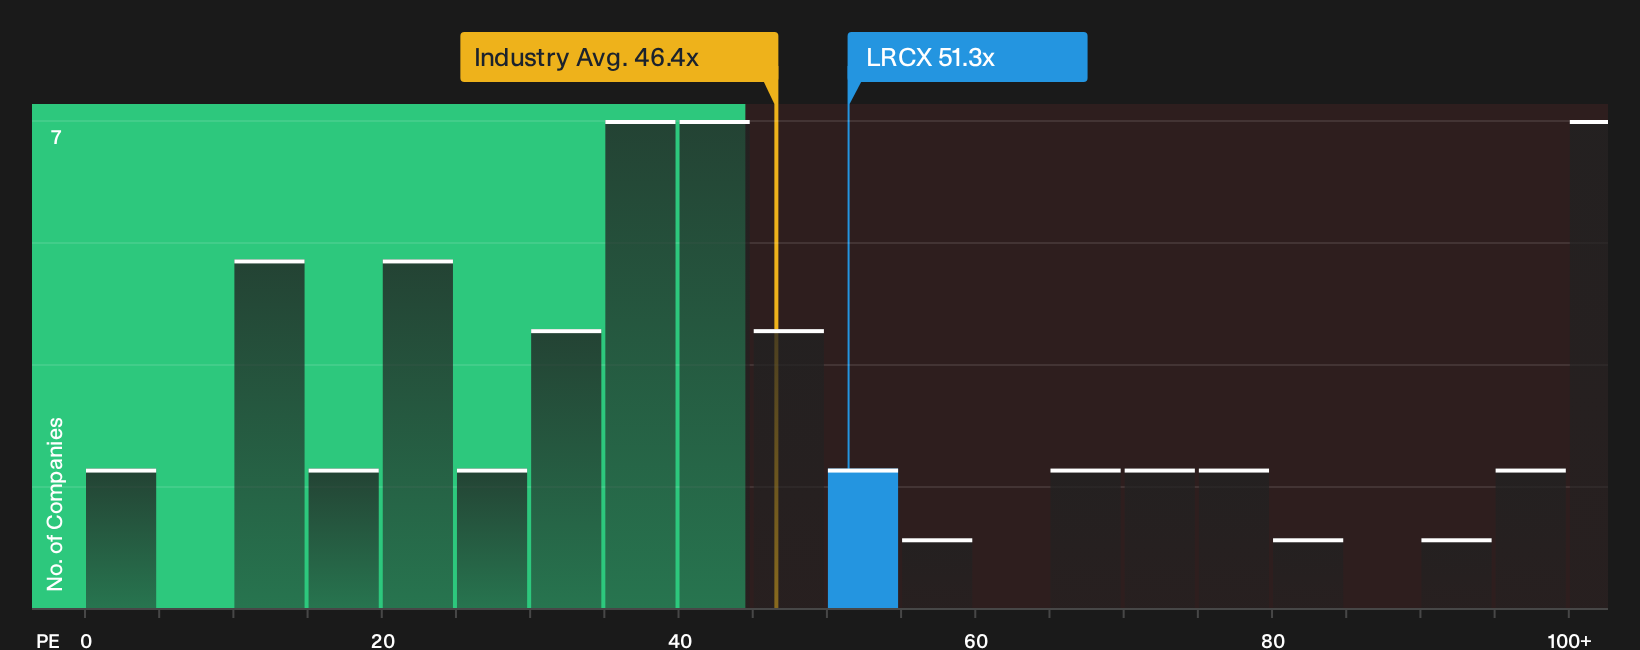
There is a very different read of Lam Research at $298.22 when the focus shifts from that $423.85 narrative fair value to the current P/E. The stock trades around 51.4x earnings, compared with roughly 46.4x for the US semiconductor group and 46.2x for peers, while the fair ratio sits lower again at 44.2x.
That gap means investors are already paying a premium to both the sector and similar stocks, and even to the level our fair ratio suggests the multiple could drift toward over time. The key question is whether the growth and AI exposure justify accepting that valuation risk.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Lam Research is clearly split, so this is the moment to move quickly, evaluate the complete picture, and decide where you stand using the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Lam Research?
If Lam Research has your attention, do not stop here. Broaden your opportunity set with a few targeted stock lists that surface different kinds of potential winners.
- Target stability first and scan a 11 resilient stocks with low risk scores that highlights businesses with more resilient profiles when market swings pick up.
- Hunt for value and review a 31 high quality undervalued stocks that blends solid balance sheets with cash flows priced at what may look like a discount.
- Get ahead of the crowd and comb through a 16 high quality undiscovered gems that focuses on quality companies still flying under most investors' radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com