


Astera Labs has climbed 62.2% year to date, yet valuation checks point to a stock that appears expensive on most measures and only roughly aligned with its intrinsic value estimate rather than clearly cheap.
- The 62.2% year to date gain sets a high bar for future returns and leaves little room for disappointment in the story investors are paying for.
- Expectations for ongoing growth in high speed connectivity solutions can support the current share price, while any slowdown in cash flow progress or heavier investment needs may pressure what investors are willing to pay.
- The broader valuation workup, where Astera Labs is assessed as undervalued in 0 of 6 checks, suggests the stock does not offer an obvious bargain on standard valuation yardsticks.
The key question now is whether Astera Labs at roughly its current level offers enough intrinsic value support to justify the premium signals coming from the market multiples.
Scan how Astera Labs compares with other high speed data and AI infrastructure plays by reviewing the hand picked 89 AI infrastructure stocks in a single view.
Is Astera Labs Fairly Priced on Cash Flow?
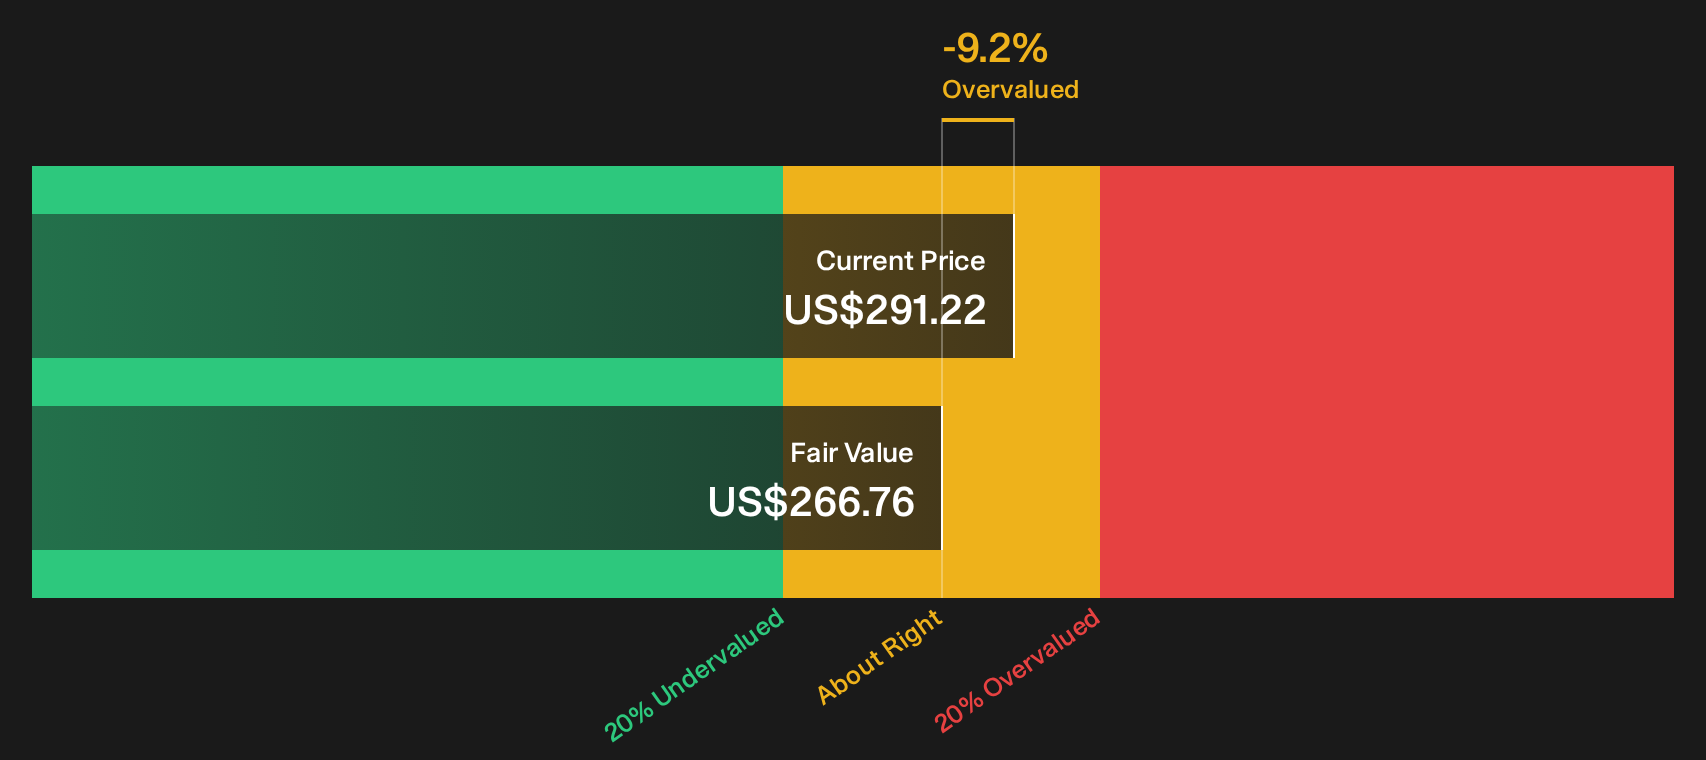
The Discounted Cash Flow model looks at Astera Labs by projecting out future free cash flows and bringing them back to today’s dollars. On this view, the business currently generates trailing twelve month free cash flow of about $275.8 million, with the model assuming growing cash generation over time rather than a shrinking profile.
Those projections roll up to an estimated intrinsic value of about $266.76 per share, which sits below the current share price and points to roughly a 9.2% premium in the market. For a reader, that means the cash flow math does not flag Astera Labs as a clear bargain, especially when paired with already rich P/E, P/B and P/S multiples.
On this Discounted Cash Flow view, Astera Labs looks about fairly valued rather than clearly cheap or clearly expensive.
Astera Labs is fairly valued according to our Discounted Cash Flow (DCF), but this can change at a moment's notice. Track the value in your watchlist or portfolio and be alerted on when to act.
Has Astera Labs Run Too Far on Earnings?
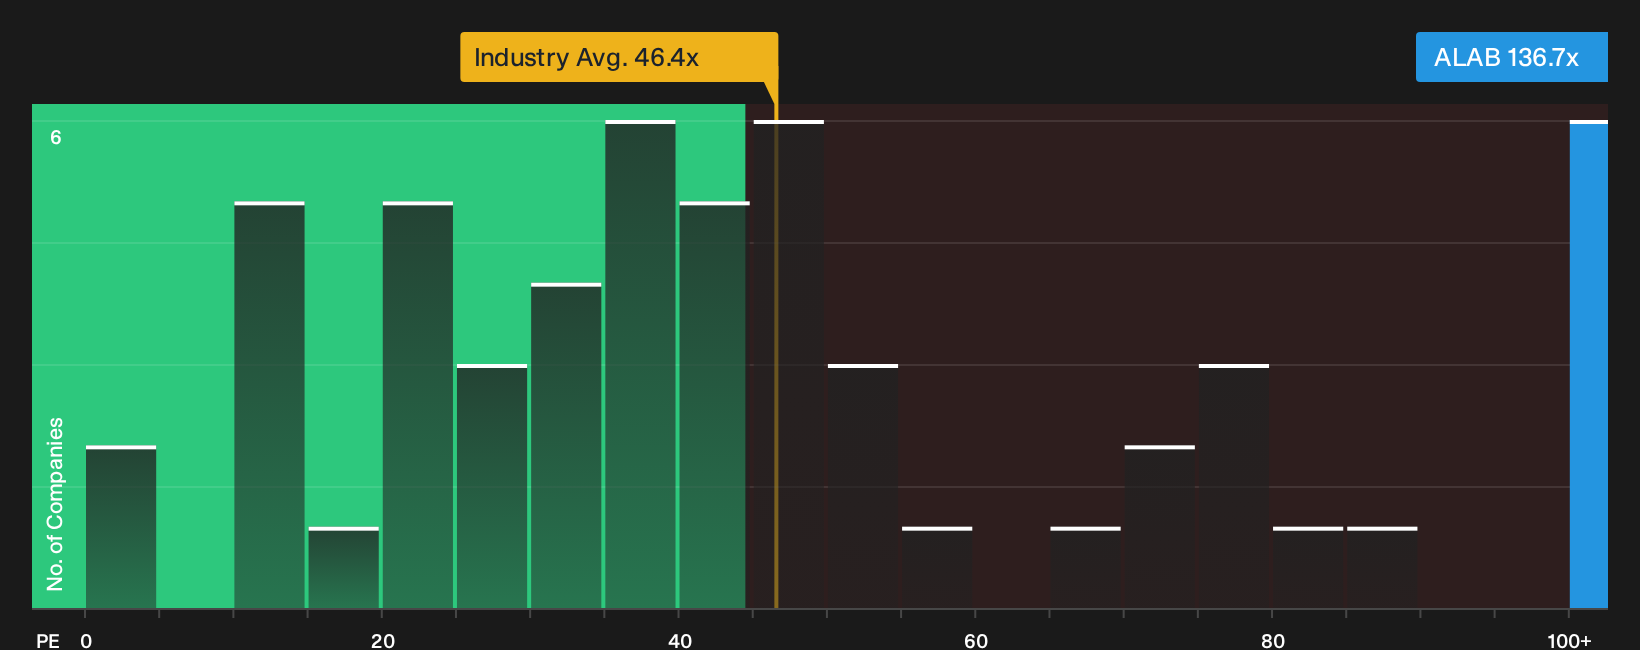
P/E works well for Astera Labs because investors are focused on what they are willing to pay for each dollar of current earnings in a fast evolving chip ecosystem. On this yardstick, the stock trades on about 136.7x earnings, which is roughly triple the broader semiconductor sector average of 46.4x. That is a wide premium for a company still building its track record as a listed business.
The fair P/E ratio implied by the model is about 54.4x, which already reflects its sector, size, risk profile and growth assumptions. The current 136.7x multiple sits far above that level and also appears high relative to a peer average of 65.6x. For an investor, this means Astera Labs depends on the market continuing to pay a steep price for each dollar of earnings, with limited buffer if sentiment cools.
On the preferred P/E yardstick, Astera Labs currently appears clearly overvalued compared with both peers and its modelled fair multiple.
See what the numbers say about this price — find out in our valuation breakdown.
The Astera Labs Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Astera Labs pick up where the valuation puzzle leaves off and explain which paths for growth, margins and earnings would need to occur for the stock to be worth materially more or less than where it trades today on the market. Rather than a single multiple or model output, each narrative lays out the set of assumptions behind its view of fair value so you can compare those expectations with Astera Labs' actual results over time.
Community views on Astera Labs could hardly be further apart, with one camp focused on product strength and another fixated on concentration and disruption risk.
Bull case: 13% undervalued
"Astera’s products act as universal adapters that work equally well with NVIDIA, AMD, or custom chips so they should be able to make money off everyone…"
Read the full Bull Case to see why Astera Labs could be undervalued
Bear case: 30% overvalued
"Astera Labs' deep reliance on a small set of leading hyperscalers and AI platform vendors as core customers leaves it exposed to severe revenue volatility…"
Read the full Bear Case to see why Astera Labs could be overvalued
Do you think there's more to the story for Astera Labs? Head over to our Community to see what others are saying!
The Bottom Line
Astera Labs screens as roughly in line with its intrinsic value estimate on a Discounted Cash Flow (DCF) view, yet trades as clearly overvalued on earnings-based multiples. That mix points to a stock where cash flow assumptions look broadly reasonable, while sentiment and growth expectations keep the P/E ratio stretched. Broader valuation checks remain weak, so the debate now hinges less on spotting a mispricing and more on whether current growth and margin hopes stay intact enough to support that premium. The crux is simple for Astera Labs: either earnings grow into the multiple or the multiple does the adjusting instead.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com