


Octave Intelligence plc has launched a new technology collaboration with Maire (BIT:MAIRE). The initiative aims to bring artificial intelligence directly into engineering, procurement and construction workflows that support complex capital projects.
Maire’s share price has lifted 2.52% over the past day and 3.36% across the last week, although the 90-day share price return is down 16.38%. The 1-year total shareholder return of 6.23% and very large 5-year total shareholder return suggest long term momentum remains intact despite recent volatility.
Compare Maire’s AI push with other industrials by scanning our hand picked 89 AI infrastructure stocks that is now shaping how complex projects use data and automation.
Maire now trades well below analyst targets after a sharp 90 day pullback, yet longer term returns remain solid. Is the discount a sign of opportunity, or a fair warning about risk as growth expectations reset?
Most Popular Narrative: 27.8% Undervalued
The latest narrative fair value of €17.46 sits well above Maire’s last close at €12.61, which puts a lot of focus on what is driving that gap.
Maire's NextChem and Sustainable Technology Solutions divisions have gained strong traction in green hydrogen, biofuels, and circular chemistry, with proprietary technologies like AdWinMethanol Zero and NX eBlue positioned at the forefront of global climate initiatives. As these high-value, low-carbon projects move to execution (e.g., the Pacifico Mexinol contract), margins and EBITDA are expected to benefit from the higher profitability of these business lines.
Want to understand why this green chemistry push supports a higher fair value for Maire? The narrative leans heavily on richer margins, steadier licensing income, and a payout multiple more often associated with premium growth stories. The key is how these ingredients are stitched together in the forecasts. The full breakdown shows exactly how that path to €17.46 is constructed.
Result: Fair Value of €17.46 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Maire’s heavy exposure to large EPC work in politically fragile regions, along with its relatively small green tech footprint, could quickly test this upside story.
Find out about the key risks to this Maire narrative.
Another View on Maire’s Valuation
While the narrative fair value suggests Maire is 27.8% undervalued at €17.46 versus €12.61, the SWS DCF model points in the opposite direction. On this cash flow view, Maire trades above an estimated value of €10.91, which flags the shares as overvalued instead.
Two models, two different answers, and both using reasonable assumptions. Which one do you think better fits how Maire will actually convert today’s projects and AI initiatives into future cash?
Look into how the SWS DCF model arrives at its fair value.
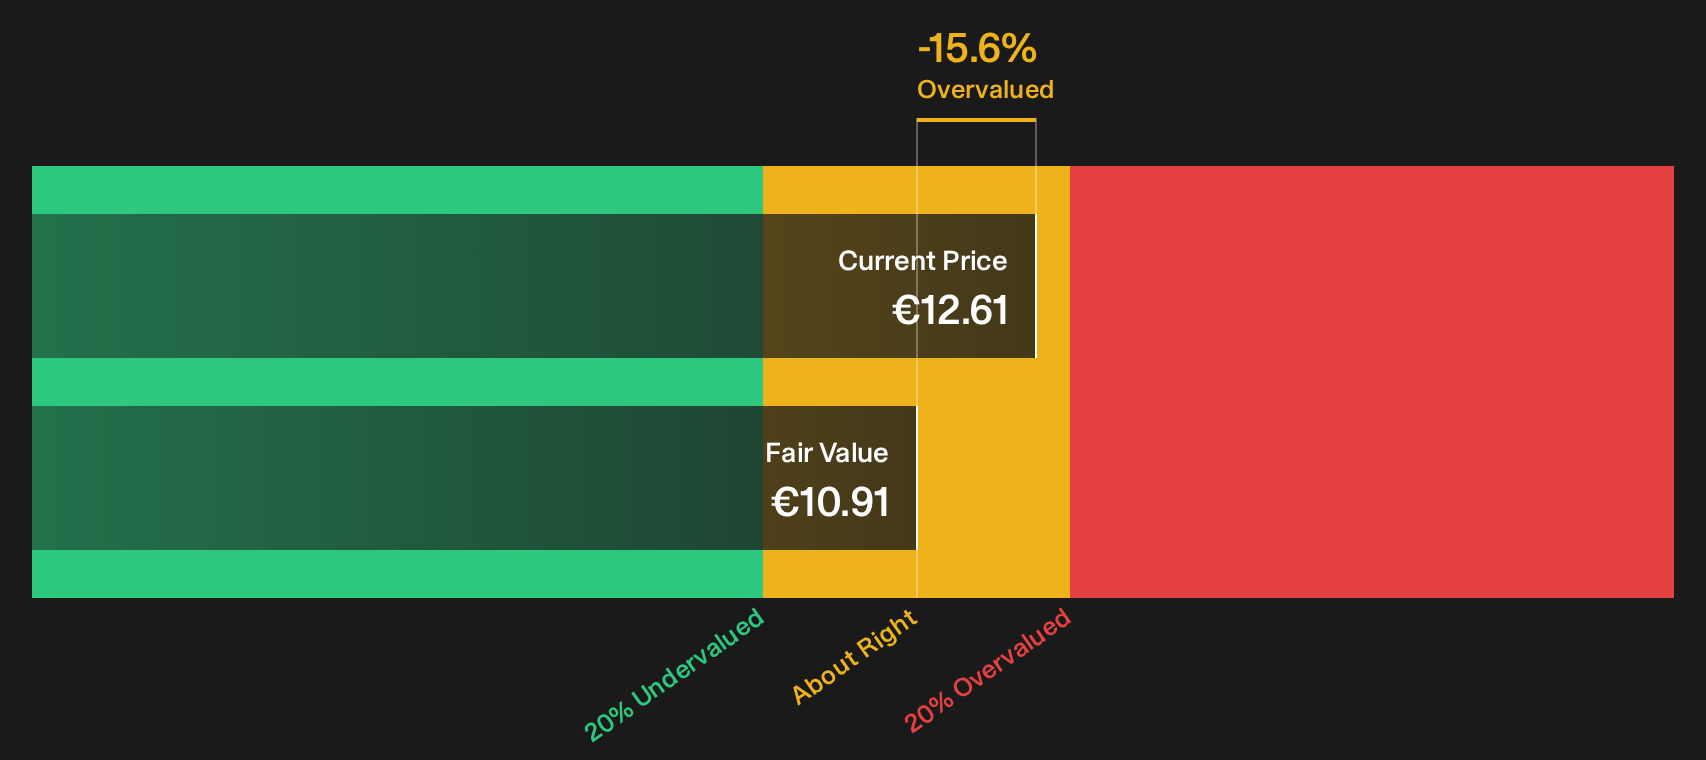
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Maire for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 183 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Maire so far? Take a moment to dissect the numbers, weigh both the upside and the flagged concerns, and then review the 4 key rewards and 1 important warning sign.
Looking for more ideas beyond Maire?
If Maire has sharpened your focus on where capital might work harder, use that momentum to scan other opportunities before they slip off your radar.
- Target resilient balance sheets and cleaner fundamentals by filtering through the list of solid balance sheet and fundamentals (193 results) that highlights companies with sturdier financial footing.
- Hunt for potential mispricings by scanning the 183 high quality undervalued stocks that surfaces stocks with quality metrics trading below their estimated worth.
- Prioritise defense and steadier income streams with the 97 resilient stocks with low risk scores that points to businesses carrying lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com