


A new global carbon fiber report has put Hexcel (HXL) in focus, naming the producer among leading suppliers to aerospace, wind energy, electric vehicles, hydrogen storage, and recycled carbon markets.
Hexcel shares closed at US$92.74 after a 3.25% 1-day share price return, while the stock is still down 9.35% on a 30-day share price basis and 5.09% over 90 days. The 1-year total shareholder return of 50.93% and 5-year total shareholder return of 66.02% indicate momentum that has built over a longer horizon as investors reassess growth prospects and risk around the carbon fiber demand story.
Scan other carbon fiber players riding similar tailwinds by checking the hand picked 39 power grid technology and infrastructure stocks that sit alongside Hexcel in the broader infrastructure build out.
After a sharp 1-year run and a softer few months, Hexcel now presents a simple question to investors: Do the current numbers still justify taking on the carbon fiber story at this price?
Most Popular Hexcel Narrative: 15.6% Undervalued
Hexcel’s widely followed narrative pegs fair value at $109.92 against the last close of $92.74. This frames the current carbon fiber enthusiasm in valuation terms rather than just share price momentum.
The anticipated ramp-up in commercial aircraft production, particularly for flagship programs like the Airbus A320neo, A350, and Boeing 787/737 MAX, as supply chain destocking abates and engine/component shortages get resolved, positions Hexcel for significant revenue growth and operating leverage when global air travel demand continues its multi-year recovery.
Want to see what sits behind that earnings story for Hexcel? The narrative leans on higher margins, stronger cash generation and a future profit multiple that assumes continued discipline on both costs and capital. It raises the question of which specific growth and profitability paths need to align for that fair value to hold.
Result: Fair Value of $109.92 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Hexcel story can break if supply chain snags slow aircraft build rates or if long term fixed price contracts continue to squeeze margins as costs shift.
Find out about the key risks to this Hexcel narrative.
Hexcel Valuation Check: A Rich P/E Against A “Cheap” Cash Flow Story
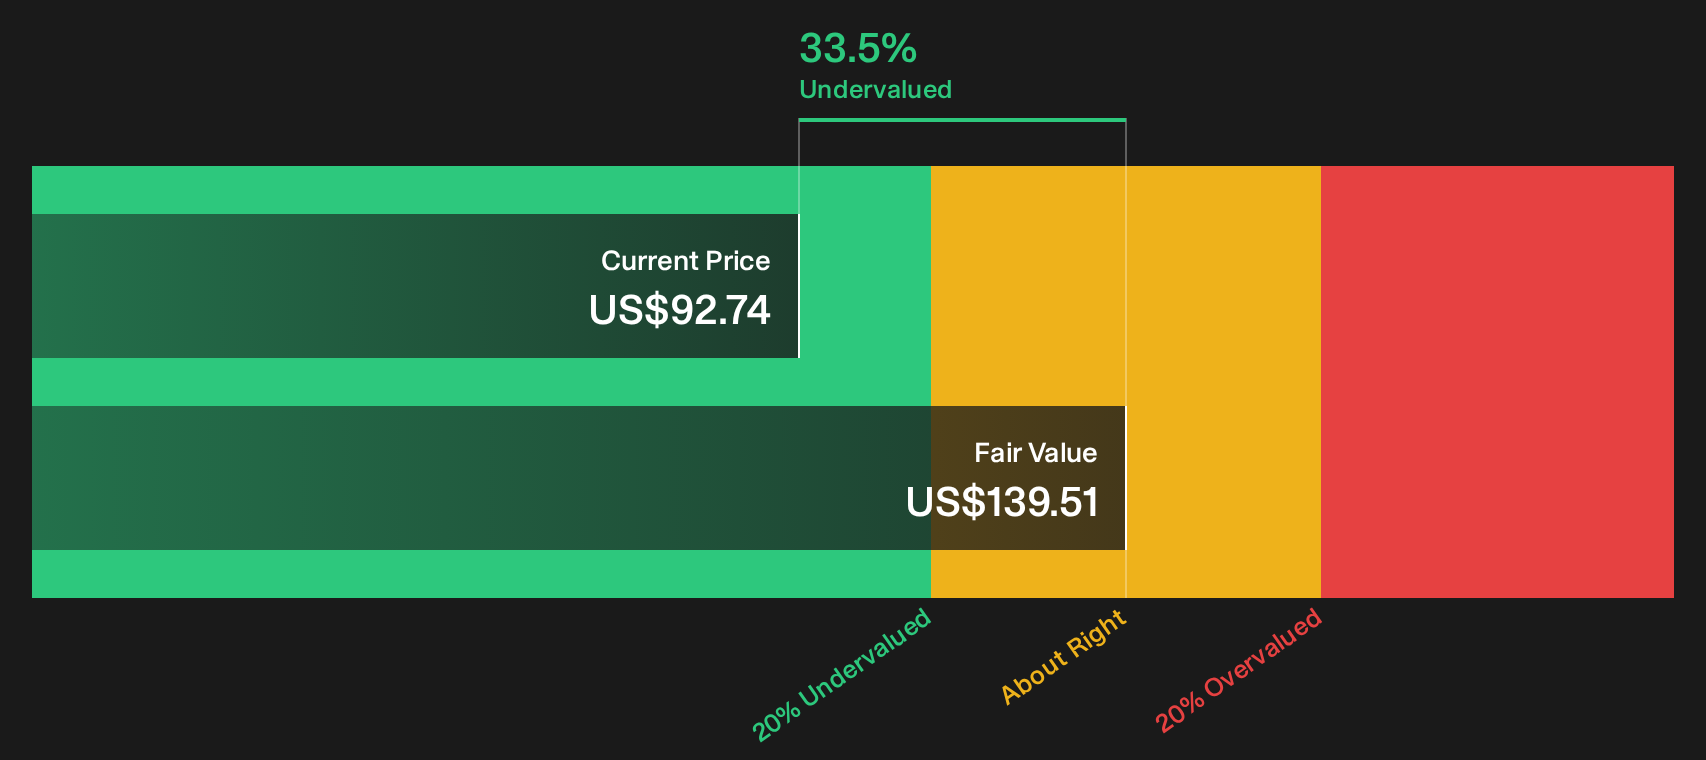
The SWS DCF model values Hexcel at $139.51 per share, compared with the current $92.74 price. That implies the stock trades at a 33.5% discount to estimated future cash flows, even though the present P/E of 45.7x screens as expensive against a fair ratio of 28.1x.
Put simply, the earnings multiple signals valuation risk, while the cash flow work suggests underpricing. The question for you is which signal you trust more: the high P/E today, or the long run cash flow profile implied by the DCF.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals across Hexcel’s valuation and narrative make this a live debate. Move fast, review the numbers, and weigh up the 3 key rewards and 1 important warning sign.
Looking for more Hexcel sized investment ideas?
If Hexcel has sharpened your thinking, do not stop here. Broaden your watchlist with a few targeted searches that could surface your next strong idea.
- Target powerful recovery potential with the 20 elite penny stocks with strong financials that combine small size with more established financial strength than many investors expect.
- Zero in on pricing opportunities by scanning the 31 high quality undervalued stocks that pair healthier balance sheets with lower implied expectations.
- Prioritise resilience and sleep better at night by focusing on the 11 resilient stocks with low risk scores that clear tighter checks on volatility and fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com