


Expand Energy stock has nearly doubled over the past five years, yet the broader valuation checks still point to a company that looks cheap rather than fully priced in. Recent share price softness contrasts with a high value score and an undervalued read on market multiples, which puts the current level under closer scrutiny for long term investors.
- Expand Energy has returned about 96% over five years, which suggests long term holders have already seen solid gains even as the recent trend has cooled.
- Rising Gulf Coast gas demand and the Twin Eagle asset can support revenue and cash flow expectations, while heavy exposure to commodity prices remains a key risk for how the market values those earnings streams.
- The broader checks lean cheap, with a high value score that rates Expand Energy at 6 out of 6 on value screens.
The issue now is whether the recent pullback leaves enough potential in Expand Energy for new money at around the current price.
Scan beyond Expand Energy and identify other potential deep value plays with 31 high quality undervalued stocks that share a similar mix of strong fundamentals and market hesitation.
Is Expand Energy Still Cheap on Earnings?
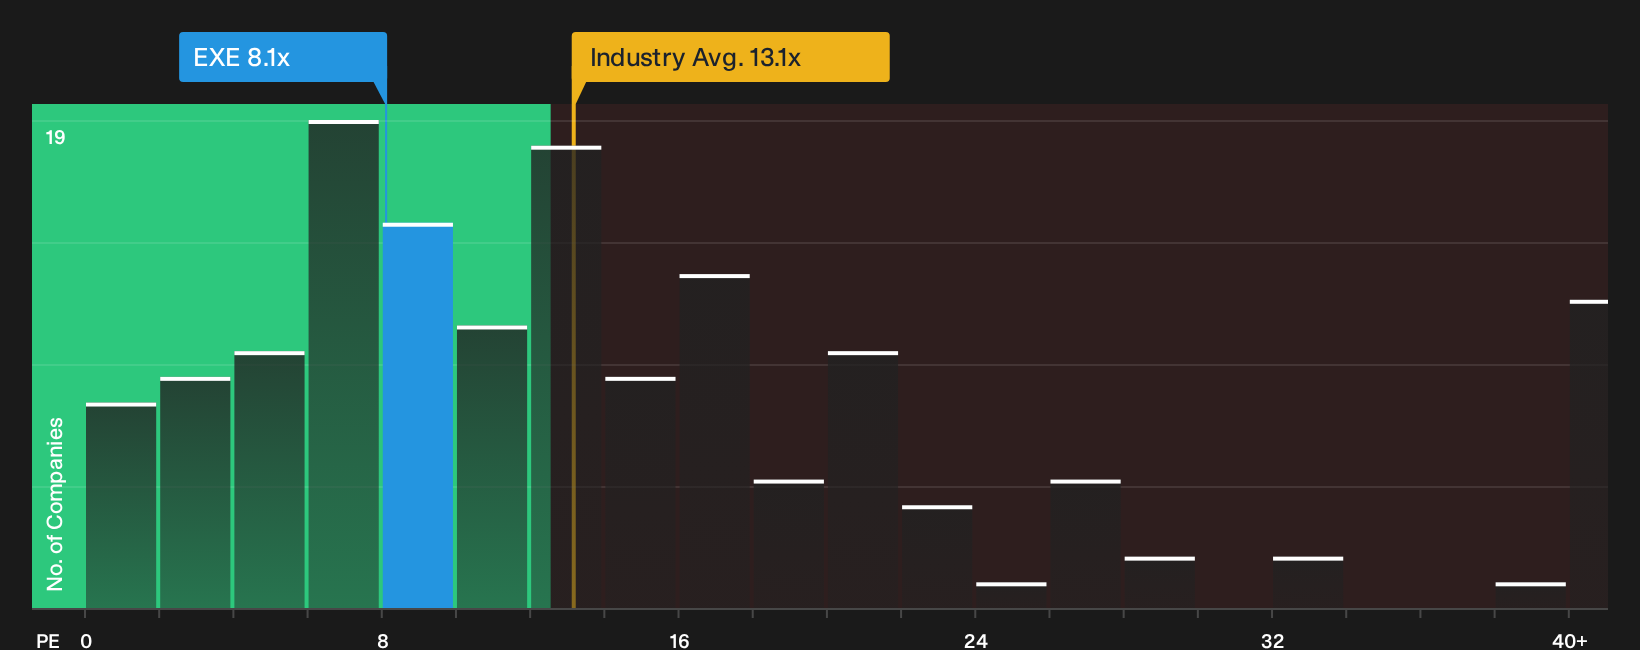
The P/E ratio suits Expand Energy because earnings sit at the center of how investors judge a cyclical producer like this. On that metric, the stock trades at about 7.9x earnings, which is well below the Oil and Gas industry average of roughly 13.0x and far under the peer group near 56.4x. That is a wide gap for a business that already reports profitability and significant free cash flow.
The fair P/E multiple implied by the broader checks is about 16.4x, which is more than double where Expand Energy changes hands today. Even with recent headlines around Gulf Coast demand and the Twin Eagle asset helping the story, the current earnings multiple still prices the shares at a sizable discount to what this framework suggests could be reasonable.
On a P/E basis, Expand Energy appears undervalued relative to both its own earnings profile and the benchmarks implied by these models.
See what the numbers say about this price — find out in our valuation breakdown.
The Expand Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle on Expand Energy leaves off by spelling out the mix of growth, margin and earnings paths that would need to play out for the valuation gap to close in either direction. Each scenario ties a specific fair value estimate to a clear set of potential catalysts and risks on Expand Energy's Community page, so you can watch over time which version of the story lines up with reality.
Community views on Expand Energy now span a wide range, from deep value upside to a much more cautious read on what comes next.
Bull case: 41% undervalued
"Meaningful breakeven reductions in the Haynesville, supported by self-sourced sand, completion design upgrades and drilling efficiency gains, position the company to prioritize its lowest cost inventory and potentially support stronger net margins and earnings through commodity cycles…"
Read the full Bull Case to see why Expand Energy could be undervalued
Bear case: roughly fairly valued
"Although management is targeting roughly $0.20 per thousand cubic feet uplift from marketing and premium market access, execution risk around building out trading, storage and downstream relationships in Houston could limit the actual improvement in realized pricing and keep revenue and EBITDA closer to current levels…"
Read the full Bear Case to see why Expand Energy could be overvalued
Do you think there's more to the story for Expand Energy? Head over to our Community to see what others are saying!
The Bottom Line
On the numbers, Expand Energy still screens as undervalued on market multiples, even after a solid five year run. The high value score aligns with that signal and points to a set of checks that lean supportive rather than cautious. What really decides it from here is whether management can translate Gulf Coast gas demand and the Twin Eagle asset into steadier earnings while handling commodity swings. The key question is whether the discount reflects opportunity or if the market is correctly pricing execution risk in marketing, trading and premium access.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com