


A 1.4% pop in Adobe on Friday is a polite clap, not a standing ovation, for what just landed. Traders nudged the stock higher while the actual report shouted something louder. Q3 revenue reached US$6.76b and non GAAP earnings per share came in at US$6.13, both solid for a mature software heavyweight. Yet the real story sat in fast building recurring cash flows. Annualized recurring revenue hit US$27.5b, a figure that speaks directly to durability, even if the short term price move suggests investors are still testing how much of that they truly believe.
Love Adobe's expanding recurring revenue base but unsure if you want so much exposure to one mature software giant? Take a look at our screener of list of solid balance sheet and fundamentals stocks (23 results).
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$6,760m vs. US$5,988m (up roughly 13%)
- Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025): US$1,827m vs. US$1,772m (up about 3%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$4.63 vs. US$4.18 (up around 11%)
- Annualized Recurring Revenue, ARR (Q3 2026 vs. Q3 2025): US$27.5b vs. US$24.75b (up roughly 11%)
Tired of slogging through earnings tables and dense commentary on Adobe? See the whole picture in one place with an at-a-glance view of its valuation and key drivers in our company report for Adobe.
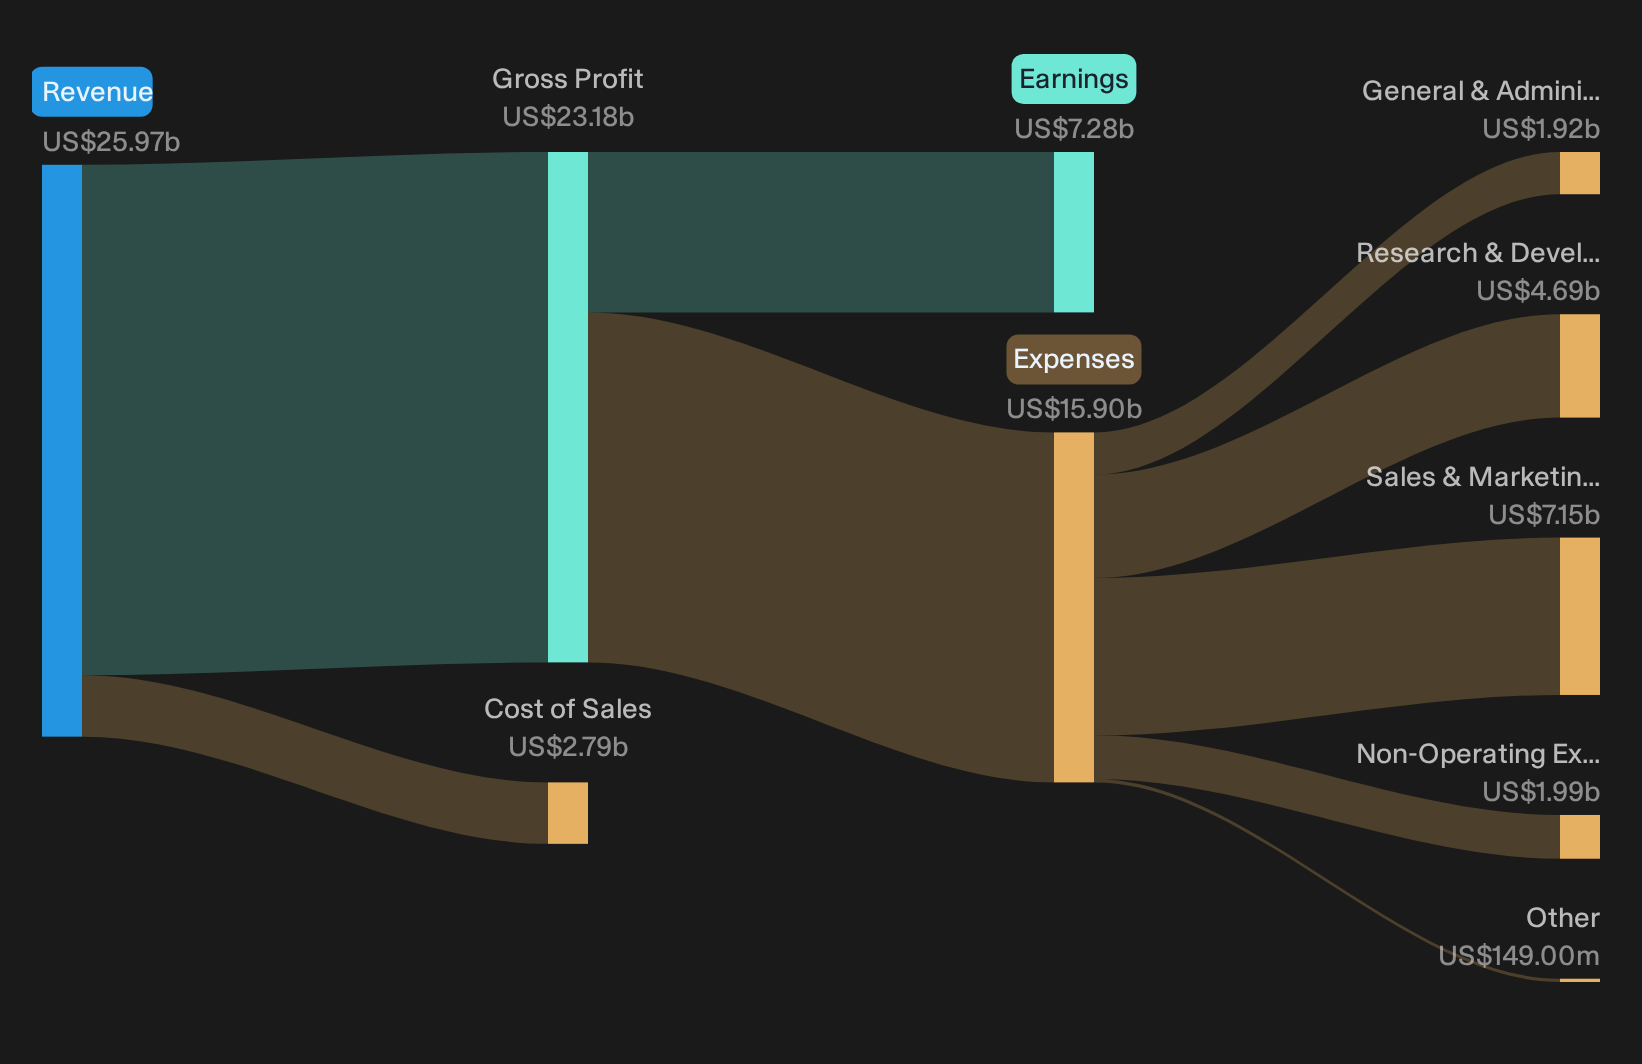
Adobe’s AI Freemium Bet Starts To Show Its Work
The bullish story says Adobe’s AI first, freemium pivot is intended to turn sheer usage into higher value subscriptions and sturdier cash flows. Q3 offers some real proof points. Acrobat and Express now exceed 900m monthly active users, up 25% year on year, while creative freemium products have passed 100m monthly users, up 70%. That is the wide funnel the thesis requires.
Monetisation is not just a promise on slides. Firefly ending annualised recurring revenue rose 40% quarter on quarter and total ARR reached US$27.5b, up 11.2% year on year. Management also called out accelerating AI credit consumption and raised full year revenue and EPS guidance. Record Q3 cash from operations of US$2.52b indicates that the AI and freemium push is being funded from internal cash rather than stretching the balance sheet.
Compare whether Adobe’s record Q3 cash generation and rising AI driven ARR are shifting institutional conviction or leaving analysts unconvinced, and see how those views stack up in the consensus price target analysis for Adobe.Adobe Bears Still Waiting On Freemium Payoff
The bearish line on Adobe says a swelling free user base slows monetisation, weighs on annualised recurring revenue and arrives just as leadership turns over. Q3 does not fully clear that bar. Total ARR sits at US$27.5b, up roughly in line with recent quarters, which means the surge to more than 1b monthly active users has not yet converted into a visible step up in subscription momentum. Firefly ARR growing 40% quarter on quarter shows appetite for paid AI features; however, that strength is concentrated and not broad based across the portfolio.
Management lifted full year ARR growth targets to 10.2% and raised EPS guidance, so fears of an immediate freemium driven slowdown are not playing out in the income statement. Bears arguing that execution risk rises with a CEO and CFO transition still have a live concern, because this print arrives before the new leadership team has set out a detailed medium term plan.
With earnings growth slowing from the five year pace and margins now at 28% rather than 30%, you need to verify how much balance sheet strength is really backing this story. Analyze the financial health analysis of Adobe stock.Stay Ahead With Simply Wall St
If Adobe’s rising annualized recurring revenue and growing AI user base are on your radar, register free with Simply Wall St and add it to a Watchlist to track price against fair value and spot a potential entry point that fits your plan. After you build a position, keep your holdings focused with the Portfolio Command Center so you only see clear, actionable updates instead of day to day noise. For longer term conviction, tap into the Community to see how other investors are thinking about the same risks and opportunities. That way you pick up on hidden catalysts or warning signs early and give yourself a better shot at staying ahead of the broader market.
Seeking Alternatives Before Momentum Flies Past?
Fresh breakouts do not wait. When capital starts moving, the best entry points get caught quickly and information goes stale fast. Scan under the radar opportunities now and review ideas early.
- Explore strong income streams while prices are still catching up by reviewing the 6 dividend fortresses packed with cash generative businesses that aim to keep payouts flowing.
- Look for the next wave of AI-related momentum by scanning the 74 profitable AI stocks that aren't just burning cash where cash generative operators pair real earnings with exposure to powerful themes.
- Consider resilient compounding potential before it is fully reflected in prices by checking the 11 resilient stocks with low risk scores curated for sturdier balance sheets and steadier risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com