


Atkore has delivered a strong 56.7% return over the past year, yet valuation checks suggest the stock now trades close to its estimated intrinsic value rather than offering obvious cheapness.
- The 1 year gain of 56.7% sets a high bar for fresh buyers who are weighing how much of Atkore’s cash flow story is already reflected in the price.
- Future cash generation from its electrical and infrastructure products can support the current share price, while any pressure on volumes or pricing could quickly weigh on those cash flow expectations.
- With a low overall value score of 2 out of 6 checks, Atkore screens as more on the expensive side than a clear bargain when viewed across multiple valuation angles.
The issue now is whether Atkore’s current US$94.15 share price leaves enough room above the intrinsic value estimate to justify the risk you take on as an investor.
Stress test Atkore’s 56.7% 1 year surge against other cash generative industrials by scanning the solid balance sheet and fundamentals stocks screener (23 results) for potential alternatives that sit on sturdier fundamentals.
Does Atkore Look Fairly Valued on Cash Flow?
The Discounted Cash Flow (DCF) model looks at what Atkore’s future cash generation could be worth today. For Atkore, the latest twelve month free cash flow figure is a small outflow of about $6.9 million. The model assumes that cash generation recovers into steady positive territory over time based on analyst estimates.
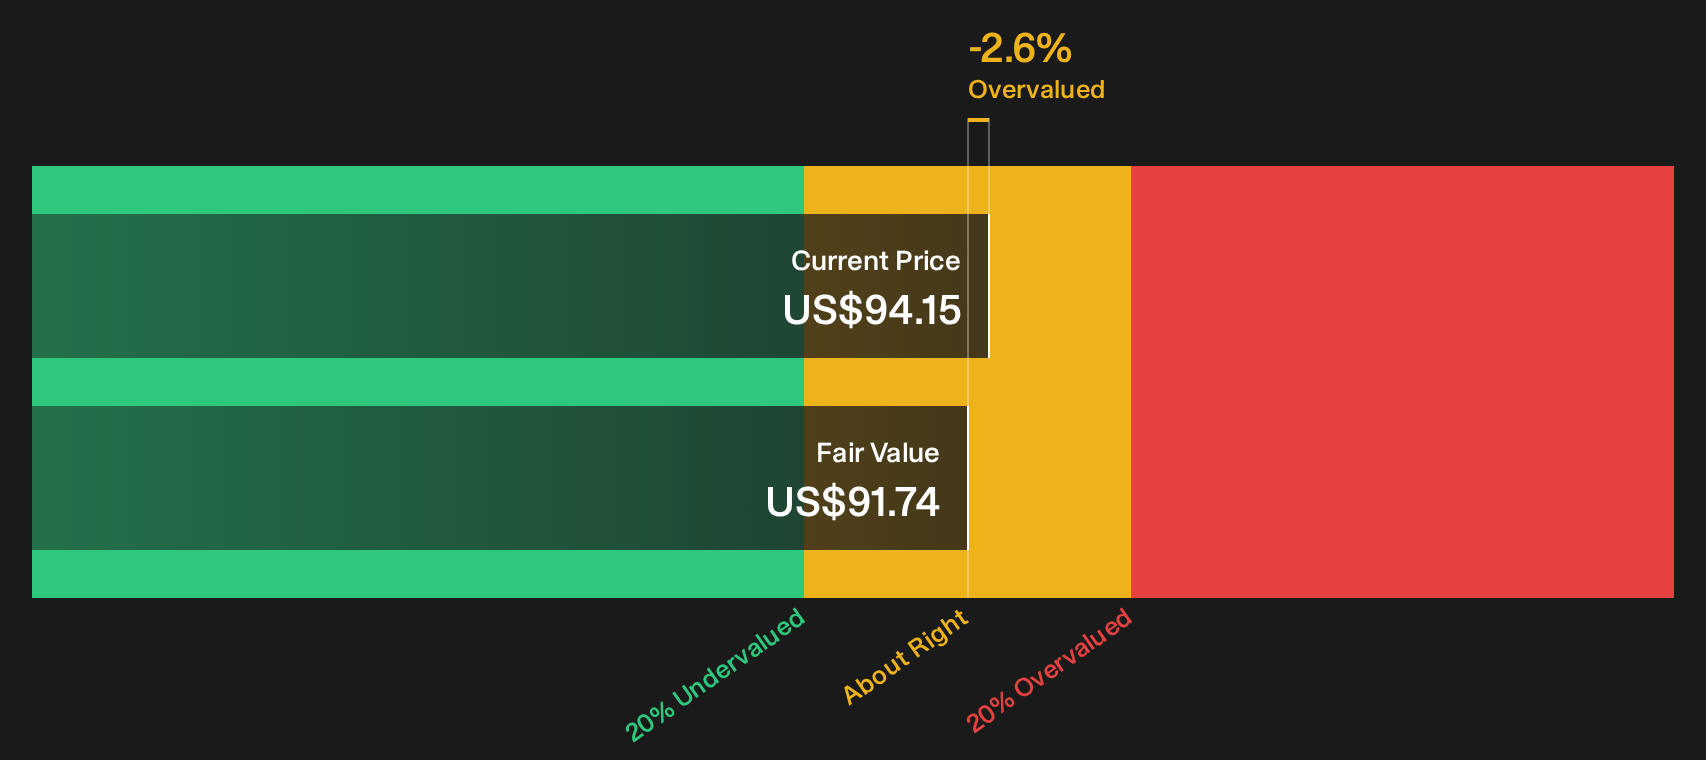
On those projections, the DCF model points to an intrinsic value of about $91.74 per share. That sits slightly below the current $94.15 share price. This implies the stock trades about 2.6% above this intrinsic value estimate and screens as only marginally overvalued rather than dramatically mispriced.
On this cash flow view, Atkore appears roughly fairly valued with a slight tilt toward being overvalued at the current share price.
Atkore is fairly valued according to our Discounted Cash Flow (DCF), but this can change at a moment's notice. Track the value in your watchlist or portfolio and be alerted on when to act.
Where Does Atkore Sit on Sales?
Price to sales fits Atkore reasonably well because investors often look at how much they are paying for each dollar of revenue in capital goods businesses where earnings can be cyclical.
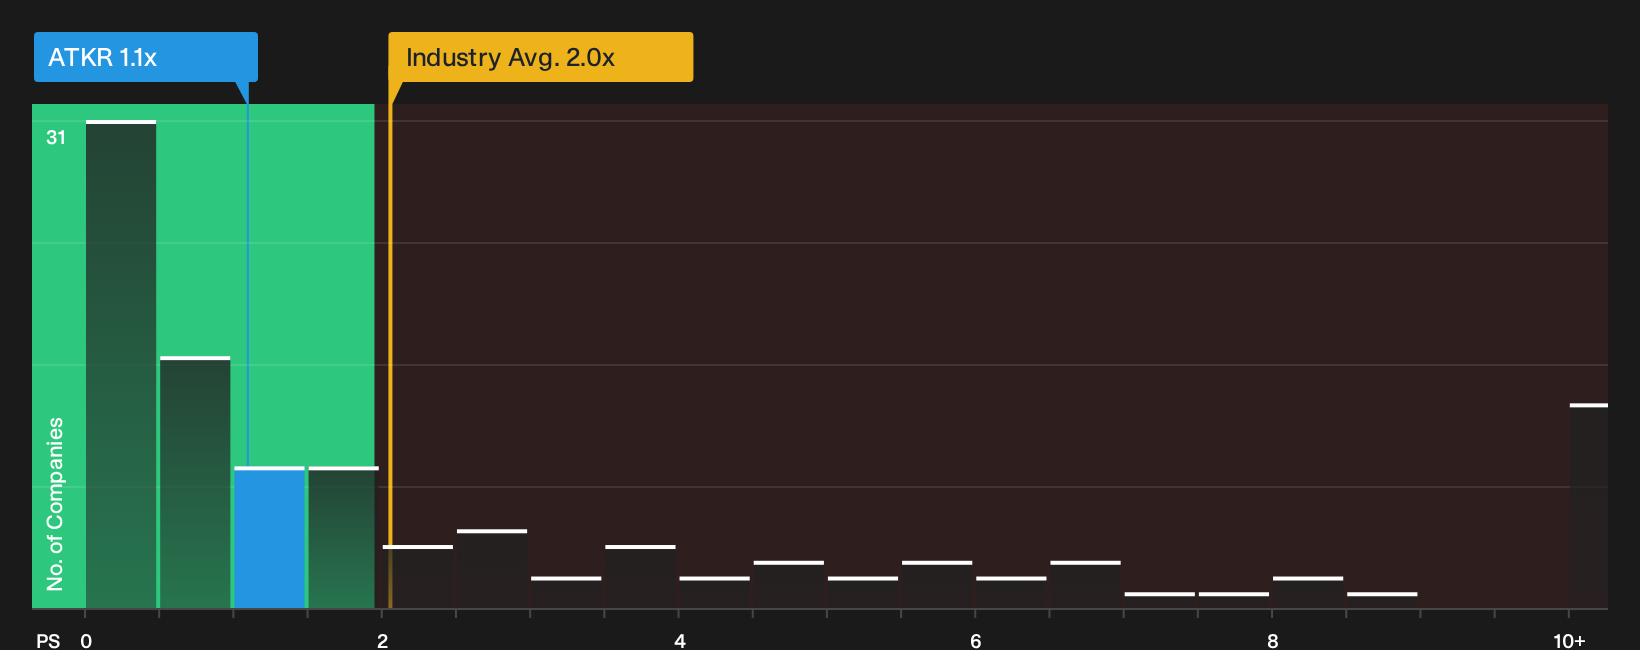
Atkore trades on a P/S of about 1.1x, which is roughly half the Electrical industry average of 2.0x and also below the peer group level of about 2.2x. The tailored fair P/S ratio for Atkore is 1.0x, which sits only slightly under the current market level. That gap is small enough that the stock does not screen as obviously cheap or expensive on sales alone.
For a reader weighing the earlier cash flow work against this simpler revenue yardstick, the picture is consistent. The market is not paying a premium P/S multiple for Atkore, but it is also not applying a big discount relative to what the fair ratio model suggests.
On the P/S measure, Atkore looks roughly fairly valued with only a mild deviation from the modelled fair multiple.
See what the numbers say about this price — find out in our valuation breakdown.
The Atkore Narrative: What Would Justify Today's Price?
Atkore’s valuation story raises a simple question for you as an investor. What has to happen to growth, margins, and earnings for this share price to make sense, or to move meaningfully higher or lower from here? Narratives on Simply Wall St’s Community page are built to spell out those assumptions in plain terms, and each one treats fair value as a thesis about Atkore’s business that you can watch play out over time.
You can add your voice to the Atkore story by sharing a narrative that provides a clear, number-driven view on where its growth, margins and execution go from here.
Set out your case on Atkore, then track how it compares with the actual results as new data arrives.
Do you think there's more to the story for Atkore? Head over to our Community to see what others are saying!
The Bottom Line
Atkore now screens as roughly fairly valued, with the Discounted Cash Flow (DCF) view and the sales multiple both clustering close to the current price. That combination, alongside a low overall value score, suggests limited valuation support if sentiment cools or operating performance stumbles. The key question from here is whether Atkore can keep cash generation and margins resilient enough to justify holding a full price tag rather than offering a clear discount.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com