


Designer Brands stock slipped 1.8% to US$5.88 after the earnings release, which might look like a shrug from the market, yet the quarter told a sharper story. This is a retailer often viewed as a low-growth mall staple, but Q2 showed a different picture with adjusted gross margin at 47.9% and adjusted operating income at US$39.4m. The big swing factor was profit quality. A US$20.2m tariff refund lifted results, while underlying assortment and inventory choices did some of the heavy lifting on their own.
Is Designer Brands really trading at a discount, or does the mix of a 17.1x P/E, modest 1.4% forecast revenue growth, and weak interest coverage point to a value trap instead? Compare the current US$5.88 share price against the detailed cash flow assumptions and peer multiples in our valuation analysis for Designer Brands
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): US$730.6m vs. US$739.8m (slight decline in quarterly sales)
- Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): US$17.6m vs. US$10.8m (profit improved meaningfully year on year)
- Basic EPS (Q2 2027 vs. Q2 2026): US$0.31 per share vs. US$0.22 per share (earnings per share increased)
- Same Store Sales Growth (Q2 2027 vs. Q2 2026): decline of 2.4% vs. decline of 5.0% (store productivity remained down, but the rate of contraction eased)
Tired of wading through dense earnings decks and spreadsheets just to understand Designer Brands? Get a clear visual overview of the company, including how valuation compares with the recent profit mix, in the full company report for Designer Brands.
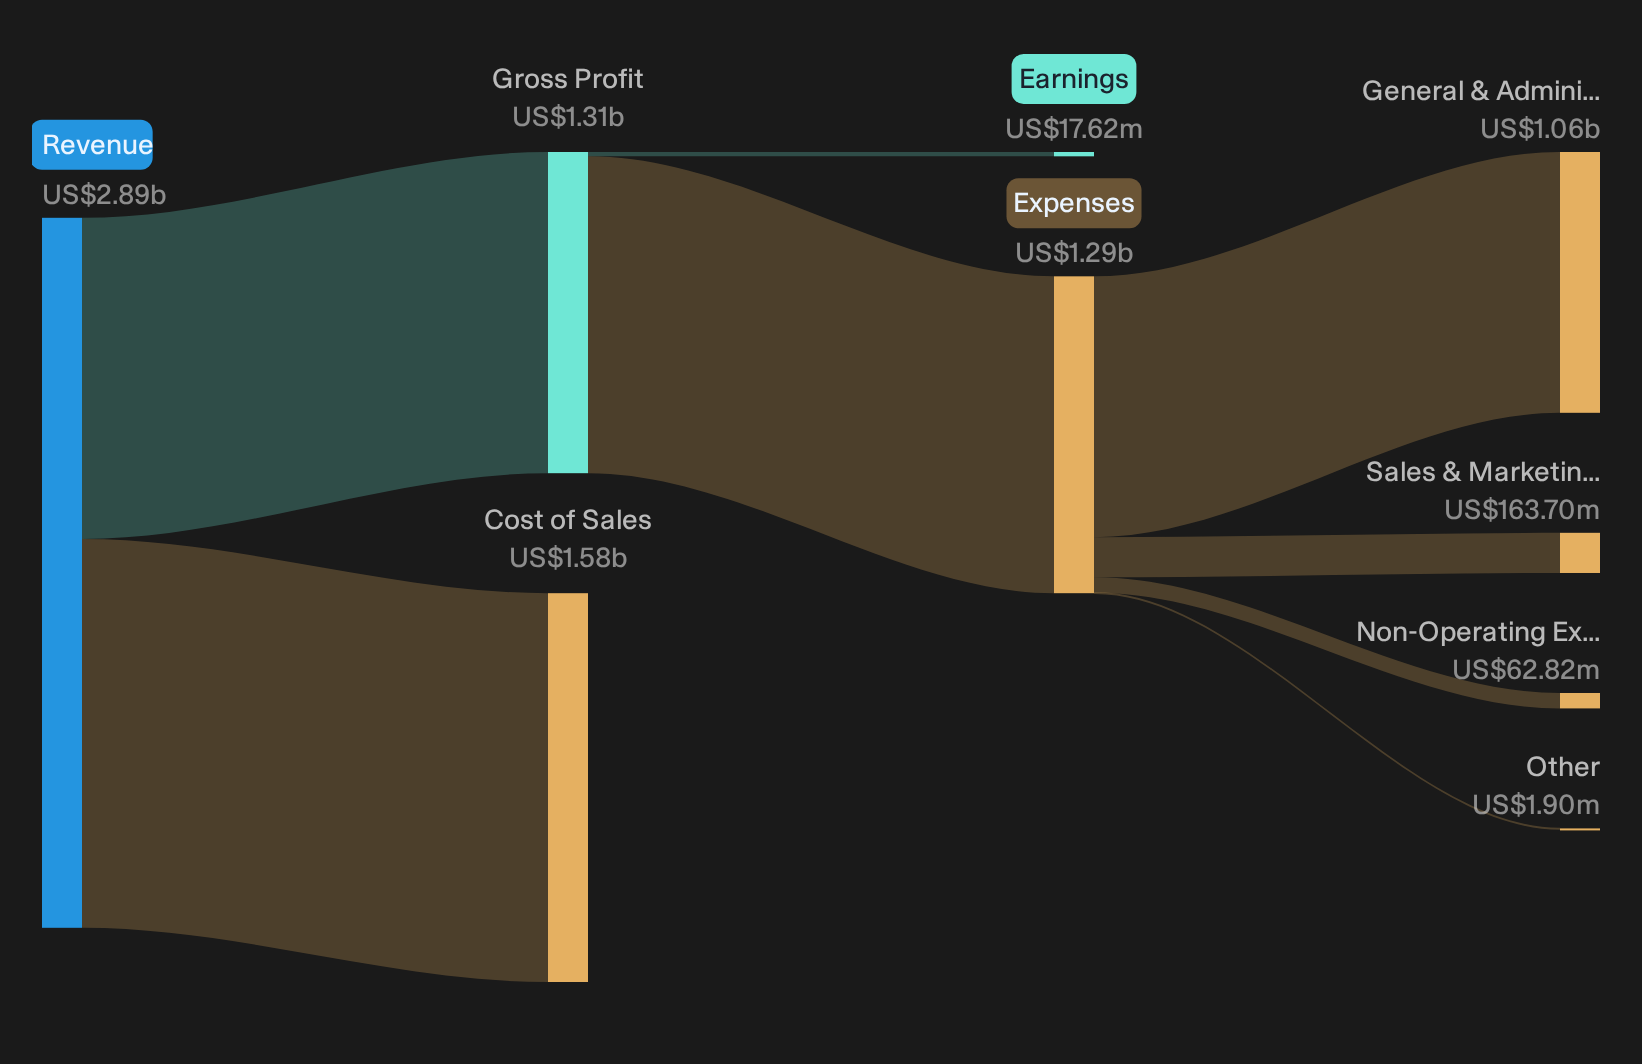
Designer Brands earnings keep the bullish story alive
For anyone leaning bullish on Designer Brands, the latest quarter gives some backing. Revenue slipped slightly and comps declined in the low single digits, yet adjusted gross margin reached 47.9% with roughly US$7m of improvement tied to cleaner assortments and tighter markdowns. Brand Portfolio revenue grew about 18%, with Topo and Jessica Simpson each up roughly 24%, which fits the idea that owned labels can carry more of the load. Debt moved down by about US$93m year on year and liquidity sat near US$198m, which strengthens the vertically integrated platform argument.
Soft sales and one offs keep the bear case in play
The cautious view on Designer Brands still has some traction. Store productivity fell again, with comps down about 2% to 2.6%, and total net sales edged lower to US$730.6m. A US$20.2m tariff refund added roughly 280 basis points to gross margin, which flatters underlying profitability and sets a tougher comparison once that benefit fades. Management flagged ongoing traffic pressure and seasonal volatility, especially around sandals, and also pointed to more profitability pressure in Q3, which keeps execution risk elevated even as the balance sheet improves.
After a quarter this reliant on tariff refunds and assortment tweaks, are these issues isolated or early signs of deeper fragility? Review our risk analysis for Designer Brands which shows 3 important warning signsShape Your Next Move With Designer Brands
Tariff refunds and shifting margins can move Designer Brands quickly, so register for free with Simply Wall St and add it to a Watchlist to watch how the share price tracks against fair value before deciding on an entry point. After you own any position, keep your view clear with the Portfolio Command Center that cuts through market noise and surfaces the updates that actually affect your thesis. For longer term thinking, tap into shared experience and debate through the Community so you can see how other investors are interpreting the same numbers. Spot potential catalysts and emerging risks early, and keep yourself a step ahead of the broader market.
Seeking Fresh Alternatives Beyond Designer Brands
Fresh ideas can move before headlines catch them, and once momentum builds, ideal entry points can be reached and then give way quickly. Scan these under the radar lists and consider them promptly.
- Spot potential breakout compounders early by tracking curated 16 high quality undiscovered gems that pair solid fundamentals with room for institutional interest to build before the crowd notices.
- Consider structural demand for critical materials by reviewing 29 best rare earth metal stocks that supply the hardware behind electrification and advanced tech while still remaining outside many portfolios.
- Explore income ideas that can help steady total returns by screening 6 dividend fortresses built around firms with high yields that the broader market is still pricing cautiously.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com