


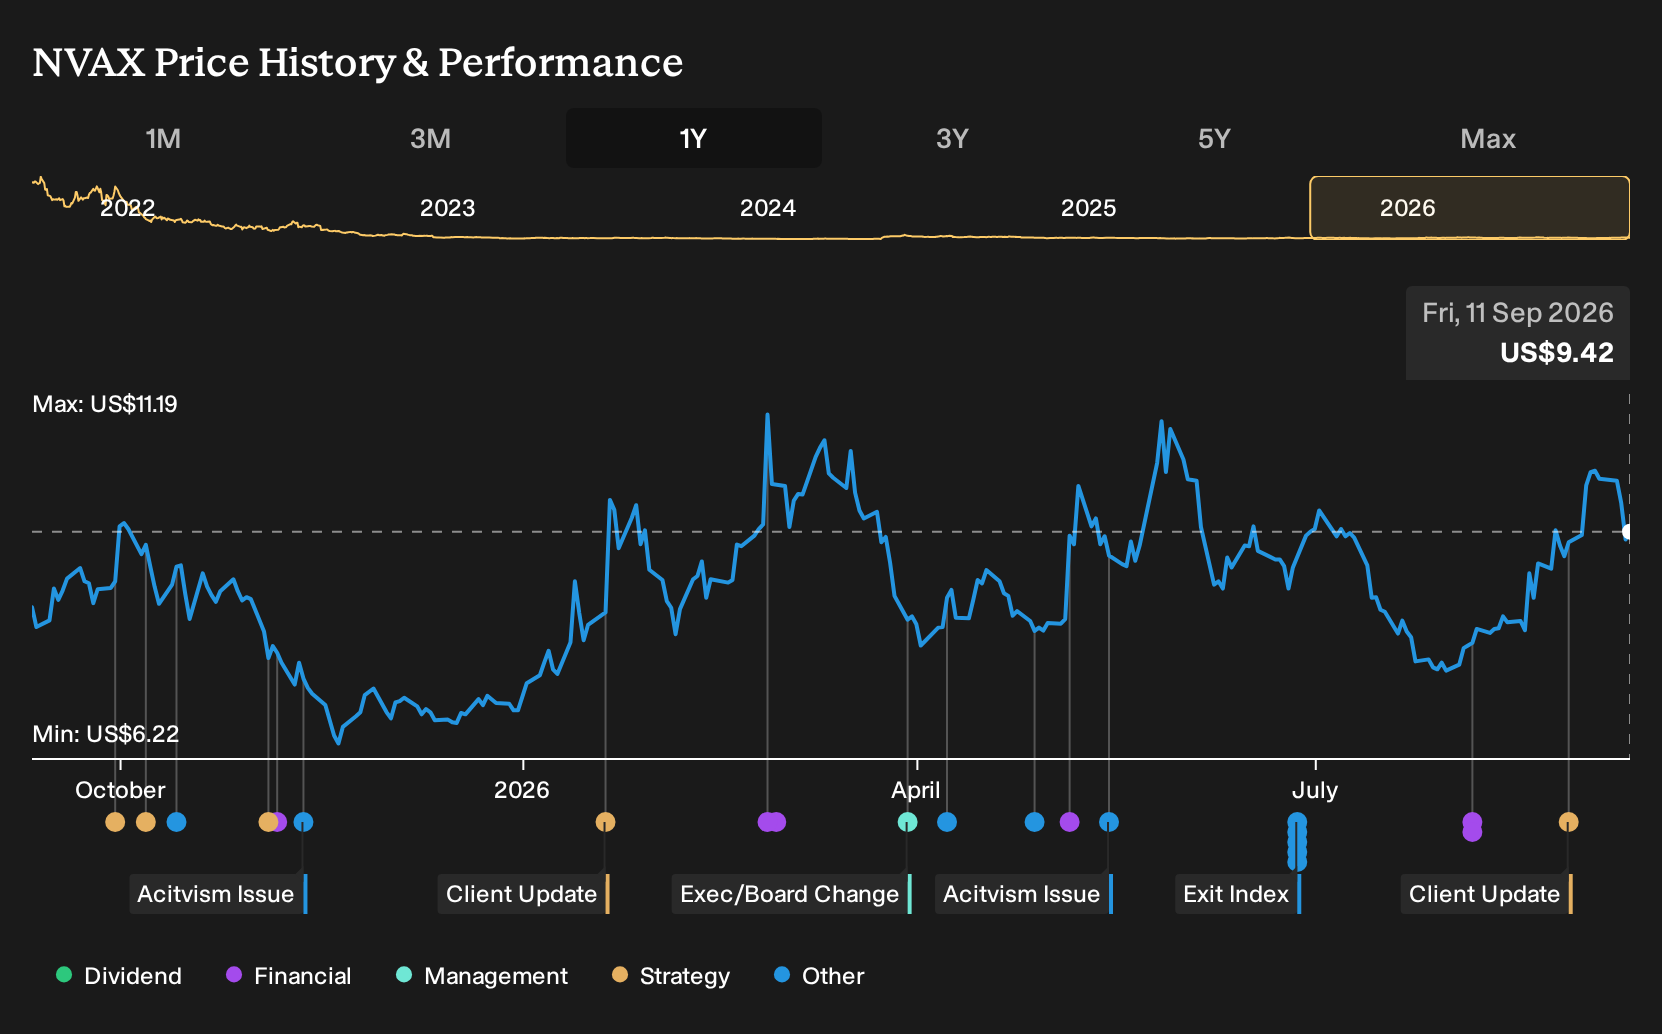
- Novavax presented its licensing-led vaccine and adjuvant strategy at Cantor Fitzgerald's Global Healthcare Conference and Citi's Biopharma Back to School Summit in New York, outlining how partners such as Sanofi and Pfizer are involved in commercialization and development plans.
- Management highlighted that upfront payments, milestones and technology transfers tied to Matrix-M partnerships are increasingly central to funding research, including early oncology work on "cold" tumors.
- We will now look at how Novavax's pivot to a licensing-led model could reshape its investment narrative and risk profile.
Novavax Investment Narrative Recap
To own Novavax, you need to believe the licensing led shift can turn Matrix M into a repeat royalty engine while the firm keeps COVID and other shots relevant enough to support partner interest. The short term focus still sits on near term cash generation, liquidity and progress on adjuvant backed programs without heavy internal spend.
The biggest swing factor remains how reliably partners convert pipeline and technology transfer steps into milestones and, eventually, commercial sales. The key risk is simple. If those programs slip or demand for COVID and combo vaccines softens, Novavax's already stretched balance sheet and negative equity position leave less room for error.
The most relevant recent development is Novavax using the September Cantor and Citi conferences to walk investors through its licensing heavy model. Those appearances matter because they give more clarity on how Sanofi, Pfizer and others may carry the load on COVID and combo respiratory shots, as well as early oncology work tied to Matrix M.
For you, the operational question is whether that model can smooth cash flows in time to support the path analysts expect to eventual profitability, without heavy dilution or extra borrowing. Execution on Sanofi related milestones and any updates on preclinical "cold" tumor data now tie directly into how credible that transition looks.
Novavax's current earnings of $422.8 million compare with analyst consensus expectations for $55.9 million of earnings and $348.5 million of revenue by 2028, with revenue forecast to decrease by 31.4% per year. This implies an earnings decline of about $366.9 million from today to the 2028 forecast level.
Uncover why Novavax's fair value indicates a 46% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Novavax focuses heavily on cash risk. Those analysts worry that milestone receipts could fade quickly and leave a funding gap. Before these New York conference updates, the most cautious models pointed to revenue of about $250.1 million and earnings of $47.5 million by 2029, far below consensus optimism. You can treat those lower figures as a stress test and compare them with your own expectations as new licensing details emerge.
Explore 2 other Novavax fair value estimates, including one that suggests it could be worth just $13.78!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Novavax research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Novavax. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Novavax's overall financial health at a glance.
Looking For More Investment Ideas Beyond Novavax?
Once you have a view on Novavax, it can help to compare it with other opportunities that share similar qualities, whether you care most about valuation support, balance sheet resilience or lower risk profiles. The Simply Wall St Screener lets you filter for those traits directly so you can build a watchlist that fits your own risk tolerance and return goals.
- If you want income to feel more predictable, start with companies that offer stronger yield support and review 6 dividend fortresses that may better align with a cash flow focused approach.
- For readers who care most about financial resilience, filter for businesses with cleaner leverage and liquidity and work through the list of solid balance sheet and fundamentals (23 results) to compare balance sheet strength side by side.
- If you are hunting for underfollowed ideas with room for the story to develop, scan through the 16 high quality undiscovered gems and see which profiles line up with your own return and risk checklist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com