


- EverPass Media announced a multi-year deal that expands commercial distribution of Netflix's NFL slate, giving bars and restaurants access to key 2026 games and events, including the Melbourne opener, Thanksgiving Eve, Christmas Day matchups, Week 18, and NFL Honors.
- Alongside this EverPass Media agreement, Netflix is pushing deeper into theatrical releases with longer runs and reported box office. This shifts part of its model toward traditional film revenue streams and new monetization channels beyond home streaming subscriptions.
- We will now look at how Netflix's expanded NFL commercial distribution could reshape the investment narrative around its content monetization.
Scan how Netflix's NFL deal fits into a wider content monetization trend by comparing it with 31 high quality undervalued stocks that could be primed for a similar breakout in investor attention.
Netflix Investment Narrative Recap
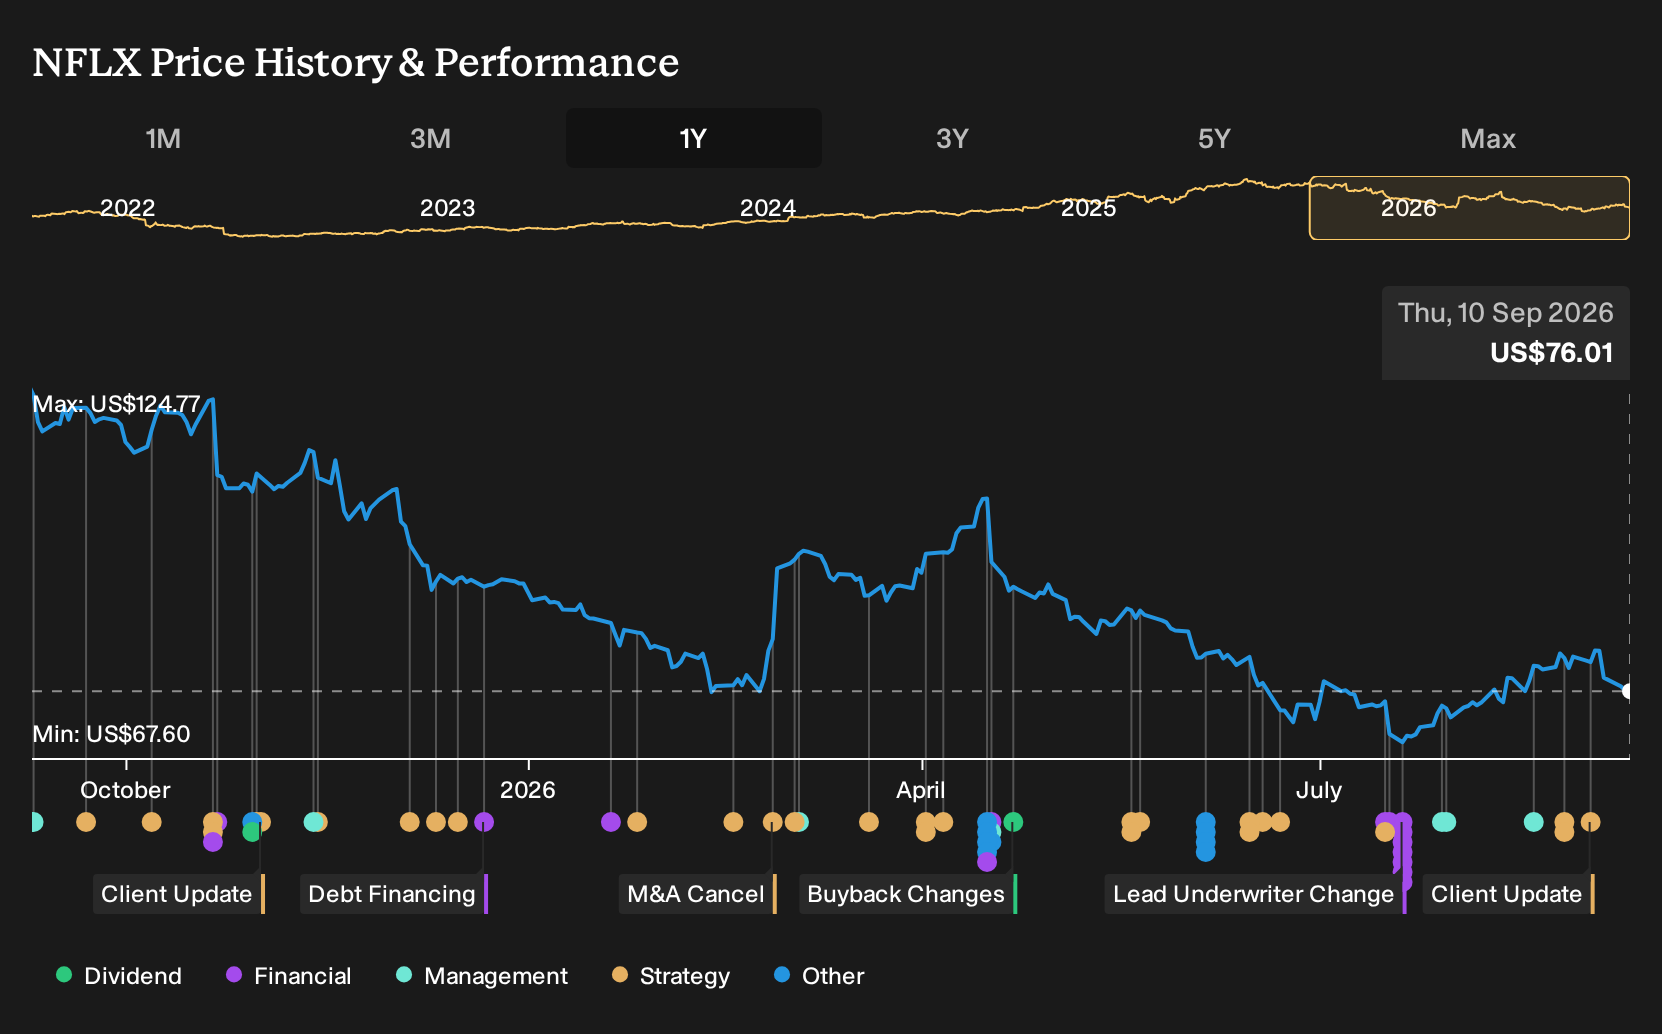
To own Netflix, you need to believe the platform can keep turning its giant content spend into rising engagement, advertising demand, and pricing power without letting costs run ahead of revenue. The near term hinges on whether new monetization levers, such as ads and live events, can support earnings after a Q2 outlook that disappointed some investors and coincided with share price pressure.
The expanded NFL footprint in bars and restaurants looks helpful for reach and brand strength but does not change the biggest near term swing factor, which is content profitability. The main risk remains that live sports, global originals, and theatrical pushes strain the budget if viewership or ad dollars do not scale as expected.
The move into longer theatrical runs, including reporting box office for titles like Greta Gerwig’s “Narnia, The Magician’s Nephew,” is the clearest companion to the NFL commercial deal. Both point to Netflix testing revenue streams beyond home subscriptions and into more traditional entertainment cash flows where every audience touchpoint can carry a price tag.
For you as an investor, the catalyst to watch is execution. Can Netflix align live events, theaters, and advertising with its existing subscriber base without letting complexity drag on margins that are currently 28.2% and above last year’s 24.6% level? If content spending tied to these experiments rises faster than monetization, the risk side of the story comes back into focus quickly.
Netflix's current analyst storyline points to US$65.5b in revenue and US$19.8b in earnings by 2029. That path assumes 10.6% yearly revenue growth and an earnings increase of about US$6.2b from the US$13.6b reported today.
Uncover how Netflix's fair value indicates a 21% potential upside to its current price. This upside could narrow quickly if sentiment turns more optimistic.
Exploring Other Perspectives
One alternate view sees Netflix’s live push as a big upside catalyst. The most optimistic analysts were already penciling in US$68.1b of revenue and US$21.8b of earnings by 2029, before this EverPass NFL expansion. That is a far richer story than the baseline, and it shows how sharply opinions can differ. Use this spread to test your own assumptions and explore which narrative you find more realistic as the impact of the new deal becomes clearer.
Explore 39 other Netflix fair value estimates, including one that suggests the potential for as much as 93% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Netflix research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Netflix. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Netflix's overall financial health at a glance.
Looking for more Netflix investment ideas beyond the headline?
If this NFL deal has you rethinking what drives Netflix's value, it can help to line it up against other opportunities with different strengths. Use the Simply Wall St Screener to spot companies that match the kind of risk, balance sheet quality, or income profile you want to pair with or contrast against Netflix in your portfolio.
- For investors who want potential upside but still care about fundamentals, scan through a curated 16 high quality undiscovered gems that could complement a position in Netflix.
- If capital preservation and steadier profiles matter more to you than headline stories, filter for 11 resilient stocks with low risk scores and see which businesses line up with your comfort level.
- Income focused investors who want to balance Netflix with cash returns can review a focused 6 dividend fortresses and see which payers fit their yield and stability targets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com