


Why IPG Photonics Is Back On Investors’ Radar
IPG Photonics (IPGP) is drawing attention after recent trading moves left the laser specialist with a market value of about US$3.3b and a last close near US$79.99 per share.
Recent trading has given IPG Photonics a short burst of momentum, with a 1-day share price return of 2.12% and a 7-day share price gain of 2.55%. However, this sits against a 90-day share price decline of 30.23% and a 5-year total shareholder return that is down 51.98%, so recent strength comes after a long stretch of weaker performance.
Compare the recent swing in IPG Photonics with a curated group of other potential rebound stories in 16 high quality undiscovered gems.
The rebound in IPG Photonics is small compared with the gap between its US$79.99 share price and analyst value estimates near US$126. Where does fair value actually land within that range?
Most Popular Narrative: 38.7% Undervalued
IPG Photonics is trading at $79.99 while the most widely followed valuation story points to a fair value near $130.50, creating a wide gap investors are trying to make sense of.
New growth initiatives in medical (e.g., thulium lasers for urology), semiconductor, and micromachining end-markets are gaining early traction, diversifying revenue streams and supporting higher margins over time as these higher-value verticals scale. Recent product innovations like the CROSSBOW directed energy system, validated with multiple unit deliveries and key partnerships (e.g., Lockheed Martin), open up opportunities in defense and critical infrastructure, supporting both revenue acceleration and improved operating leverage.
Want to understand why this narrative supports a higher fair value for IPG Photonics? It leans heavily on faster earnings growth, richer margins, and a premium future earnings multiple. Curious how those moving parts fit together and what kind of revenue mix shift is built into the model? The full narrative breaks down the assumptions in plain numbers and shows exactly how they stack up against that $130.50 figure.
Result: Fair Value of $130.50 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the IPG Photonics story can break if materials processing softness persists, or if heavy R&D and capex spending fails to translate into stronger profitability.
Find out about the key risks to this IPG Photonics narrative.
Another Angle On IPG Photonics’ Valuation
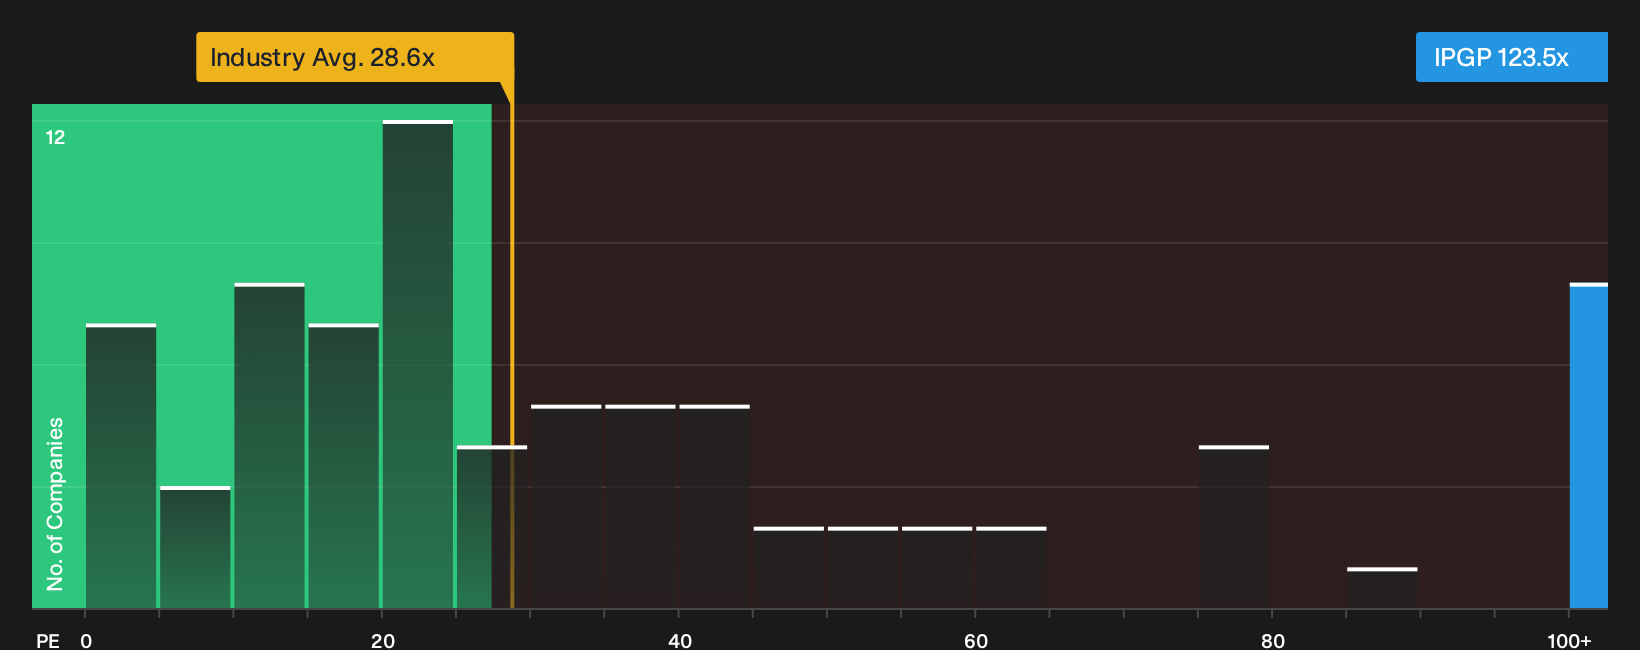
The first story around IPG Photonics leans on long range earnings forecasts and a future P/E that supports a higher fair value. A quick check against current pricing tells a different story. At a P/E of 123.5x, the stock trades far above the Electronic industry at 28.6x and well above peers at 37.6x.
The fair ratio for IPG Photonics sits near 58.7x, which is less than half the present multiple. That kind of gap can matter in practice, because it leaves less room if sentiment cools or forecasts are revised. Which lens do you trust more when the market is already paying up this much?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on IPG Photonics so far? Treat this as a starting point, move quickly with your own research, and weigh the 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond IPG Photonics?
Do not stop with IPG Photonics. Broaden your watchlist now so you are not chasing the crowd after the next big move shows up on the radar.
- Target potential mispricing by scanning a curated pool of steady cash generators and quality businesses using the 31 high quality undervalued stocks.
- Strengthen your downside protection by focusing on durable balance sheets and healthy fundamentals with the list of solid balance sheet and fundamentals (23 results).
- Catch opportunities the market has not fully paid attention to yet by reviewing the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com