


Inflation is heating back up, the Federal Reserve is leaning toward tighter policy, and higher-for-longer rates are quietly reshuffling winners and losers across U.S. large caps. That mix can reward balance sheets built for tougher funding costs and punish weaker business models. This article walks through 3 individual financial stocks exposed to the latest CPI and rate hike odds, and explains why their stories might matter for your portfolio decisions.
The three stocks below are just a sample, since the full screen surfaced 35 more large-cap banks and insurers with equally compelling stories that are not covered here. To go deeper into this idea, analyze and compare the full field of candidates through the U.S. Large-Cap Financials (Banks and Insurance) screener.
First Mid Bancshares (FMBH)
First Mid Bancshares is a US community-focused financial holding company that leans heavily on traditional banking, with all of its US$373 million revenue coming from banking activities that fit the screener’s size, quality and rate-sensitive profile. The stock is valued at about US$1.4b.
First Mid Bancshares ties directly into the higher rate theme. It runs a classic spread-based banking model serving commercial, retail and agricultural borrowers, and earns strongly from net interest income. Earnings growth, solid net profit margins and a modest P/E all align with the screener’s focus. However, what happens when revenue trends and rate-sensitive income push against each other will be important for investors.
Those cross-currents are exactly what you can stress test through the DCF valuation analysis for First Mid Bancshares to see how rate scenarios might reshape First Mid Bancshares’ story.
ServisFirst Bancshares (SFBS)
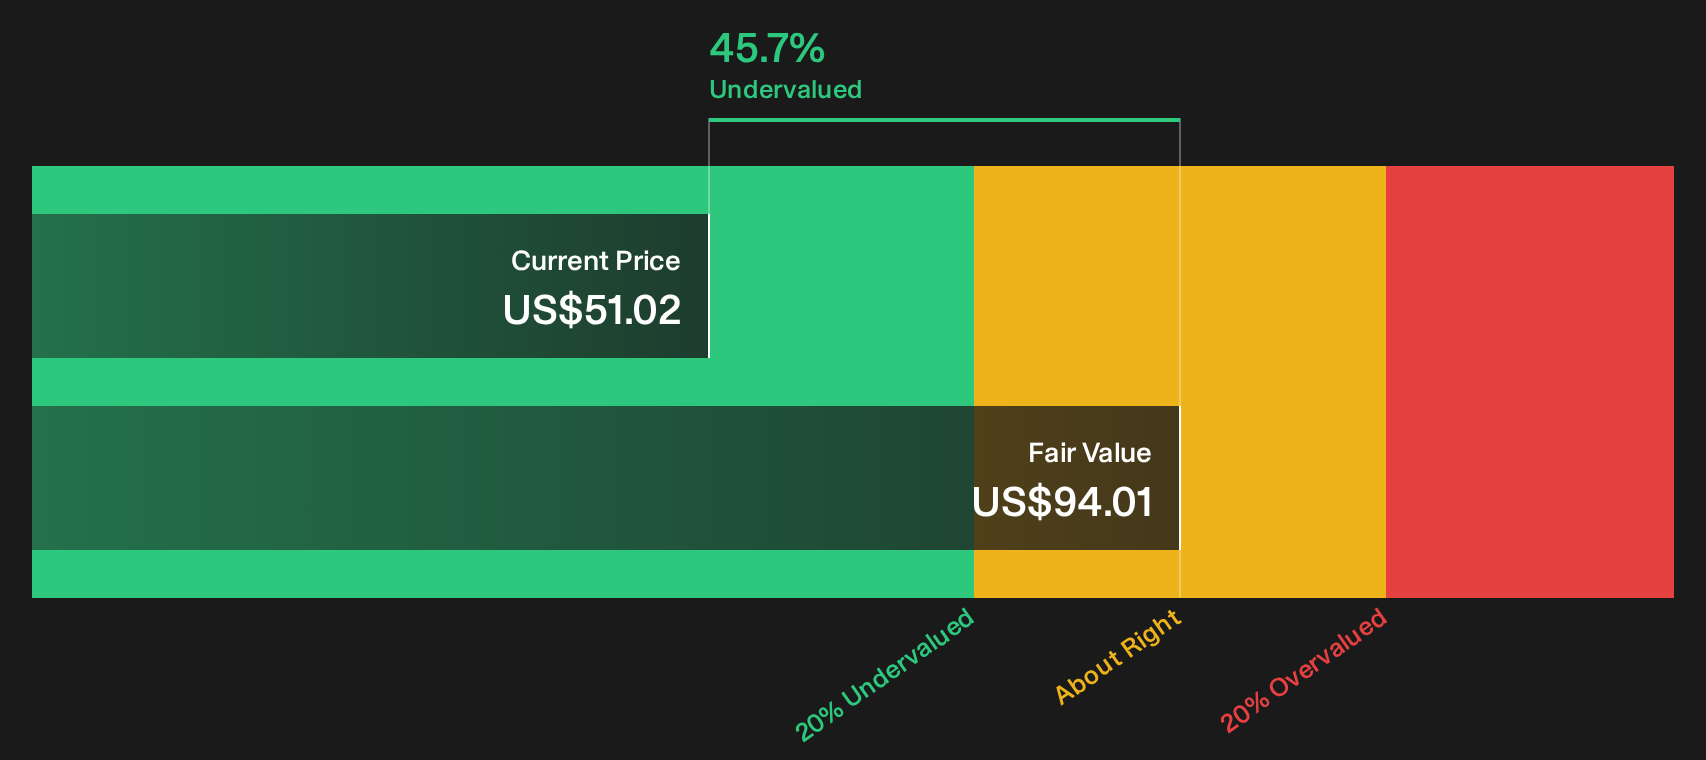
ServisFirst Bancshares is a Birmingham based bank holding company focused on commercial and personal financial services, generating about US$585 million from business and personal banking in the US, and carries a roughly US$4.6b market value that fits the large cap financials screener theme.
ServisFirst Bancshares links cleanly to the higher rate story because it lives off lending spreads in growing Sun Belt markets. This puts more weight on how its loan book, funding costs, and efficiency respond when borrowing stays expensive.
"Expansion of commercial lending teams and ongoing hiring in key Southeastern markets positions the company to capitalize on robust population and business growth in the Sun Belt, supporting above-average organic loan and deposit growth, which is likely to drive top-line revenue and long-term earnings growth."
What happens if one quiet pressure on funding costs shifts faster than ServisFirst Bancshares can reprice its loans and fees?
If that repricing risk is on your mind, read the full narrative for ServisFirst Bancshares to see how ServisFirst Bancshares’ loan growth and funding mix could be decoupling.

Northwest Bancshares (NWBI)
Northwest Bancshares is a regional bank holding company built around deposit-funded personal and commercial banking across several Midwestern and Northeastern states, generating about US$654 million from banking in the U.S., with a market value of roughly US$2.3b.
Rising rate expectations have pushed many investors toward banks that rely on core deposits and loan repricing, and Northwest Bancshares fits that profile within this large cap financials screen, particularly as management leans into efficiency gains and a tighter cost base.
"The successful completion and integration of the Penns Woods acquisition, with cost savings tracking ahead of original expectations and full run-rate efficiencies expected by mid-2026, should materially improve expense ratios and net margins going forward."
What really moves the needle from here hinges on how one less visible cost pressure interacts with that leaner expense base over the next few years.
That hidden cost pressure is exactly what the full narrative for Northwest Bancshares unpacks, mapping where Northwest Bancshares’ efficiency push could accelerate or quietly stall.

Curious About What You Might Be Missing?
Fresh ideas move first. Some stocks are building breakout momentum while others are quietly dropping under the radar for now. Do your homework before the crowd and consider your research early in the process.
- Spot income workhorses that aim to keep paying investors even when volatility picks up by scanning the 6 dividend fortresses.
- Track early movers in artificial intelligence infrastructure while the stories are still underfollowed by checking the 89 AI infrastructure stocks.
- Hunt for overlooked operators with improving financials and room for re-rating using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com