


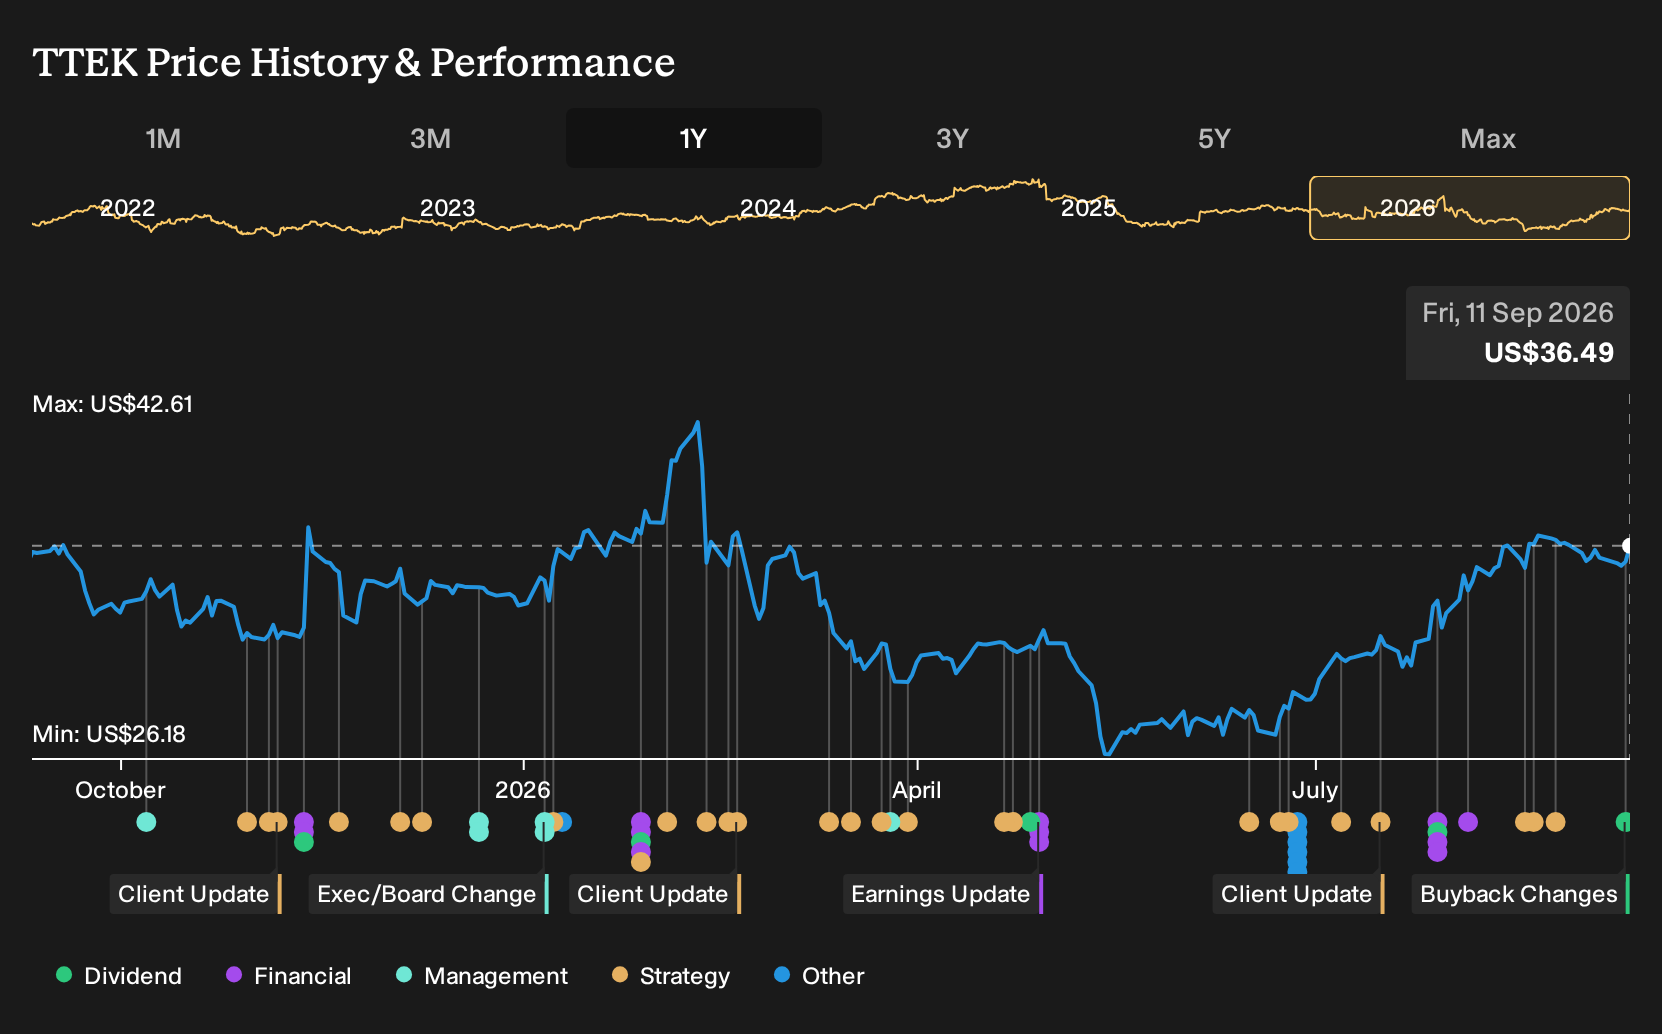
- Tetra Tech announced that its board approved an additional US$500 million share repurchase authorization, bringing the total current program capacity to US$898 million under a broader US$1.4 billion buyback framework.
- The enlarged repurchase pool highlights management’s willingness to deploy substantial capital into the business’s own equity. This tightens the share count over time and relies on Tetra Tech’s cash generation and balance sheet strength as key supports.
- We will now look at how Tetra Tech’s expanded US$500 million repurchase plan could reshape its long term investment narrative.
Tetra Tech Investment Narrative Recap
To own Tetra Tech, you need to be comfortable with a consulting and engineering business that leans heavily on government and infrastructure work, while pushing into higher value, tech led services. The expanded buyback does not change the near term swing factor. The key issue remains how quickly new public sector awards and task orders offset lapsed USAID and State Department work.
The biggest risk still sits in revenue concentration and timing. Disaster response projects and U.S. federal funding priorities can shift or fade, which can pressure margins that recently sat near record levels. The larger repurchase pool mainly highlights confidence in cash generation rather than altering these operational sensitivities.
The fresh US$500 million increase in buyback capacity connects directly to earlier commentary about Tetra Tech using its balance sheet and cash flow as part of the equity story. Analysts already expected earnings to grow modestly and shares outstanding to drift lower, and this larger authorization reinforces that capital return is a continuing part of the plan.
For you as an investor, the more interesting angle is how this program interacts with execution on water, sustainability, and federal infrastructure contracts. If state and local water programs and higher margin consulting work keep filling the order book, a sizable repurchase pool can amplify per share metrics. If commercial and international demand stay sluggish or federal budget mix tilts away from core areas, then the buyback alone will not offset softer project volume.
Tetra Tech's current analyst narrative points to revenues of US$4.5b and earnings of US$460.0m by 2029, with earnings today at US$440.2m. That earnings path implies an increase of about US$19.8m from current levels, while analysts are assuming revenue remains fairly flat over the next 3 years.
Uncover how Tetra Tech's fair value indicates an 8% potential upside to its current price before the discount window narrows.
Exploring Other Perspectives
One alternate angle focuses less on buybacks and more on slow moving project funding. The most cautious analysts were already assuming flat revenue, only modestly higher margins at 10.5%, and earnings of about US$475.1m by 2029. Those pre buyback views are more restrained, so you may want to compare several forecasts before reacting to Tetra Tech’s larger repurchase plan.
Explore 2 other Tetra Tech fair value estimates, including one that suggests it could be worth just $35.00.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Tetra Tech research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Tetra Tech. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tetra Tech's overall financial health at a glance.
Looking For More Ideas Beyond Tetra Tech?
If you want to put Tetra Tech in context, it helps to line it up against other businesses with clear balance sheets, disciplined capital return, or different risk profiles. The Simply Wall St Screener can help you quickly spot those contrasts and build a broader watchlist that fits your own style.
- For investors who prefer steadier businesses with stronger finances, scan a curated list of solid balance sheet and fundamentals (23 results) to see what else measures up on debt and liquidity.
- If value is your focus and you want candidates that combine quality fundamentals with pricing that may look appealing on key ratios, check out a targeted pool of 31 high quality undervalued stocks that share similar traits.
- For those hunting for under the radar opportunities with cleaner accounts and room to mature, review a focused set of 16 high quality undiscovered gems that could complement a core position in Tetra Tech.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com