


Eaton (ETN) has been drawing attention after reporting revenue growth of 15.5%, a P/E of 41.5, and fresh investments in both manufacturing capacity and digital tools, including the new Workbench 360 platform.
Eaton’s share price has been strong over the past year, with a year to date share price return of 29.96% and a 3 month share price gain of 8.68%. This comes even though the 1 month share price return is down 7.52% and near term momentum has cooled. Recent attention around the more than $242m North Little Rock expansion and the launch of Workbench 360 helps frame that move. A 1 year total shareholder return of 17.54% and a 5 year total shareholder return of 191.78% point to investors rewarding the longer term story more than just the latest project headlines.
Spot opportunities aligned with the same electrification and infrastructure themes as Eaton’s recent moves by scanning our hand-picked 39 power grid technology and infrastructure stocks.Eaton now trades on a rich P/E and has already delivered a strong year to date run, so the real tension is simple: Do you pay up today for the electrification story or wait and hope for a cheaper entry later?
Most Popular Narrative: 18% Undervalued
Eaton last closed at $425.37, while the most followed narrative on the stock anchors fair value near $517 per share. That puts the perceived valuation gap front and center for anyone weighing the current price.
"Eaton Corporation (NYSE: ETN) is one of the rare institutions that has managed to turn the physical constraints of heavy industry and metallurgy to its advantage. Its monopolistic position, benefiting from high material constraints (GOES), years-long delivery times, and in-cabinet thermal densities of 120 kW, along the Voltage Cascades from a 400,000-volt grid to 1 volt on a chip, has provided the company with an unsurpassable economic moat."
Read the complete narrative. Read the complete narrative.
Want to see how a power management specialist ends up priced like a critical AI infrastructure gatekeeper? The narrative leans heavily on projected earnings expansion, higher through-cycle margins, and a premium future profit multiple usually associated with fast growing tech suppliers. Curious which revenue paths, segment mix shifts, and long dated project backlogs are used to support that $517 figure over today’s $425 price? The full narrative lays out those assumptions in detail so you can judge the gap for yourself.
Result: Fair Value of $517 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Eaton’s story can break if AI infrastructure spending slows sharply or if transformer and GOES bottlenecks ease faster than this narrative assumes.
Find out about the key risks to this Eaton narrative.
Another View On Eaton’s Valuation
The user narrative leans on a premium earnings multiple to argue Eaton still looks undervalued around $425. Yet the SWS DCF model, which prices the business off future cash flows, points to a value of $318.3 per share and flags the stock as overvalued. Which framework do you trust more when the gap is this wide?
Look into how the SWS DCF model arrives at its fair value.
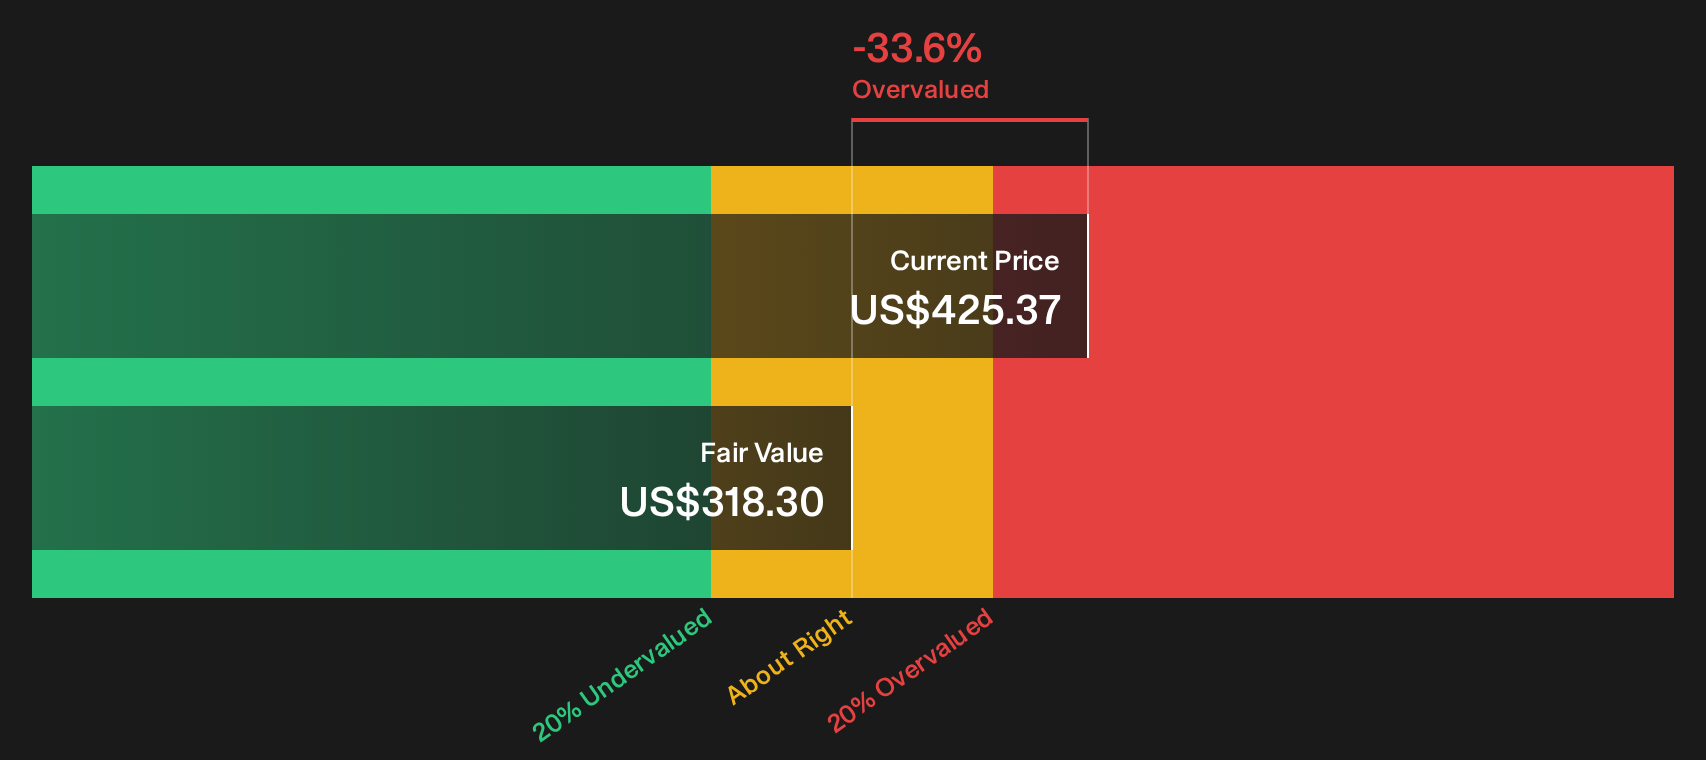
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Eaton for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Eaton’s valuation story so far. Act before sentiment shifts and review both sides for yourself by weighing the 1 key reward and 1 important warning sign.
Looking for more ideas beyond Eaton?
If Eaton’s story has you thinking bigger, use this moment to line up your next watchlist candidates before the crowd starts paying closer attention.
- Hunt for quality at a discount by scanning our hand picked 31 high quality undervalued stocks that match solid fundamentals with more modest pricing.
- Build a steadier income stream by checking out 6 dividend fortresses that combine yield with staying power.
- Dial down portfolio stress and focus on durability through 11 resilient stocks with low risk scores tailored for resilience when conditions change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com