


- Peoples Bancorp is in focus after recent commentary highlighted its dividend yield as materially higher than the industry average, supported by a 47% payout ratio and five straight years of dividend increases.
- The combination of an elevated yield, measured payout, and projections for earnings in the current fiscal year has sharpened attention on Peoples Bancorp's potential as a steady income vehicle rather than a pure growth story.
- We will now look at how Peoples Bancorp's richer dividend yield and disciplined payout policy could reshape its broader investment narrative.
Scan beyond Peoples Bancorp by reviewing a curated set of higher-yield, income-focused stocks in the Simply Wall St screener for 6 dividend fortresses.
Peoples Bancorp Investment Narrative Recap
For a shareholder in Peoples Bancorp, the core belief is that a community focused bank with a clear income tilt can keep generating solid earnings while returning a meaningful share of those profits to investors. The recent focus on its dividend fits that view. It highlights a 47% payout ratio that still leaves room to fund operations and technology investment.
The key near term swing factor is how net interest margin and credit costs evolve, especially as accretion income support fades and funding remains competitive. Credit issues in the small ticket leasing book and higher operating costs sit on the other side of the ledger as the biggest current risks.
Recent commentary around Peoples Bancorp has centered on its dividend profile. The company currently offers an income stream that is described as high and reliable at 4.22%. It is supported by earnings that have grown 13.2% per year over the past 5 years and an annual payout that has been raised for five consecutive years.
That mix matters for any thesis on potential catalysts. A disciplined payout policy, alongside what is described as high quality earnings and management efforts to reduce exposure to weaker leasing assets, gives the bank more room to absorb credit or funding pressure while still supporting shareholder returns. Execution on deposit growth, cost control and digital upgrades remains crucial.
Peoples Bancorp's analyst narrative points to forecast revenue of $632.5 million and projected earnings of $164.9 million by 2029, based on an assumed 14.3% yearly revenue growth rate and an earnings increase of about $54.4 million from $110.5 million today.
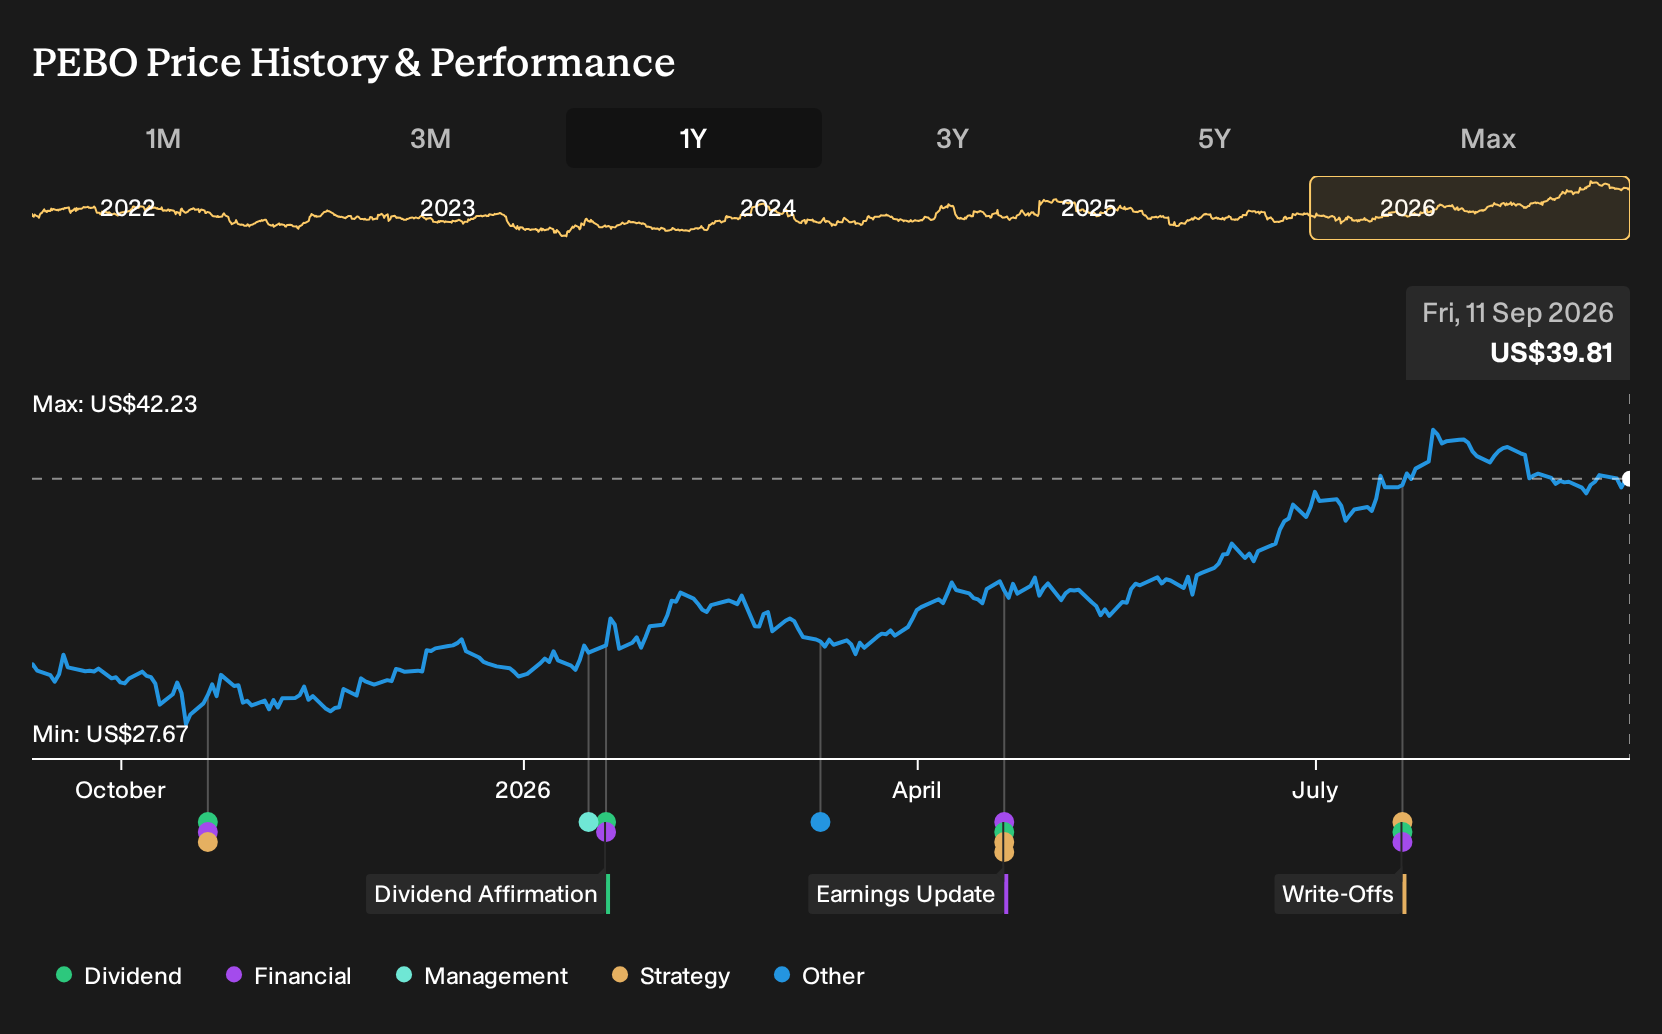
Uncover why Peoples Bancorp's fair value indicates a 4% potential upside to its current price. This move could close sooner than income investors expect.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span roughly US$41.50 to about US$69.46 per share, so retail opinions on Peoples Bancorp are far from aligned. When you factor in credit risk around small ticket leasing and funding pressure on margins, you get very different stories about future profitability. Explore those contrasting viewpoints before leaning on any single estimate.
Explore another Peoples Bancorp fair value estimate, including one that suggests as much as 74% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider performing your own analysis.
- A great starting point for your Peoples Bancorp research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Peoples Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, which makes it easy to evaluate Peoples Bancorp's overall financial health at a glance.
Looking For More Ideas Beyond Peoples Bancorp?
If you want to put Peoples Bancorp in context, it helps to line it up against other income and quality focused opportunities. The Simply Wall St screener can surface a wider mix of candidates that match different risk and return preferences, so you are not relying on a single bank to carry your income goals.
- For investors who care most about resilient balance sheets and solid fundamentals, review this curated list of solid balance sheet and fundamentals (23 results) that can help you prioritise financial strength alongside income potential.
- If your focus is on finding mispriced opportunities with room for a re rating, scan through a tailored list of 31 high quality undervalued stocks that combine quality metrics with more modest expectations baked into current prices.
- Those who want income at the centre of their approach can widen the search beyond Peoples Bancorp by reviewing a range of 6 dividend fortresses designed to spotlight higher yielding businesses with a focus on shareholder payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com