


- Teslar Software recently announced that TeslarSync is now available through the Fiserv AppMarket, giving banks and credit unions automated core write-back capabilities that cut duplicate data entry and keep records aligned across systems.
- By plugging TeslarSync into Fiserv’s distribution and core ecosystem, community institutions gain a practical route to workflow automation without replacing existing core platforms. This directly addresses adoption friction and integration costs.
- We will now look at how this new TeslarSync core automation link inside Fiserv AppMarket could influence the broader investment narrative.
Scan how Fiserv’s push into workflow automation compares with other financial institutions investing in core tech upgrades by reviewing the hand-picked list of solid balance sheet and fundamentals (23 results).
Fiserv Investment Narrative Recap
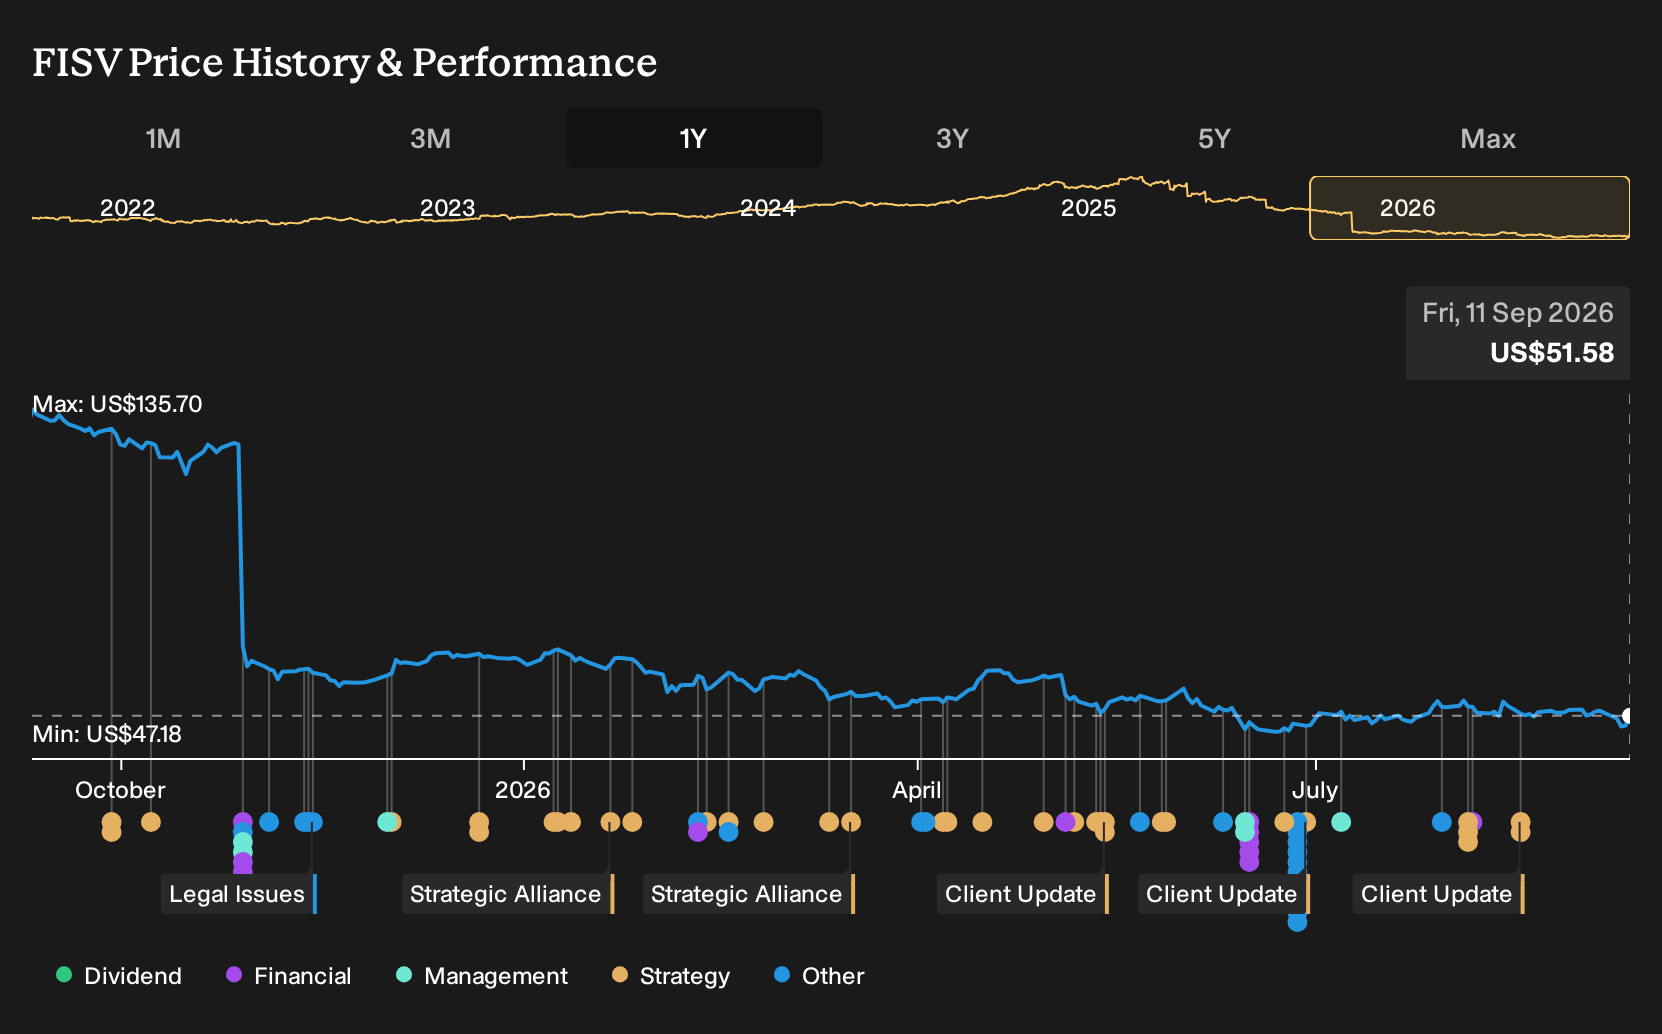
For Fiserv, the core belief you would need as a shareholder is that its payments and financial technology platforms can keep pulling in recurring, transaction driven revenue even as growth expectations are modest. The big swing factor in the near term is execution on new products and integrations. The TeslarSync news looks helpful for the story, but not a game changing catalyst on its own.
The main risk remains operational follow through. Management has already pushed organic growth expectations to the low end of guidance and is dealing with thinner margins and interest costs that are not comfortably covered. If new platforms or ecosystem additions like TeslarSync are slow to scale, those pressures could remain in focus for longer.
The TeslarSync availability inside Fiserv AppMarket connects directly to one of the clearest operational themes. Banks and credit unions want automation and cleaner integrations without ripping out legacy cores. This fits that brief and supports the push behind next generation platforms such as Finxact and CashFlow Central that rely on tight data flows.
There is still meaningful execution risk around how quickly clients adopt these newer tools and how much extra software and value added services revenue Fiserv can earn from them. If uptake is steady, more third party modules like TeslarSync could deepen AppMarket usage and help offset slower growth expectations elsewhere in the business.
Fiserv's narrative projects US$21.5b revenue and US$3.4b earnings by 2029. This assumes revenue stays broadly flat and an earnings increase of about US$0.6b from current earnings of US$2.8b.
Uncover why Fiserv's fair value indicates a 22% potential upside to its current price before that gap closes.
Exploring Other Perspectives
Some of the most optimistic analysts already saw Fiserv pushing toward US$21.7b in revenue and about US$4.0b in earnings by 2029, assuming faster margin expansion. You might now read the TeslarSync move and wonder if that thesis gains more support. Others remain far more cautious, so explore both camps before forming a view.
Explore 13 other Fiserv fair value estimates, including one that suggests potential upside of up to 133% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Fiserv research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Fiserv. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fiserv's overall financial health at a glance.
Looking For More Ideas Beyond Fiserv?
If the Fiserv story has you thinking more broadly about where to put fresh capital to work, it can help to scan a wider field of opportunities with different risk and income profiles.
- For investors who want income today rather than only potential price moves, take a look at 6 dividend fortresses that focus on higher yielding payouts.
- If capital preservation and steadier balance sheets are your priority, filter for companies on the 11 resilient stocks with low risk scores that score well on resilience and financial strength.
- For those hunting for quality that is not yet widely followed, the 16 high quality undiscovered gems can surface under-the-radar businesses with solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com