


Investor events put Protagonist Therapeutics in focus
Protagonist Therapeutics (PTGX) has lined up a busy September, with CEO Dinesh V. Patel scheduled to speak at Citigroup’s Biopharma Back to School Summit and Cantor Fitzgerald’s Global Healthcare Conference in New York.
These appearances follow a recent special investor call to discuss an update from management, putting fresh attention on how the biotech’s clinical pipeline and financial profile line up with the current valuation.
Protagonist Therapeutics has ridden a strong run over the past year, with the share price delivering a 69.97% year to date gain and a very large 1 year total shareholder return of 151.75%, even after a modest 2.52% share price pullback over the past month that tempers near term momentum against a backdrop of longer term gains that run into multi fold territory over three and five years.
Spot other biotech stories that could be setting up for similar conference fueled interest by scanning our curated list of 16 high quality undiscovered gems alongside Protagonist Therapeutics.Protagonist Therapeutics now trades below both intrinsic value estimates and average analyst targets after its sharp multiyear run. Is that discount a sign of excessive market caution, or a rational pause before the next data points land?
Price-to-earnings of 115.7x for Protagonist Therapeutics: Is it justified?
Valuation has flipped for Protagonist Therapeutics, with the SWS DCF model flagging a large discount to its fair value estimate while the P/E ratio sits at a very rich 115.7x compared with both peers and the wider biotech industry.
The P/E multiple tracks how much investors are currently willing to pay for each dollar of reported earnings. For a drug developer like Protagonist Therapeutics, a very high P/E often reflects expectations that current profit levels do not fully capture the potential from a clinical pipeline, licensing deals or future product launches that are not yet fully visible in the income statement.
At 115.7x, the stock trades at a much higher P/E than the US Biotechs industry average of 16.5x and also above the peer group average of 84.1x. Compared with an estimated fair P/E of 28.9x, that gap is even wider, which suggests the current market multiple is far above the level the fair ratio model indicates the valuation could move toward if expectations cooled or earnings caught up.
To understand how that fair ratio is calculated and what would need to change for the P/E to look more aligned with fundamentals, take a closer look at the Explore the SWS fair ratio for Protagonist Therapeutics.
Result: Preferred multiple of Price-to-Earnings of 115.7x (OVERVALUED)
Still, the story around Protagonist Therapeutics can change quickly if key trials underperform expectations or if revenue of $281.992m fails to support its 115.7x P/E.
Find out about the key risks to this Protagonist Therapeutics narrative.
Another view on Protagonist Therapeutics valuation
On earnings, Protagonist Therapeutics looks expensive at a 115.7x P/E, yet the SWS DCF model points the other way and values future cash flows at $393.79 per share versus a $148.18 price, which implies the stock trades at a large discount. Which signal do you treat as more important?
Look into how the SWS DCF model arrives at its fair value.
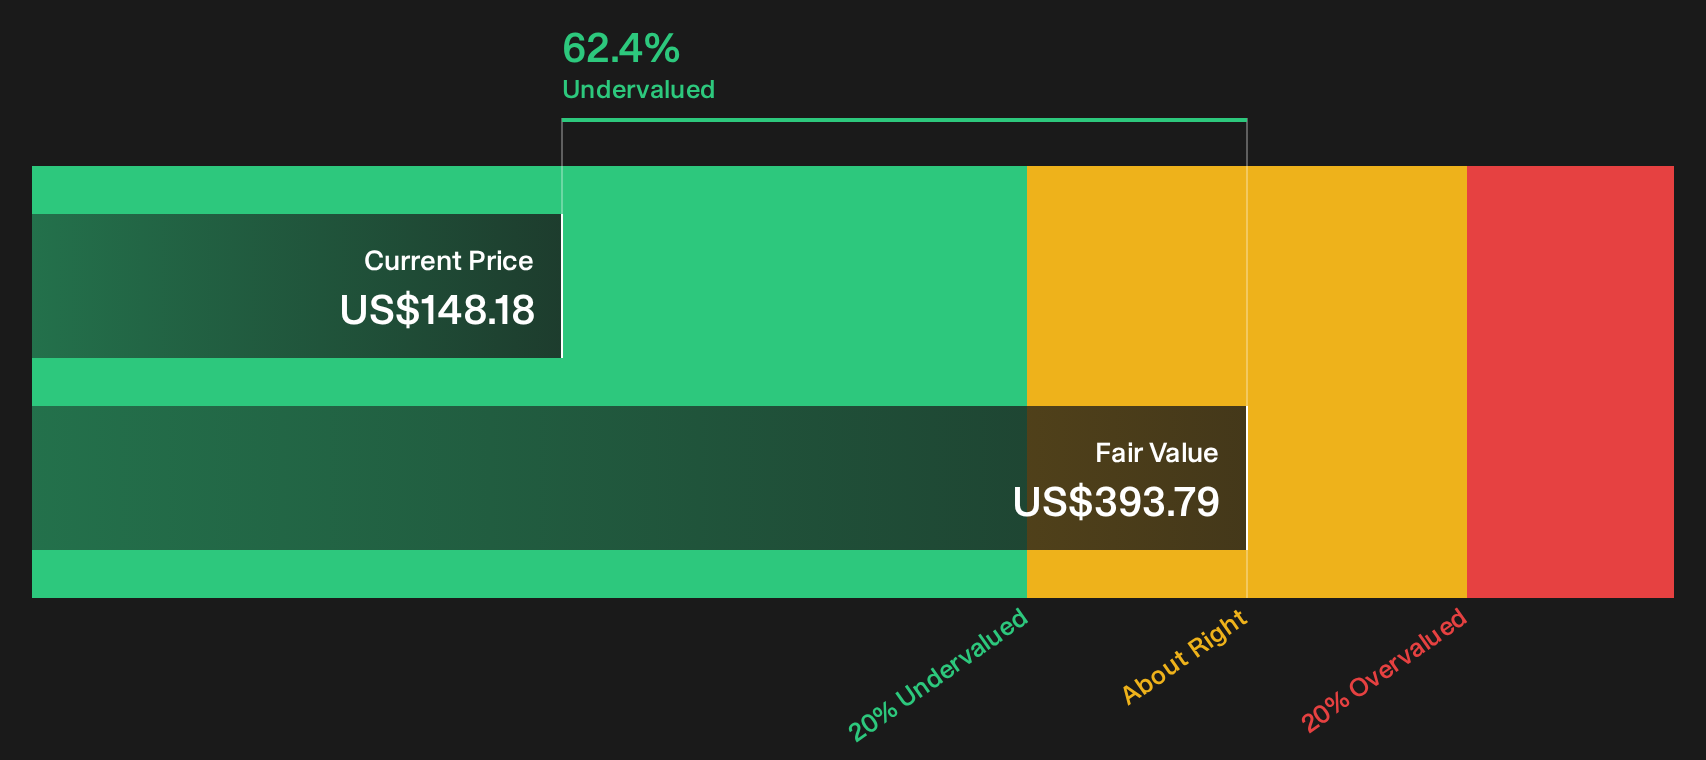
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Protagonist Therapeutics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty of data points around Protagonist Therapeutics send mixed messages, so move quickly and test the numbers yourself before sentiment shifts again. To see what optimism in the data looks like in detail, review the 3 key rewards.
Looking for more investment ideas beyond Protagonist Therapeutics?
Do not stop with Protagonist Therapeutics. Put fresh ideas on your radar by scanning focused stock sets that already filter for quality, valuation, and resilience.
- Target more resilient performers by reviewing a 11 resilient stocks with low risk scores that already screens for lower risk profiles and helps you focus your time where it counts.
- Zero in on value opportunities by working through a 31 high quality undervalued stocks that applies both quality and pricing filters before you even start your own deeper checks.
- Hunt for potential early stage winners by scanning a 21 elite penny stocks with strong financials that highlights smaller companies with stronger financials than the usual penny stock universe.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com