


Elevance Health has delivered a strong 1 year gain while the valuation checks still frame it as an undervalued stock rather than a fully priced one. For investors, that mix of solid recent returns and a high value score raises the question of whether the current share price still leaves meaningful upside on the table.
- The 37.0% 1 year return points to rising optimism. However, it also raises the bar for what counts as a good entry price from here.
- Management’s reaffirmed earnings and cost targets can support confidence in Elevance Health’s profit outlook. At the same time, execution risk around keeping benefit expenses in line with those targets may limit how far the valuation can stretch.
- A high value score, with Elevance Health screening as undervalued on most checks, suggests the broader toolkit still leans toward the stock looking cheap at current levels.
The issue now is whether Elevance Health’s recent share price strength has already absorbed most of that apparent discount or if the valuation still leaves room for further gains.
Spot opportunities with a similar mix of strong recent returns and high value scores by scanning the 31 high quality undervalued stocks alongside Elevance Health.Is Elevance Health Still Cheap on Earnings?
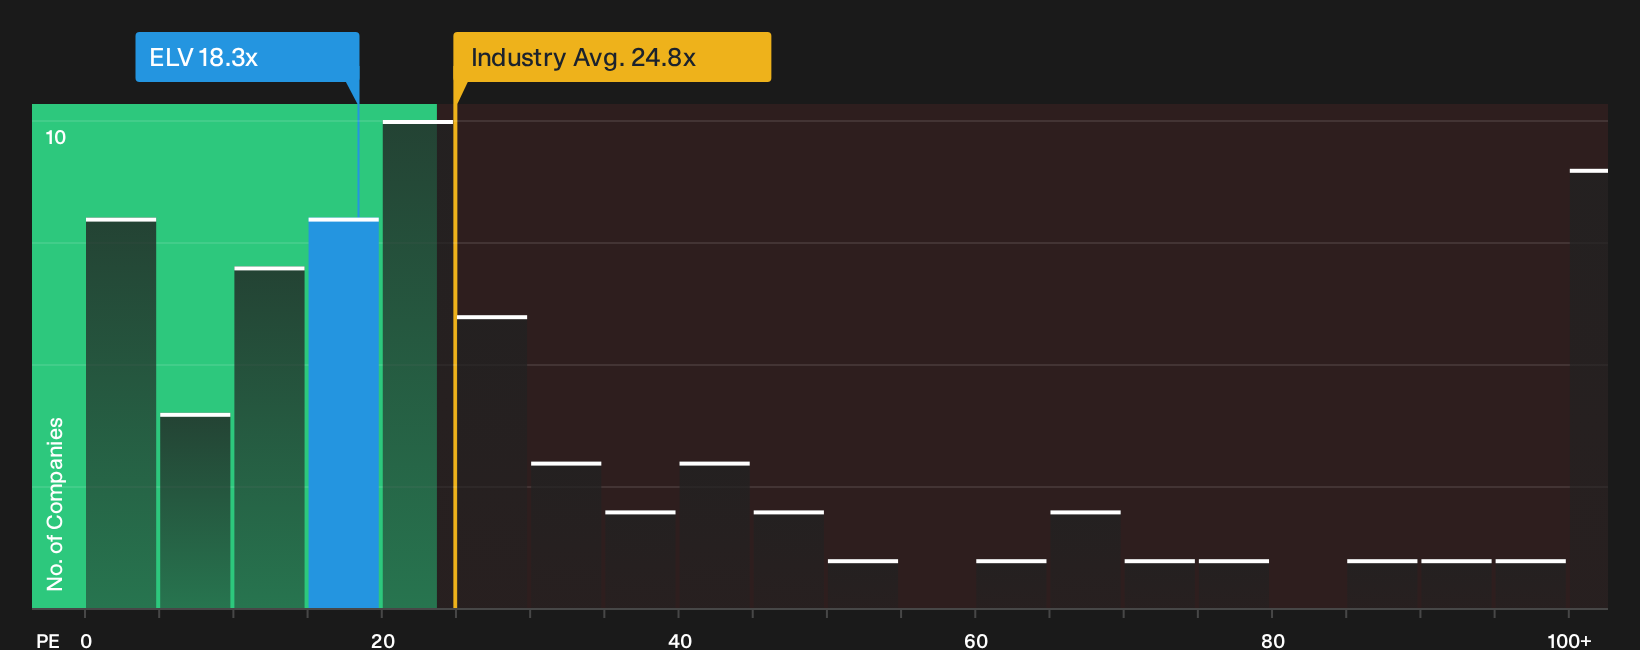
The P/E ratio works well for Elevance Health because the business already reports earnings and management provides explicit profit guidance. On this measure, the stock trades on roughly 18.3x earnings, which is well below the Healthcare sector average of about 24.8x and a peer group closer to 27.4x.
A more tailored fair P/E multiple for Elevance Health, which adjusts for its size, profitability profile and risk, comes out nearer 34.9x. That is a wide gap to the current 18.3x, which implies the market is assigning a sizeable discount to the company’s earnings stream even after recent share gains. Despite Elevance Health reaffirming its 2026 earnings and cost guidance, the current P/E still prices the stock well below the level implied by this framework.
On the P/E multiple alone, Elevance Health appears undervalued relative to both its sector and the earnings-based fair value estimate.
See what the numbers say about this price — find out in our valuation breakdown.
The Elevance Health Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Elevance Health pick up where the P/E puzzle leaves off. They spell out which paths for Elevance Health's revenue growth, margins and earnings would need to play out for the stock to be worth materially more or less than today's price. They also turn a single ratio or model result into a set of future checkpoints you can follow over time on the Community page.
The community is essentially split on Elevance Health, with one camp focused on disciplined Medicaid exits and tech driven efficiency and the other fixated on cost pressure and policy risk.
Bull case: 7% undervalued
"Demographic shifts, notably the aging U.S. population and increasing chronic disease prevalence, underpin long-term growth opportunities in Medicare Advantage and Medicaid..."
Read the full Bull Case to see why Elevance Health could be undervalued
Bear case: 7% overvalued
"Elevated costs in government-backed plans and greater reliance on value-based care could compress margins despite operational improvements and diversification strategies..."
Read the full Bear Case to see why Elevance Health could be overvalued
Do you think there's more to the story for Elevance Health? Head over to our Community to see what others are saying!
The Bottom Line
Elevance Health still screens as undervalued on earnings, with the current P/E sitting well below both sector peers and the tailored fair multiple. That gap only closes if investors become more comfortable paying up for the company’s profit stream. Everything now hinges on whether Elevance Health can keep benefit costs in check and hit the reaffirmed earnings and expense targets. If execution holds, the discount looks like a potential opportunity. If cost pressure is higher than expected, the lower multiple may reflect justified caution rather than mispricing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com