


Smurfit Westrock (NYSE:SW) has drawn fresh investor focus after joining Pratt Industries in petitioning U.S. trade authorities to investigate allegedly unfairly priced pizza box imports from China, Malaysia, and Turkey.
For context, Smurfit Westrock shares trade at US$43.22, with a 1 month share price return that is down 12.24% and a 7 day share price return that is down 5.70%. This is even though the year to date share price return is 9.14% and the 3 year total shareholder return is 33.33%, which points to longer term momentum but fading near term enthusiasm as investors weigh trade actions like the pizza box petition against broader fundamentals and valuation.
Scan beyond Smurfit Westrock and this trade case by comparing it with a curated list of solid balance sheet and fundamentals (23 results) that also rely on resilient packaging and materials demand.
Smurfit Westrock appears to be a large, globally diversified packaging business with solid recent earnings growth. However, the share price has slipped on the trade news. As you run the numbers next, is that dip offering fair value or is it a value trap?
Most Popular Narrative: 23.4% Undervalued
On the most followed narrative, Smurfit Westrock screens as undervalued, with a fair value of $56.43 compared with the current $43.22 share price.
Systematic winding down of loss-making contracts and refilling capacity with more profitable business in North America is expected to drive significant margin expansion and EBITDA growth as these actions move through the P&L over the coming year, benefiting both earnings and net margins.
Want to see what sits behind that margin story? The narrative leans on rising revenue, fatter profit margins, and a future earnings multiple that needs to compress sharply. It raises the question of which assumptions have to line up for that gap between price and fair value to close.
The same storyline also leans on a substantial increase in earnings and a higher profit share on every dollar of sales, all discounted back using an 8.09% rate. Analysts backing this view are effectively saying Smurfit Westrock needs to evolve into a very different earnings profile than today for the $56.43 figure to be justified. That is a useful reference point when weighing the short term trade noise around pizza box tariffs against a longer term equity case built on margins, synergies and capital discipline.
Result: Fair Value of $56.43 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Smurfit Westrock narrative leans heavily on successfully exiting loss-making contracts and avoiding prolonged industry overcapacity, both of which could easily stall the margin story.
Find out about the key risks to this Smurfit Westrock narrative.
Another View: Smurfit Westrock Through The P/E Lens
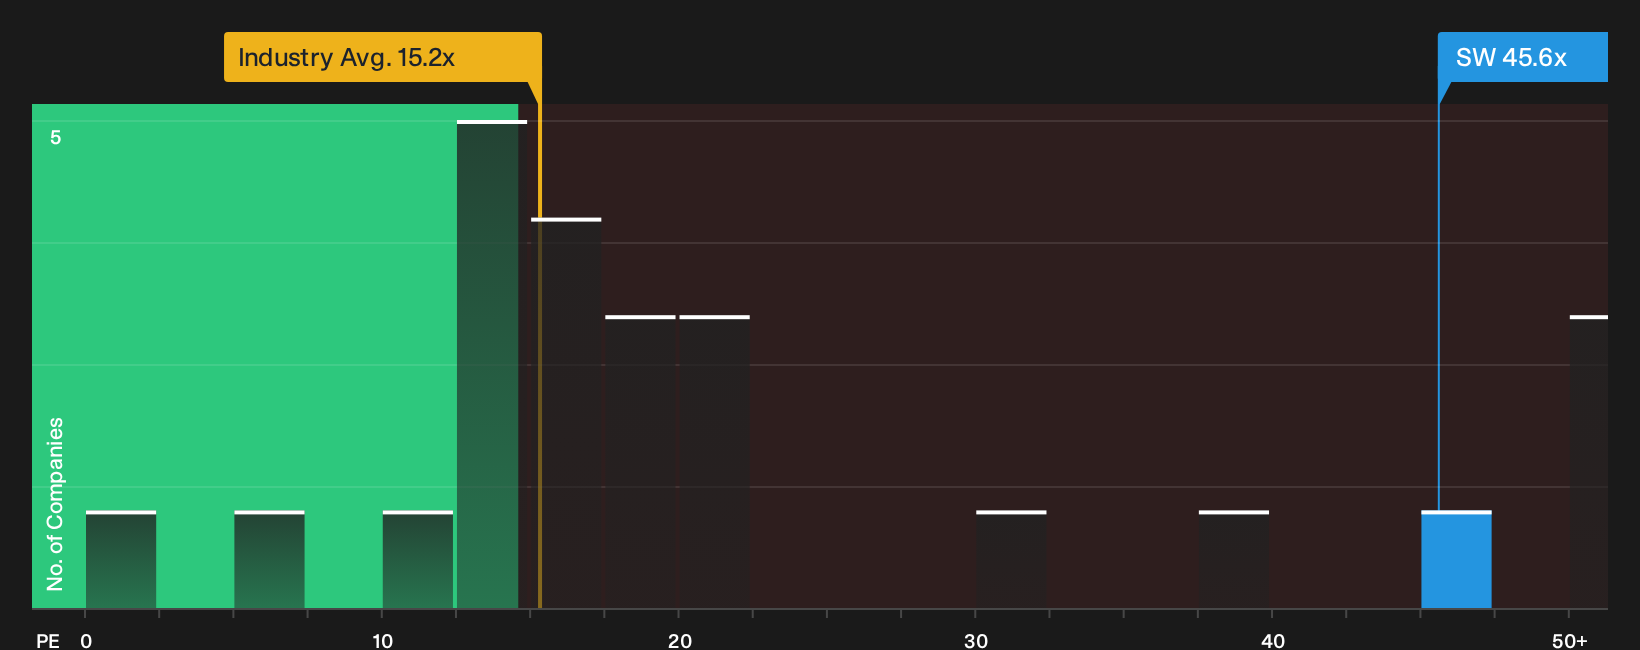
The discounted cash flow story around Smurfit Westrock paints a generous upside, yet the plain P/E yardstick tells something very different. The stock trades on about 45.6x earnings compared with a 15.2x Global Packaging average and an estimated fair ratio of 37.1x. That gap points to richer pricing and raises a simple question for you: Is this an early reward for future execution or a premium that leaves less room for error?
For a closer look at how that valuation gap ties back to earnings power and sector norms, it is worth studying a full breakdown before leaning on any single metric too heavily. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Smurfit Westrock after all that, or already leaning one way? Pull up the numbers yourself, test the assumptions that matter most to you, then weigh the 4 key rewards and 3 important warning signs
Looking for more Smurfit Westrock style investment ideas?
If Smurfit Westrock has sharpened your focus on valuation and quality, do not stop here. Push further and use data driven tools to broaden your watchlist.
- Target quality at a discount by scanning a 31 high quality undervalued stocks that filters for strong fundamentals without stretching on price.
- Strengthen your income stream by reviewing a 6 dividend fortresses that highlights companies combining higher yields with resilient payout histories.
- Protect your downside by assessing a 11 resilient stocks with low risk scores that spotlights businesses with sturdier balance sheets and calmer volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com