


Cardinal Health has delivered a very strong run over the past five years, yet current valuation tools point to a stock that now looks closer to fairly priced than obviously cheap. After such a move, the recent pullback and a mixed overall value score put more focus on how much upside is left in the current market multiple.
- Cardinal Health has returned about 3.98x over five years, which puts recent share performance at the upper end of the large healthcare distributors group and raises the bar for future returns.
- Pricing power and execution in its distribution and services operations can support earnings quality, while any pressure on margins or working capital needs may weigh on how much of that flows through to long term cash generation.
- The broader checks yield a mixed picture rather than a clear bargain or clear overvaluation, with the value score of 3 out of 6 suggesting Cardinal Health is roughly in line with where many investors might expect it to trade.
The issue now is whether Cardinal Health’s current share price already reflects the bulk of its recent gains or still leaves room for further upside without stretching valuation metrics.
Compare Cardinal Health’s sharp five year run with other distributors that still screen as potentially mispriced using the curated list of 31 high quality undervalued stocks.
Where Does Cardinal Health Sit on Earnings?
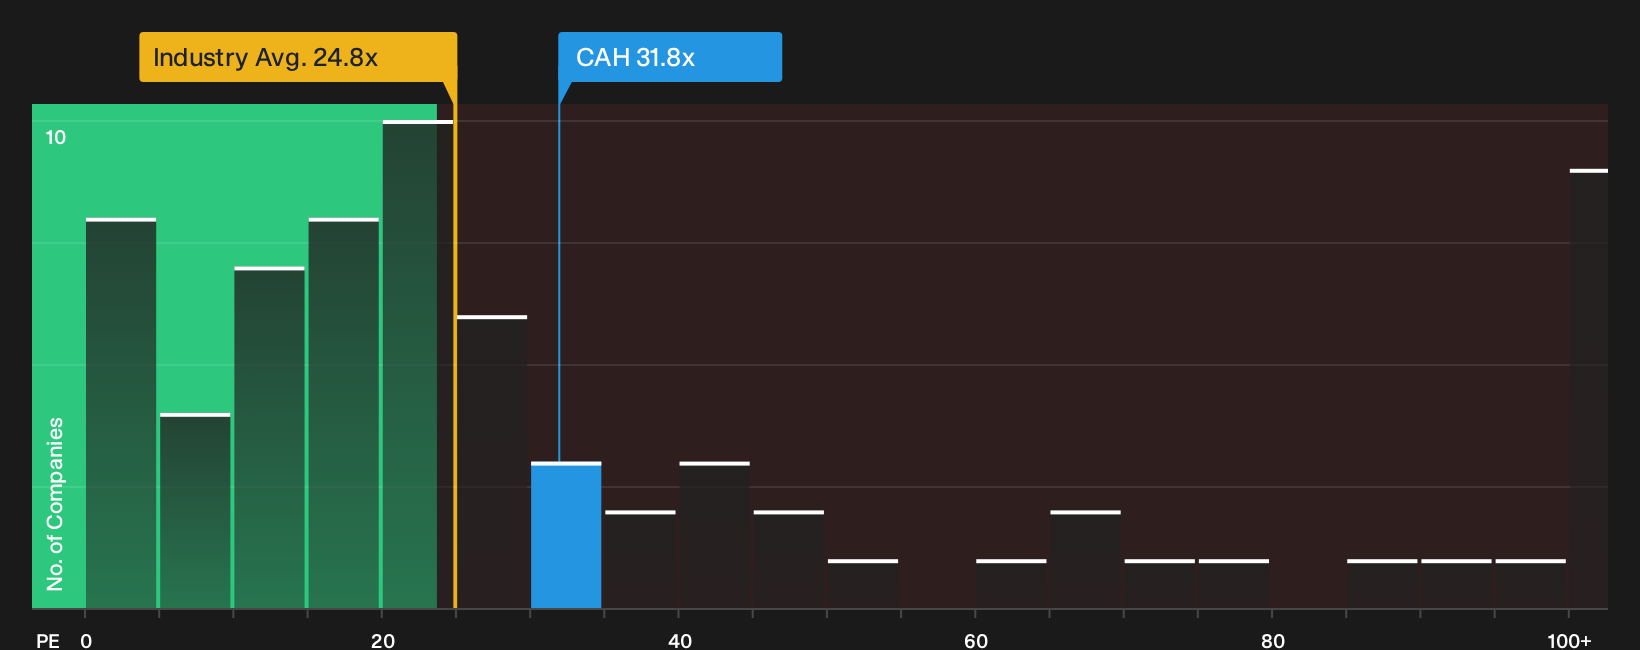
The P/E ratio suits Cardinal Health because earnings remain a central yardstick for how investors judge large healthcare distributors. On that measure, the stock trades on roughly 31.8x earnings, above the broader Healthcare sector average of about 24.8x and also above the peer group at around 27.2x. That puts a clear premium on the shares compared with many similar businesses, which matters after such a strong five year run.
The fair P/E that accounts for Cardinal Health’s scale, margins and risk profile sits at about 32.7x. The current 31.8x level is only slightly below that reference point, so the market is broadly aligning the price with what this model suggests is reasonable rather than stretching the multiple to an extreme.
On the P/E test, Cardinal Health appears roughly fairly valued, with the current multiple landing close to what the tailored fair ratio would imply.
See what the numbers say about this price — find out in our valuation breakdown.
The Cardinal Health Narrative: What Would Justify Today's Price?
Narratives for Cardinal Health pick up where the valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or materially less than today’s price on Simply Wall St’s Community page. Instead of stopping at a single ratio output, these scenarios unpack the future that number quietly relies on so you can watch over time whether that story is still holding together.
Add your own narrative on Cardinal Health's valuation and share your view on where its growth, margins and execution may go from here, so other investors can weigh that thesis against the numbers.
You can be one of the first voices in the Simply Wall St community to set out a grounded, data-driven case on Cardinal Health and then observe how it compares as new results are released.
Do you think there's more to the story for Cardinal Health? Head over to our Community to see what others are saying!
The Bottom Line
Cardinal Health now trades on a P/E that lines up closely with its tailored fair multiple, so the market is already assigning it a full, rather than discounted, valuation. The big question from here is not whether it is cheap, but whether its execution on margins and cash generation can keep justifying that premium. For investors, the real fork in the road is simple. Either earnings quality holds up and the current multiple proves sustainable, or any slip in profitability or working capital discipline turns today’s fair-looking price into a stretch.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com