


Sherwin-Williams stock has delivered a solid 26.9% gain over the past three years, yet current checks suggest investors are paying up, with the intrinsic value estimate pointing to roughly fair pricing while market multiples lean expensive.
- The 26.9% return over three years highlights that longer term holders have been rewarded, even though more recent performance has cooled.
- Expectations for ongoing demand in architectural and industrial coatings may support the valuation, while any slowdown in construction or renovation activity could pressure both earnings and the share price.
- The broader valuation checks indicate Sherwin-Williams is not a clear bargain, with only 2 of 6 tests lining up as cheap on this framework.
The key question now is whether Sherwin-Williams at around US$323 already reflects its intrinsic value, or whether the current premium on standard multiples leaves too little cushion for new buyers.
Spot 31 high quality undervalued stocks that, unlike Sherwin-Williams after its strong three-year run, still combine solid fundamentals with more room in the valuation cushion.Is Sherwin-Williams Fairly Priced on Cash Flow?
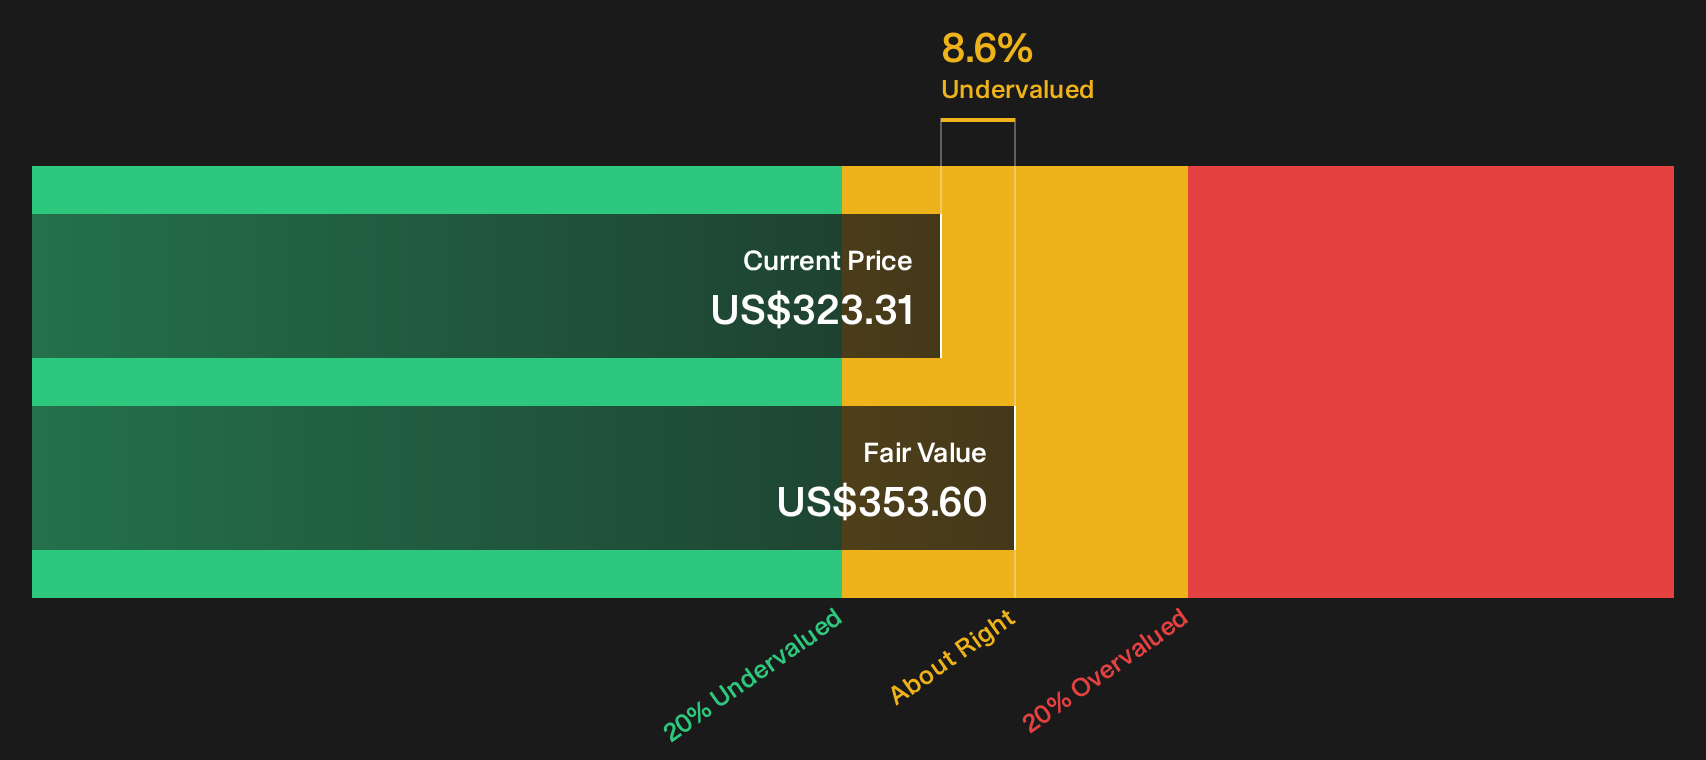
The Discounted Cash Flow (DCF) model here is built on what Sherwin-Williams can generate in free cash over time rather than on headline earnings. The company produced about $3.0b of free cash flow over the last twelve months, and the model assumes those cash flows keep growing rather than shrinking. On that basis, the 2 Stage Free Cash Flow to Equity framework points to an intrinsic value of about $354 per share.
With the stock trading near $323, the DCF implies roughly an 8.6% discount, so Sherwin-Williams comes out as slightly cheap rather than obviously mispriced. Recent Q2 results, including revenue of $6.79b and guidance that topped analyst expectations, help explain why the market is still willing to pay a relatively full price even if the model only shows a modest gap to fair value.
On this cash flow view, Sherwin-Williams appears to be close to fairly valued, with only a small margin between the DCF estimate and the current share price.
Sherwin-Williams is fairly valued according to our Discounted Cash Flow (DCF), but this can change at a moment's notice. Track the value in your watchlist or portfolio and be alerted on when to act.
Does Sherwin-Williams Look Pricey on Earnings?
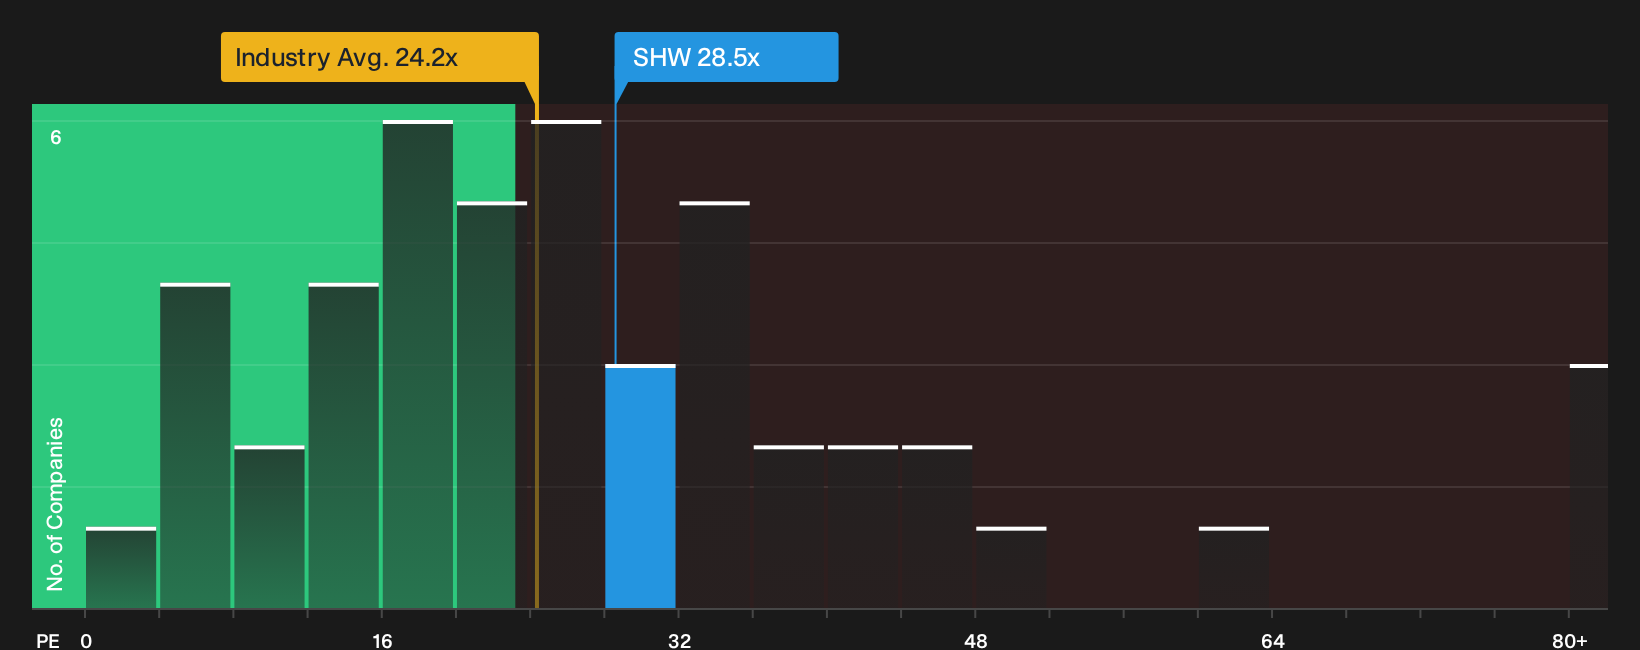
The P/E ratio works well for Sherwin-Williams because earnings are a key lens for a mature coatings business with a long operating history. On this yardstick, the shares trade on about 29.0x earnings, which is higher than the broader chemicals sector on roughly 24.0x and also above peers at around 21.3x.
A more tailored yardstick that blends Sherwin-Williams' growth profile, profitability, size and risk points to a fair P/E closer to 22.6x. That indicates the current multiple carries a sizeable premium to what this framework suggests as reasonable, even before factoring in any future surprises, which leaves the stock looking expensive on earnings compared with both industry norms and this fair value benchmark.
On the P/E multiple, Sherwin-Williams currently appears expensive relative to both its industry and a more customised fair-value yardstick.
See what the numbers say about this price — find out in our valuation breakdown.
The Sherwin-Williams Narrative: What Would Justify Today's Price?
Sherwin-Williams' valuation puzzle only really makes sense once you make the underlying story explicit. Narratives on Simply Wall St's Community page spell out the mix of growth, profitability and earnings assumptions that would need to hold for the stock to be worth meaningfully more or less than it is today. Each one treats fair value as a thesis about how Sherwin-Williams' business develops over time, so you can see how that view holds up as fresh information arrives.
One of the top community narratives on Sherwin-Williams: 7% undervalued
"Rising tariffs and flat raw material costs threaten gross margins, potentially compressing earnings without compensatory revenue growth."
Read one of the top narratives on Sherwin-Williams
Do you think there's more to the story for Sherwin-Williams? Head over to our Community to see what others are saying!
The Bottom Line
Sherwin-Williams screens close to fairly valued on the Discounted Cash Flow (DCF) estimate, with only a modest implied discount to intrinsic value, while the market-multiple view flags the stock as overvalued on earnings against both peers and a tailored fair P/E. That split comes down to which lens you trust more: the cash generation profile over time, or the richer multiple investors are currently willing to pay for the earnings stream. Broader valuation checks lean weak despite the DCF support, so the debate now hinges on one core question: Can Sherwin-Williams sustain the kind of earnings power that keeps its premium P/E ratio intact?
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com