


- Sanmina (NasdaqGS: SANM) and subsidiary SCI Technology have settled a whistleblower lawsuit alleging misrepresented costs on U.S. government contracts.
- The case involved former employees who claimed the businesses presented inaccurate cost information tied to certain federal contract work.
- As part of the resolution, payments are expected to go to the U.S. government and to at least one former staff member.
- The settlement of the whistleblower cost misrepresentation case is only one piece of the wider Sanmina story. Our analysis turns up 2 other big wins for Sanmina as well.
Consider widening your watchlist to include other contract manufacturers and electronics players that also interact with government and enterprise buyers through 74 profitable AI stocks that aren't just burning cash.
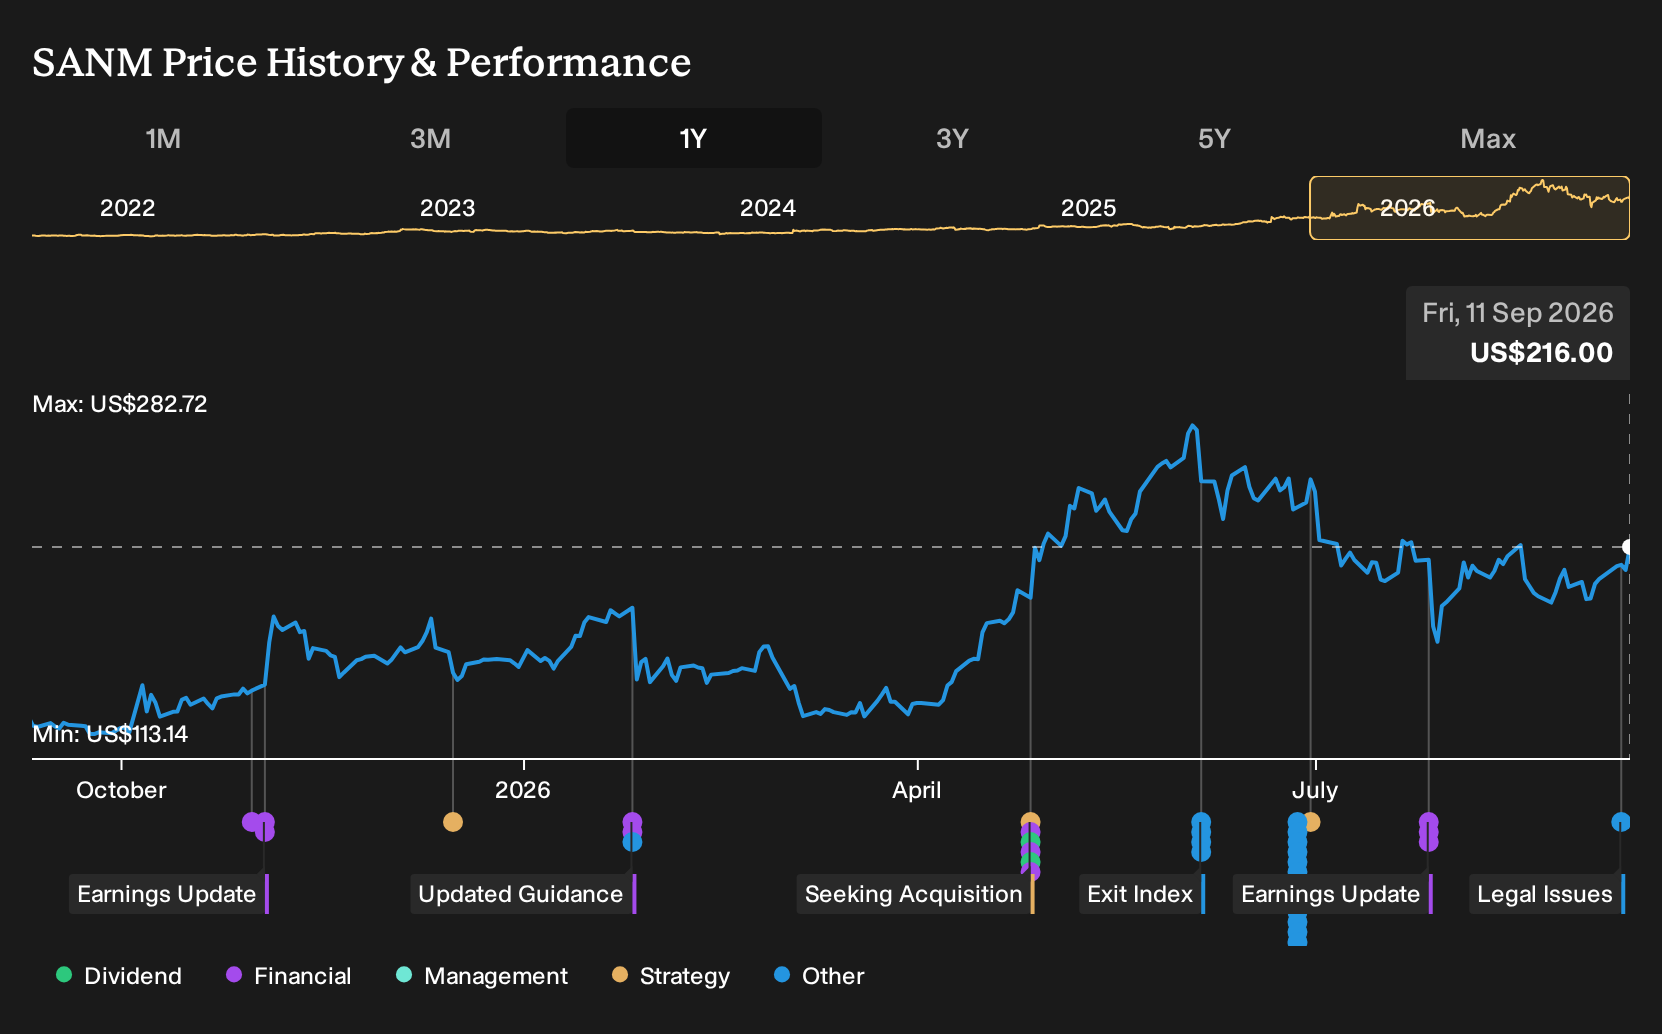
Sanmina operates as an electronics manufacturing services provider, handling design, production, and after-market support for customers across the Americas, Asia Pacific, Europe, the Middle East, and Africa. This focus places government and enterprise contract work at the center of how its business runs day to day.
See how Sanmina's balance sheet measures up.
Sanmina’s cost-accounting scrutiny goes straight to its margin story
The investment story around Sanmina leans heavily on the idea that a high mix of complex, government-linked manufacturing can support steadier profitability as the firm scales. A settled whistleblower case around cost accounting and labor practices cuts right into how reliable that profit narrative looks.
"Customer concentration, supply chain risks, and execution challenges from acquisitions and expansion threaten future growth, margins, and revenue stability amid shifting industry and geopolitical pressures..."
See how the full story points towards a $260 fair value for Sanmina.
The legal settlement directly touches the catalyst that hinges on higher-margin defense and aerospace work supporting long-term earnings, because it focuses on how SCI and Sanmina accounted for costs on U.S. contracts. This event adds to the existing execution risk bucket, alongside integration of ZT Systems and regional expansion, and may lead some investors to scrutinize contract quality more than headline volume.
On the other hand, resolving a long-running whistleblower case without an admission of wrongdoing removes one source of uncertainty that could have distracted management from automation efforts and AI related build outs, especially versus peers like Celestica or Jabil. Analysts have already flagged that large one off items can affect reported results, so any government-related repayments and fees now sit squarely in that category rather than as an open ended overhang.
For an investor, it is the coherence of Sanmina’s narrative that turns a dense legal settlement into something that can be weighed against growth, margin and risk targets.
One more Sanmina question that matters for long term investors
There is a separate piece of the Sanmina puzzle that comes from the pattern of cash moving through the business, which can be used to estimate what the shares might reasonably be worth next to today’s price. Find out exactly what Sanmina is worth today based on its cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com