


Hercules Capital enters this valuation check with a strong 5 year share return set against market pricing that several models still flag as cheap, creating a clear question about how much upside is already reflected in the US$17.41 stock price.
- The Hercules Capital share price has delivered roughly 82.7% over 5 years, which puts long term holders in a solid position before considering what today’s valuation implies from here.
- Fresh capital raising progress at Hercules Adviser, including more than US$2.3b of investable capital, can support future deployment, while any shift in credit quality or loss experience may weigh on how investors price that lending book.
- On Simply Wall St’s checks, Hercules Capital screens as broadly cheap, with a high value score of 5 out of 6 and both intrinsic value and multiples pointing to the stock trading at a discount.
The issue now is whether that apparent discount in Hercules Capital is wide enough to compensate you for the risks in a specialist lender and justify fresh capital at today’s level.
Compare Hercules Capital’s valuation story with other potential opportunities by running the same checks across 31 high quality undervalued stocks that already score well on both pricing and fundamentals.
Is Hercules Capital Still Cheap on Excess Returns?
The Excess Returns model for Hercules Capital estimates what shareholders earn above the cost of equity and capitalises that stream into a per share value. For this lender, the inputs are grounded in recent history rather than aggressive projections. Book Value is set at $12.32 per share, with Stable Book Value at $11.79 per share based on the median level over the past 5 years. Stable EPS of $1.84 per share comes from the median Return on Equity, which averages 15.60%.
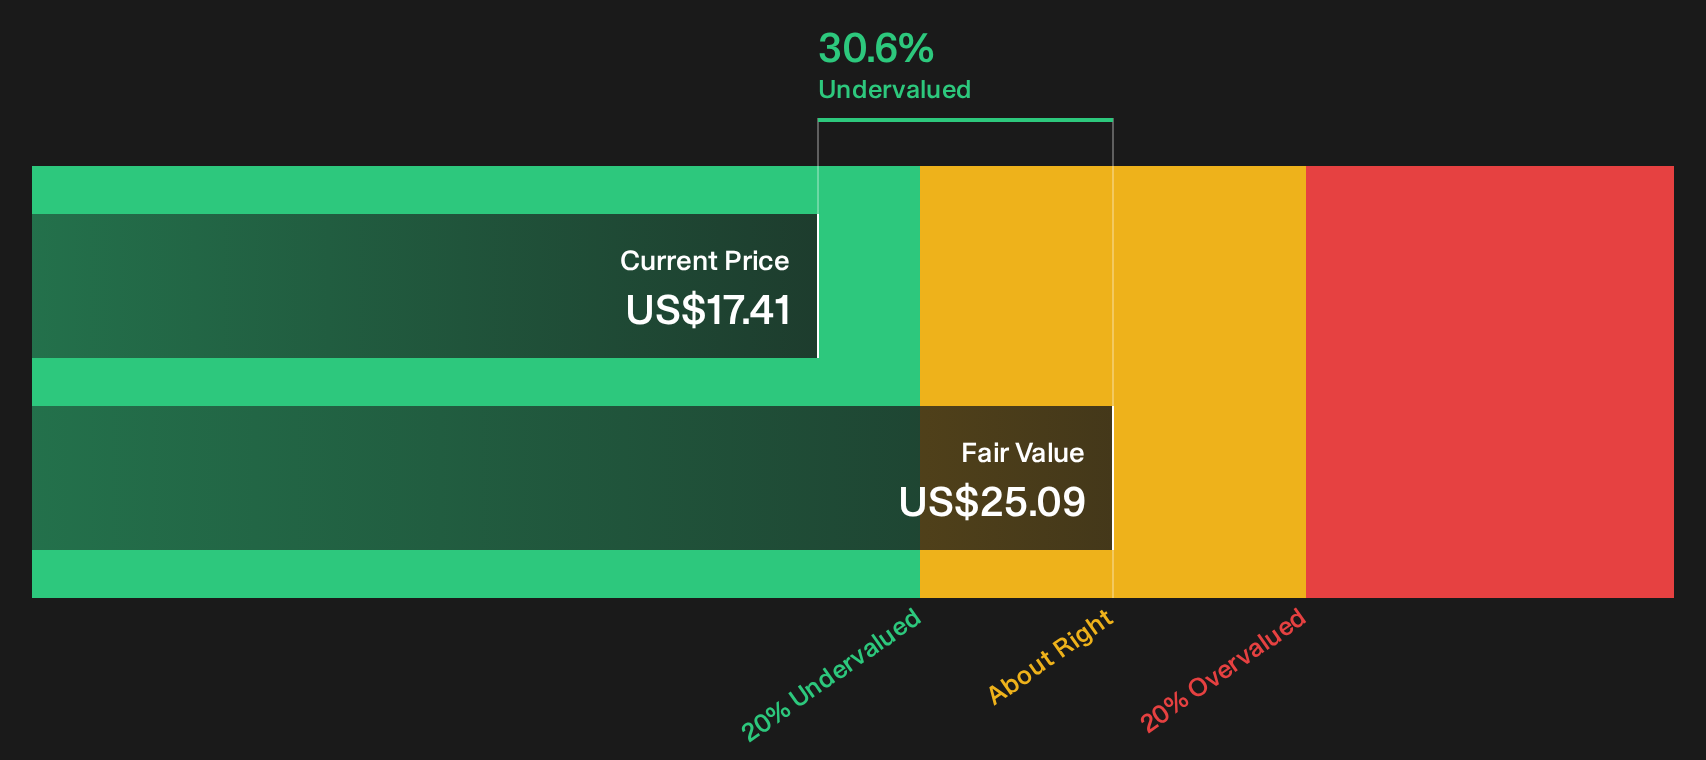
Against a Cost of Equity of $1.10 per share, the model calculates an Excess Return of $0.74 per share and arrives at an intrinsic value of about $25.09 per share. Set beside the current price around $17.41, the Excess Returns framework implies Hercules Capital trades at roughly a 30.6% discount, which indicates undervaluation on this method. Because Hercules Adviser recently surpassed US$2.3b in investable capital, some investors may interpret the current gap between intrinsic value and market price as a reflection of how cautiously the market is treating that growth runway.
On these Excess Returns assumptions, Hercules Capital appears undervalued relative to the current share price.
Our Excess Returns analysis suggests Hercules Capital is undervalued by 30.6%. Track this in your watchlist or portfolio, or discover 31 more high quality undervalued stocks.
Does Hercules Capital Look Undervalued on Earnings?
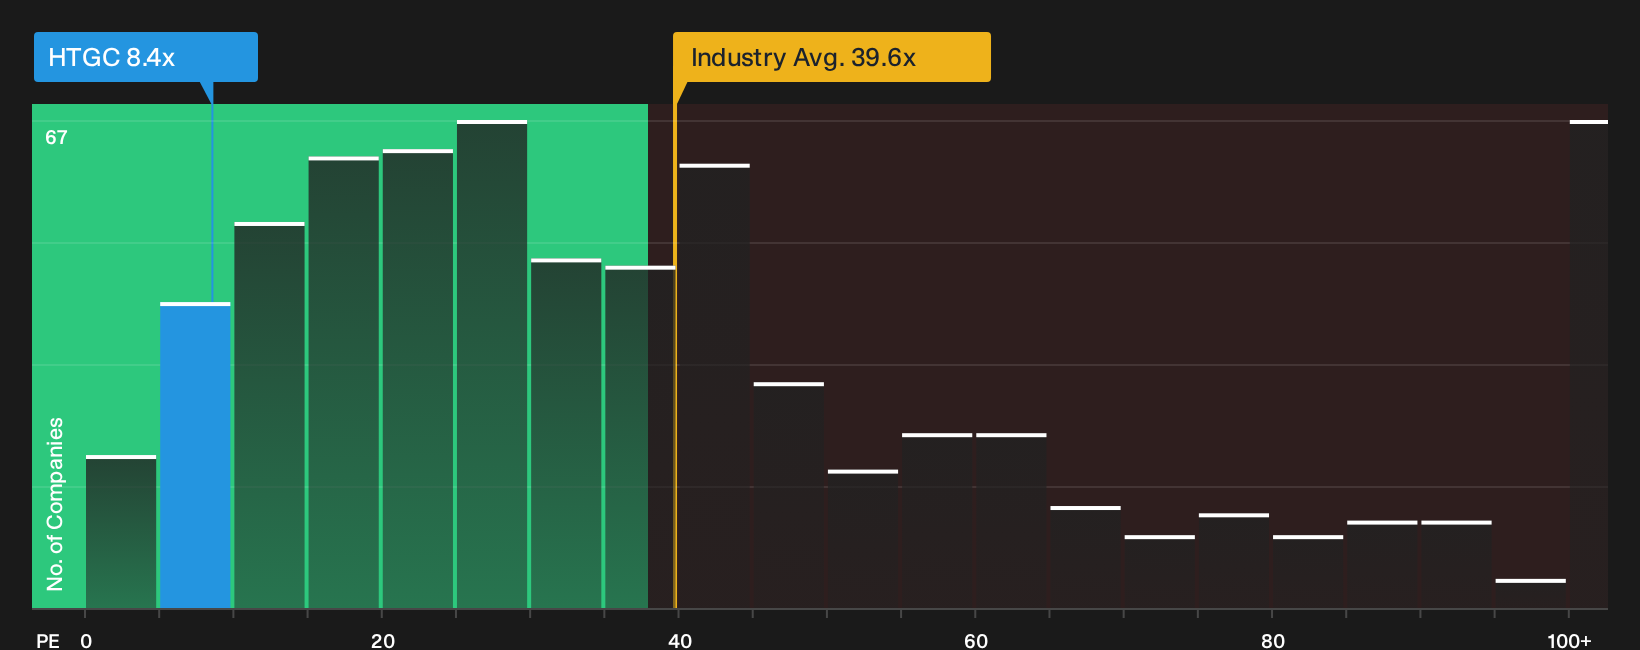
P/E fits Hercules Capital well because earnings remain a primary yardstick for lenders and business development companies. On this measure, the stock trades on a P/E of about 8.4x, compared with a Capital Markets industry average near 39.6x and a peer group around 16.2x. That is a steep step down from both the sector and more immediate competitors.
The Fair P/E Ratio model points to a figure closer to 10.2x for Hercules Capital, based on its recent profitability, risk profile and sector. Set against the current 8.4x multiple, that gap suggests investors are asking for a wider margin of safety than the fundamentals alone would imply. For readers weighing valuation, the shares screen as inexpensive on earnings even before you factor in how rich broader industry P/E levels appear.
On the P/E yardstick, Hercules Capital stock currently appears undervalued relative to what the tailored fair multiple would suggest.
See what the numbers say about this price — find out in our valuation breakdown.
The Hercules Capital Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Hercules Capital's valuation puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to play out for the share price to sit meaningfully above or below where it trades today. Rather than stopping at a single ratio or model output, they map the specific business outcomes that number relies on so you can watch how Hercules Capital's actual results line up over time on the Community page.
Community views on Hercules Capital pull in opposite directions, with one side focused on growth firepower and the other on yield pressure and risk.
Bull case: 10% undervalued
"Sustained expansion in the technology and life sciences sectors continues to drive record growth in new loan originations and fundings for Hercules, supporting robust revenue and net investment income growth into 2026…"
Read the full Bull Case to see why Hercules Capital could be undervalued
Bear case: roughly fairly valued
"Hercules Capital may face pressure on future core yields, which have already declined from 12.9% in Q4 to 12.6% in Q1, due to declining base rates and spread compression, potentially impacting revenue growth and net income…"
Read the full Bear Case to see why Hercules Capital could be overvalued
Do you think there's more to the story for Hercules Capital? Head over to our Community to see what others are saying!
The Bottom Line
Hercules Capital screens as undervalued on both the Excess Returns intrinsic value estimate and the earnings multiple, which is a rare alignment for a specialist lender. The broad valuation work points to a meaningful discount, so the real question is whether that gap reflects mispricing or a sensible buffer against credit and yield risk in the loan book. Everything now hinges on how core yields, loss experience and deployment of that investable capital evolve, because those factors will decide whether the current markdown becomes a re rating or proves to be a value trap.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com