


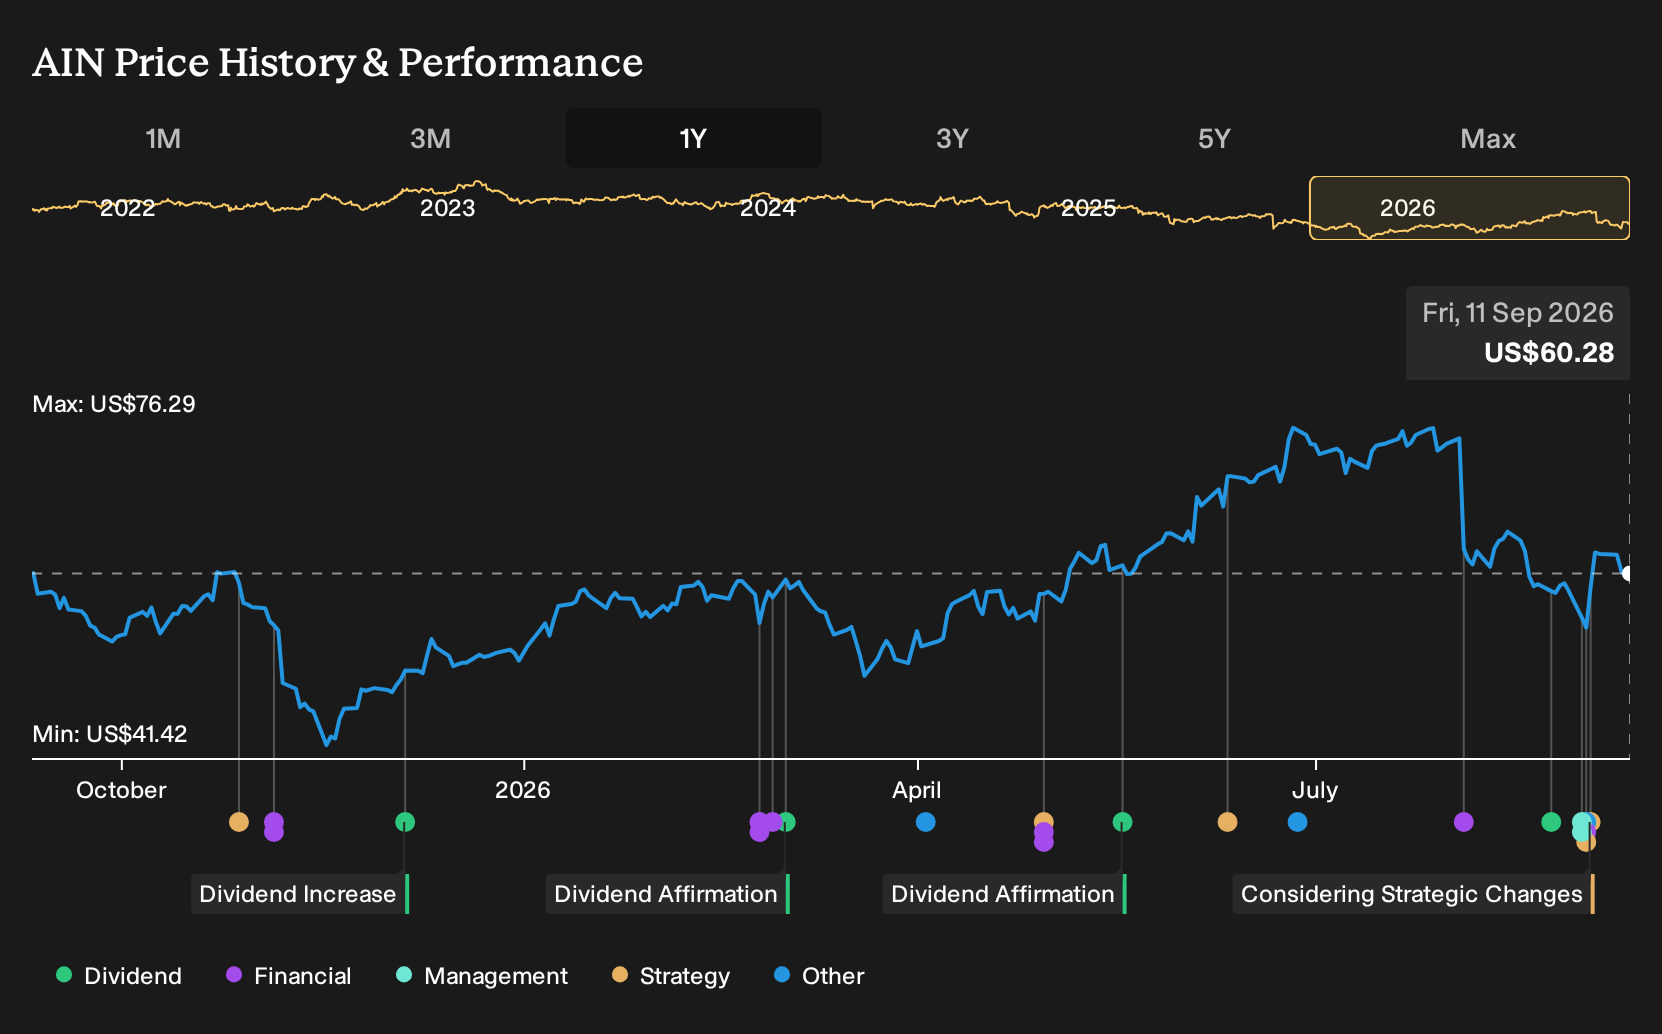
- Albany International completed its review of the Amelia Earhart Drive facility in Salt Lake City, choosing to keep the site after securing new work and amended contracts with Sikorsky on CH-53K and Boeing on the 787 program, alongside issuing fourth quarter 2026 revenue guidance of US$325 million to US$335 million.
- The decision to retain a well capitalized aerospace composites facility, backed by revised contract terms that target reduced program risk and positive cash flow, signals a focus on operational continuity and long term program execution rather than footprint reduction.
- We will now look at how Albany International's renewed CH-53K contract could shape the broader investment narrative for the business.
Albany International Investment Narrative Recap
For Albany International, the core belief is that aerospace composites and more resilient packaging-related machine clothing can offset weak legacy paper exposure and current losses. The Salt Lake City decision supports that view. Keeping a fully equipped composites plant, with amended CH 53K and 787 terms and Q4 2026 revenue guidance of US$325 million to US$335 million, points to a focus on execution rather than retrenchment.
The most important short-term catalyst remains cleaner execution and cash generation in Albany Engineered Composites. The biggest risk is still program concentration and operational missteps that could keep the group unprofitable and leave dividends uncovered. On balance, this news looks operationally helpful but not transformational.
The renewed CH 53K arrangement with Sikorsky is the announcement that matters most here. Management describes reduced program risk, positive cash flow and stabilized helicopter production from the amended contract. That directly addresses earlier concerns around heavy investment, EAC adjustments and weaker than expected profitability in Engineered Composites.
For you as a shareholder or potential shareholder, this contract framework sits beside guidance and existing growth programs as a key test of Albany International’s ability to translate a concentrated program mix into sustainable earnings. Execution at the Amelia Earhart Drive facility now becomes a practical marker for how effectively the business can manage capital-heavy aerospace work while carrying meaningful debt and an uncovered dividend.
Albany International's current earnings are a loss of US$51.2 million, while analysts expect earnings of US$410.9 million by 2029. This implies an earnings increase of about US$462 million. Based on those same forecasts, analysts project that revenues will reach US$1.5b in 2029, assuming yearly top line growth of 6.9%.
Uncover why Albany International's fair value indicates that earnings are roughly in line with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Albany International’s potential earnings ramp rather than program concentration risk. Before this Salt Lake City news, the bullish group was already modeling about US$1.5b of revenue and US$306.0 million of earnings by 2029. You can treat this as one possible path and compare it with more cautious views.
Explore another Albany International fair value estimate, including one that suggests it could be worth as much as $60.25.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Albany International research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Albany International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Albany International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Albany International?
Once you have a view on Albany International, it can help to widen the lens and compare it with other businesses that match the kind of balance sheet strength, income potential or value profile you want in your portfolio.
- If you want a shortlist of companies that combine quality fundamentals with what analysts rate as attractive pricing, start with the 31 high quality undervalued stocks.
- For investors who care about income as much as price appreciation, filter for companies with stronger yields and more resilient payouts using the 6 dividend fortresses.
- To help keep risk in check while you search for ideas, focus on resilient businesses with sturdier finances through the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com