


Applied Materials stock has delivered very strong gains over the last three years, yet the current valuation picture sends mixed signals. Investors see a powerful multiyear return profile set against a broader checkup that does not clearly label the shares as either cheap or stretched. For anyone looking at Applied Materials today, the key question is whether the recent pullback meaningfully improves the entry point or simply trims some heat off a still fully valued story.
- Over the last 3 years, Applied Materials has returned about 238.0%, which puts recent share weakness into the context of a very strong multiyear run.
- Heavy customer interest tied to AI related chip production and process control tools can support earnings expectations, while any slowdown in wafer equipment demand or AI infrastructure spending may influence how much investors are willing to pay for those cash flows.
- The overall valuation score is mixed, with the company screening as undervalued on some multiple based checks but not presenting as an obvious bargain on the broader set of tests, according to 3 of 6 indicators.
The issue now is whether Applied Materials at today’s level fairly reflects its recent AI driven momentum or still leaves room for further upside without stretching valuation too far.
Spot AI-driven demand across the sector by scanning our hand picked 89 AI infrastructure stocks while you assess how Applied Materials fits into the broader build out.Is Applied Materials Still Cheap on Earnings?
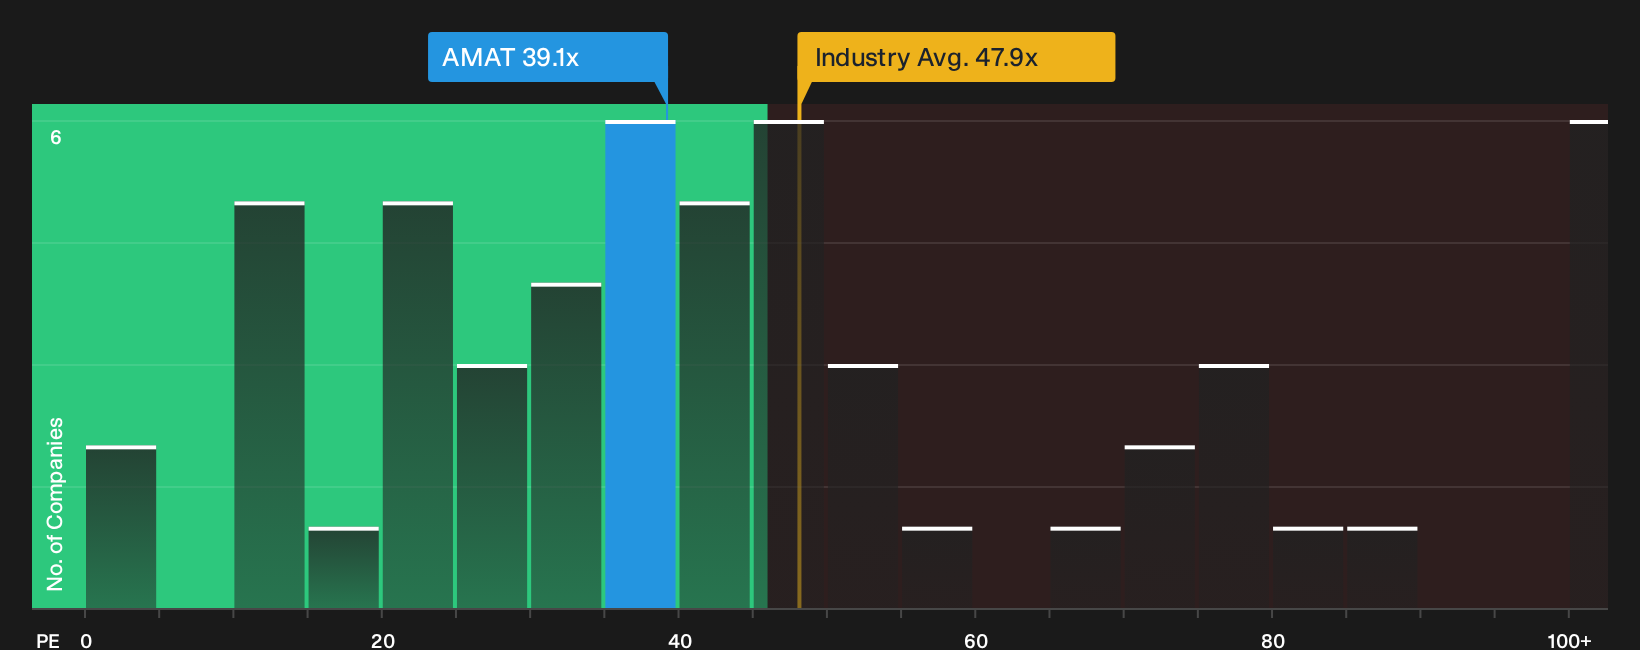
P/E fits Applied Materials well because earnings remain the main yardstick many investors use for large, established chip equipment suppliers. The stock trades on roughly 39.1x earnings, which sits below both the semiconductor sector average of about 47.9x and the peer group on roughly 43.0x. That already points to a discount for Applied Materials when set against similar businesses.
The internal “fair” P/E multiple for the company sits higher again, at about 43.6x, which leaves a clear gap between where the market prices the shares and where this framework would expect them to trade. Despite upbeat commentary around AI related demand for wafer equipment and process control tools, the P/E still lines up below those tailored benchmarks. Taken together, the numbers indicate that investors today are not paying a premium multiple for Applied Materials relative to its sector and peer set.
On the P/E yardstick, Applied Materials appears undervalued compared with both its tailored fair multiple and the wider semiconductor group.
See what the numbers say about this price — find out in our valuation breakdown.
The Applied Materials Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Applied Materials valuation puzzle leaves off by spelling out which earnings, margin and growth paths would need to play out for the stock to look meaningfully mispriced in either direction at today’s level. Each narrative links its figure to a specific view on how Applied Materials' growth, profitability and risk profile could evolve, giving you a concrete reference that can be checked against future results and new information.
Community views on Applied Materials could hardly be further apart, with one camp leaning into an AI equipment supercycle and the other focusing on trade rules and a cooler spending path.
Bull case: 27% undervalued
"Advanced packaging remains Applied's area of highest market share, bolstered by strong customer collaboration and a growing pipeline of new hybrid bonding and integration technologies…"
Read the full Bull Case to see why Applied Materials could be undervalued
Bear case: 5% overvalued
"The company faces trade restrictions impacting its ability to serve the China market, potentially hurting future revenue and service growth, as approximately $400 million of revenue is expected to be impacted in fiscal 2025…"
Read the full Bear Case to see why Applied Materials could be overvalued
Do you think there's more to the story for Applied Materials? Head over to our Community to see what others are saying!
The Bottom Line
Applied Materials screens as undervalued on key P/E checks, yet the broader mix of signals is more balanced than outright cheap. That leaves the current price hinging on whether AI linked equipment demand and margins can support the kind of earnings profile that justifies even a modest re rating. The core debate is simple but important. Either the lower multiple reflects an opportunity if AI related orders stay resilient, or it shows the market already baking in trade and spending risks that cap how far the valuation can stretch from here.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com