


Brinker International (EAT) moved into focus after reporting fourth quarter fiscal 2026 earnings that matched expectations, with revenue ahead of forecasts. Chili's drove results, while Maggiano's contended with softer traffic and restaurant closures.
Brinker International’s share price has pulled back recently, with a 7-day share price return down 7.7% and a 30-day return down 13.6%. However, the 90-day share price return of 33.4%, year-to-date gain of 40.2%, and a three-year total shareholder return above 7x still point to strong momentum overall.
Spot other restaurant chains showing strong multi-year momentum by scanning the hand-picked 16 high quality undiscovered gems that share some of Brinker International's resilience and earnings traction.Brinker International now trades well below analyst targets after a sharp pullback. Is that a simple reset after a significant three-year run, or a warning that the market is questioning the earnings story?
Most Popular Narrative: 19.4% Undervalued
Against the last close of $212.49, the most followed narrative pegs Brinker International’s fair value meaningfully higher, framing the recent pullback as a valuation gap rather than a complete reset in expectations.
Brinker's investments in menu innovation (e.g., upgraded ribs, new chicken sandwiches, beverage innovation) and a sharper focus on core items with broader appeal to younger demographics position it to capture incremental traffic from shifting population and generational consumption patterns, supporting future revenue growth.
This raises the question of what kind of revenue build, margin profile and future P/E multiple are required to justify that higher fair value on Brinker International. The underlying narrative leans on a detailed earnings bridge out to 2029, plus a specific discount rate that can materially shift that valuation if any of the inputs move.
On Simply Wall St, that narrative applies an 8.85% discount rate and a fair value estimate of $263.75, implying Brinker International trades at a sizeable implied discount to its own modeled future cash generation and profit potential today. Result: Fair Value of $263.75 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Brinker International’s heavy tilt toward dine in occasions, along with ongoing labor and food cost pressure, could both chip away at the smooth earnings path this narrative assumes.
Find out about the key risks to this Brinker International narrative.
Another View: Brinker International Through The Cash Flow Lens
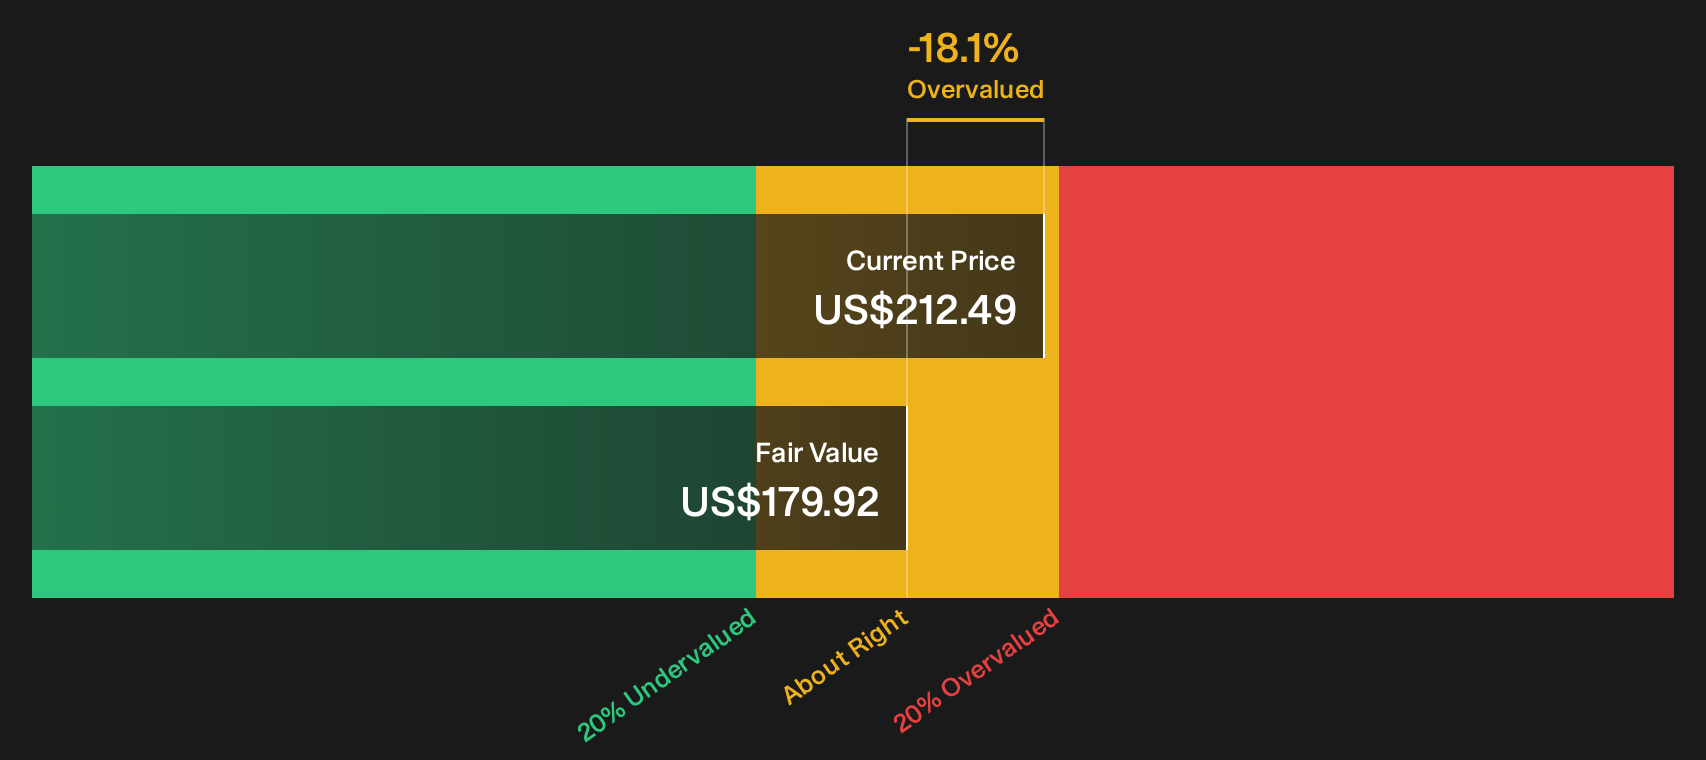
The first narrative leans on a fair value of $263.75 using earnings, multiples and analyst targets. A different lens comes from the SWS DCF model, which points to a future cash flow value of $179.92, with Brinker International trading above that level at $212.49.
That gap suggests the current share price builds in stronger or more durable cash generation than the DCF model assumes, even though analysts still see upside from here. For anyone following EAT closely, the key question is which set of assumptions feels more realistic for the next few years.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Brinker International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Strong share price gains and a pullback like Brinker International has seen tend to split opinion. Use that debate as a prompt to move quickly, review both the potential risks and upside drivers, then weigh the 5 key rewards and 2 important warning signs
Ready for more Brinker International style ideas?
If you like the way Brinker International has reshaped its story, do not stop here. Use the Simply Wall St screener to hunt for your next edge.
- Target resilient opportunities that balance quality and value by scanning our hand picked 31 high quality undervalued stocks before the market fully prices them in.
- Prioritise stability and sleep better at night by reviewing the 11 resilient stocks with low risk scores that score well on resilience and business strength.
- Get ahead of the crowd by tracking a curated list of solid balance sheet and fundamentals (23 results) that can better withstand shocks and keep compounding over time.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com