


Dole has delivered an 18.9% gain over the past three years, yet the broader valuation checks paint a mixed picture that keeps the stock from looking like a straightforward bargain or an obvious trap at recent levels.
- The 18.9% return over three years suggests patient shareholders have been rewarded, even though the stock has moved sideways over the past year.
- The lawsuit filed in Waialua over alleged flood related mismanagement may weigh on sentiment and potential legal costs. At the same time, the underlying global produce operations can still support steady cash generation that matters for long term valuation.
- The stock appears undervalued on earnings multiples, but with a mixed overall value score. Only 4 of 6 checks line up as cheap, which points to a more balanced setup than a clear discount.
For investors, the debate is whether Dole's current price already reflects these legal and business risks or still offers enough value support for the next few years.
Compare Dole's mixed valuation and recent flat 1 year return with other hand picked value opportunities by scanning 31 high quality undervalued stocks with similar earnings support and balance sheet strength.
Is Dole a Bargain on Earnings?
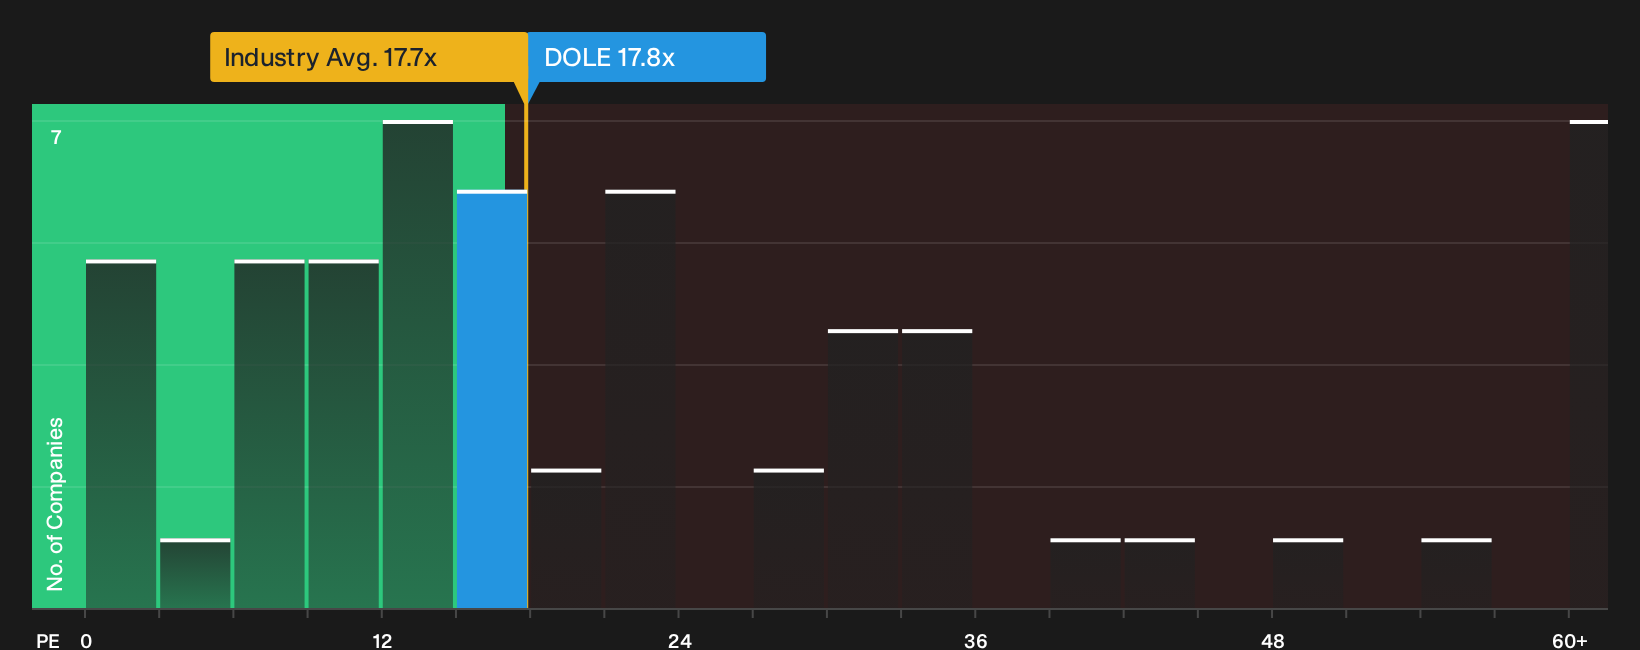
The P/E ratio suits Dole because earnings still sit at the center of how investors judge a mature food producer. On that metric, the stock trades at about 17.8x earnings, which is roughly in line with the broader food industry on 17.7x. Peers as a group change hands closer to 23.6x, so the market is not assigning Dole a peer level premium despite its global footprint.
The fair P/E multiple for Dole, based on its profile and risk mix, sits near 20.5x. That is a clear gap above the current 17.8x mark, which implies the equity is priced below what this model suggests for the business. Despite the lawsuit over the March flooding in Waialua weighing on sentiment, the P/E still prices Dole at a discount to similar companies and the tailored fair ratio.
On the P/E multiple alone, Dole appears undervalued compared with both its fair ratio and broader peer group.
See what the numbers say about this price — find out in our valuation breakdown.
The Dole Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Dole pick up where this valuation puzzle leaves off and spell out which combinations of future growth, margins and earnings would need to play out for the stock to be worth materially more or less than today's price on the Community page. Each narrative treats Dole's implied fair value as a thesis about the business that can be tracked over time rather than a one off snapshot, so you can see how the story holds up as new information arrives.
One of the top community narratives on Dole: roughly fairly valued
"Exposure to extreme weather, crop diseases, and lack of diversification creates persistent risk to supply, costs, and revenue stability..."
Read one of the top narratives on Dole
Do you think there's more to the story for Dole? Head over to our Community to see what others are saying!
The Bottom Line
Dole screens as mildly undervalued on earnings, yet the broader checks point to a more balanced picture than a clear bargain. The key question is whether that modest discount compensates you for legal overhangs and the operational risks that come with global farming exposure. If you think the market is overstating those pressures, the current P/E could look appealing. If you believe weather, litigation and cost volatility will keep weighing on sentiment, the present valuation may simply reflect those ongoing uncertainties.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com