


Silicon Motion Technology (SIMO) just secured ISO/SAE 21434:2021 automotive cybersecurity process certification, a third party validation of its development framework for secure in vehicle storage and a fresh talking point for investors.
The cybersecurity certification arrives as Silicon Motion Technology trades at US$284.48, with a 1-day share price return of 7.25% and a 30-day share price return of 17.89%. The 1-year total shareholder return of 225.01% and 3-year total shareholder return of almost 5x indicate that recent conference appearances and product credentials are reinforcing this momentum rather than reversing it.
Capitalize on Silicon Motion Technology's cybersecurity momentum by scanning a curated set of 11 resilient stocks with low risk scores that pair resilient financial profiles with similar defensive tech themes.After a 7.25% single day jump and a 1 year total return above 200%, Silicon Motion Technology now trades well below the average analyst target. Is that discount pointing to mispricing, or just generous models ahead of a reset?
Most Popular Narrative: 23.1% Undervalued
Analysts in the most followed Silicon Motion Technology narrative see fair value at $369.70, which sits well above the recent $284.48 close and frames today’s rally in a very different light.
The rapid expansion of high-performance storage demand from AI, data centers, cloud computing, and edge computing is fueling adoption of advanced NAND controller solutions, particularly Silicon Motion's PCIe Gen 5 and enterprise-focused MonTitan controllers, supporting robust future revenue and margin growth as these markets scale.
Read the complete narrative. Read the complete narrative.
Want to see what is behind that gap between price and fair value? The story leans on brisk top line expansion, sturdier margins, and a future earnings profile that assumes Silicon Motion Technology keeps winning higher value controller slots across AI heavy workloads.
Result: Fair Value of $369.70 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the bullish Silicon Motion Technology storyline depends on intense NAND controller competition not compressing margins further and on customer concentration risk not turning forecast wins into revenue volatility.
Find out about the key risks to this Silicon Motion Technology narrative.
Another View: SWS DCF Model Sees Less Upside
The analyst narrative paints Silicon Motion Technology as 23.1% undervalued, yet the SWS DCF model tells a colder story. On that cash flow work, the fair value lands at $159.92, well below the current $284.48 price, which implies expectations already bake in a heavy dose of future success. That gap leaves you weighing which set of assumptions you trust more.
To see how that cash flow outcome is built, and how sensitive it is to growth and margin inputs, Look into how the SWS DCF model arrives at its fair value.
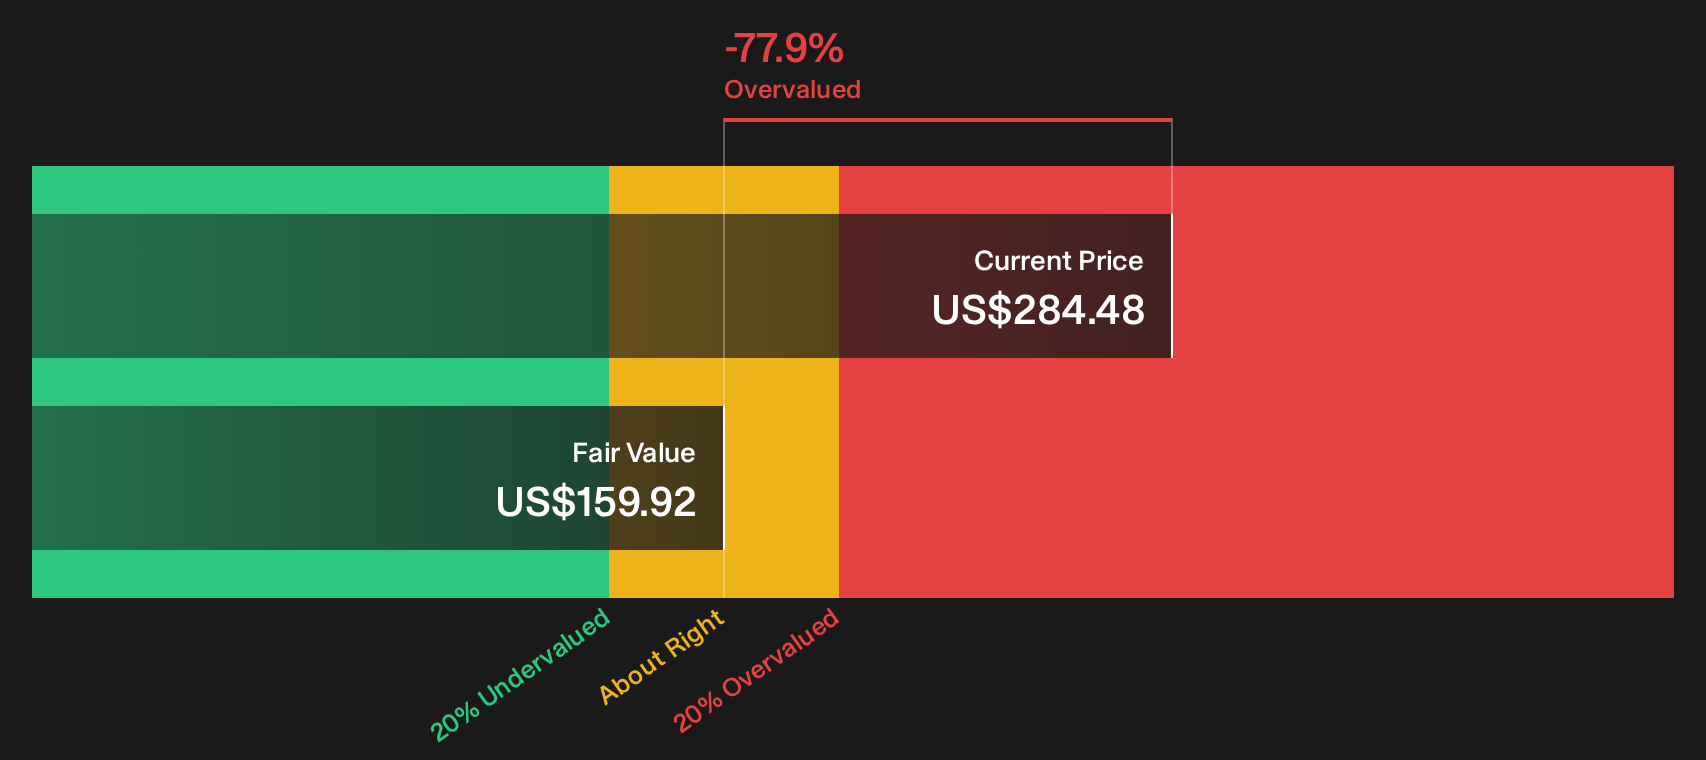
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Silicon Motion Technology for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty of enthusiasm runs through this Silicon Motion Technology story, yet the mix of flagged issues and upside drivers deserves your own fresh read of the data. To weigh that balance for yourself and move quickly from headline to conclusion, take a closer look at the 5 key rewards and 3 important warning signs
Looking for more investment ideas beyond Silicon Motion Technology?
If you only stop at Silicon Motion Technology, you risk missing other opportunities that could fit your risk, income, or value goals just as well.
- Target resilient balance sheets and cleaner fundamentals by scanning the list of solid balance sheet and fundamentals (23 results) that match your comfort level on financial strength.
- Zero in on potential value opportunities early by reviewing the 16 high quality undiscovered gems before they attract broader attention.
- Build a portfolio with clearer downside protection by focusing on 11 resilient stocks with low risk scores that align with your tolerance for volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com