


Eldorado Gold (TSX:ELD) just crossed a key milestone at its Skouries Project in northern Greece, producing first copper gold concentrate as the site shifts from construction toward full operations.
Investors have been leaning into the Eldorado Gold story over the past year, with a 90 day share price return of 41.40% and a 1 year total shareholder return of 56.71% around the latest Skouries milestone, suggesting momentum has been building rather than fading.
Scan beyond Eldorado Gold and line up other potential beneficiaries of the gold momentum cycle with the curated 35 elite gold producer stocks.
The share price has already sprinted on the Skouries milestone and a rich pipeline of producing assets. Does Eldorado Gold still offer enough upside potential to justify the risk at today’s valuation?
Most Popular Narrative: 4.2% Overvalued
The most followed Eldorado Gold narrative pegs fair value at CA$58.16, slightly below the last close at CA$60.62, which points to a modest premium being priced in by the market today.
The approaching commissioning of the Skouries copper gold project, slated for Q1 2026 and on schedule, is expected to be transformative by materially increasing production volumes, diversifying the revenue mix, and expanding EBITDA margins due to the asset's high grades and lower costs relative to existing operations. Ongoing operational optimization initiatives at flagship sites such as Kişladağ and Lamaque are expected to lower all in sustaining costs and enhance net margins and free cash flow as operational efficiencies and higher grades flow through to financials.
Want to see what kind of revenue surge and margin profile Eldorado Gold would need for that valuation to hold up. The narrative leans on brisk top line expansion, thicker profitability and a future earnings multiple that looks leaner than today. Curious how those moving parts combine into a single fair value number.
Result: Fair Value of CA$58.16 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Eldorado Gold faces real pressure points, including elevated all in sustaining costs and complex Skouries ramp up risks that could upset the current fair value story.
Find out about the key risks to this Eldorado Gold narrative.
Another View: SWS DCF Flags Deep Undervaluation
The analyst narrative pegs Eldorado Gold at a modest 4.2% premium to its CA$58.16 fair value, yet the SWS DCF model lands in a very different place, with a future cash flow value of CA$127.56, which is 52.5% above the current CA$60.62 share price.
That gap suggests the market price could be giving far less weight to long term cash generation than this cash flow model does. The key question is which set of assumptions you place more confidence in for Eldorado Gold.
Look into how the SWS DCF model arrives at its fair value.
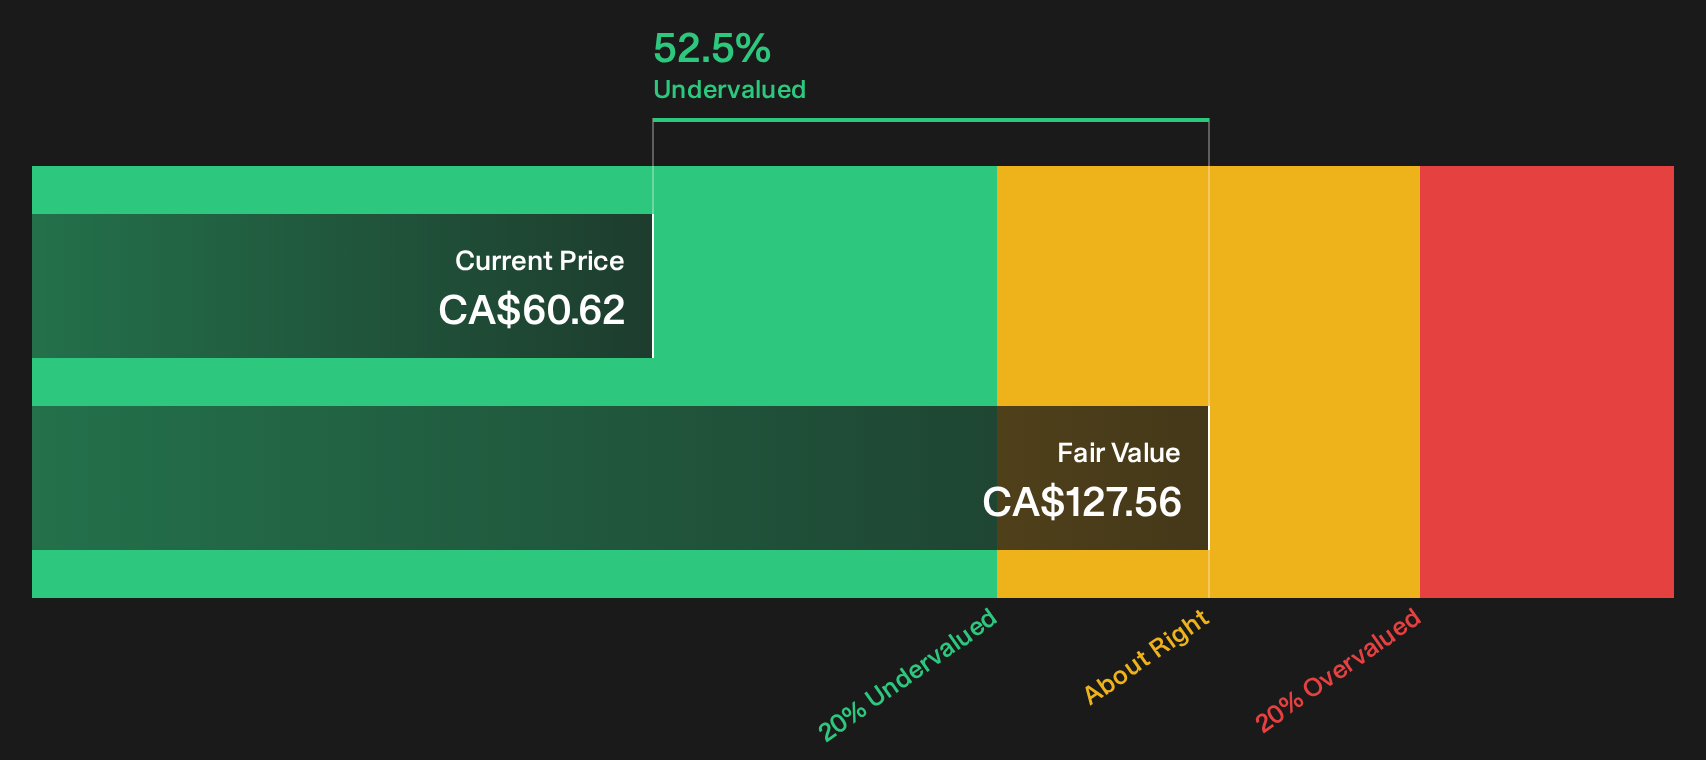
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Eldorado Gold for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the Eldorado Gold story so far. If you want to move fast and build your own view on the balance of concerns and potential upside, start by weighing 3 key rewards and 3 important warning signs.
Looking for more Eldorado Gold sized investment ideas?
Do not stop with Eldorado Gold. Use the Simply Wall St screener to quickly surface fresh stock ideas that fit your risk, income, and value preferences.
- Target long term value by scanning for resilient cash generators through the 5 high quality undervalued stocks.
- Build a steadier income stream by hunting for reliable high yield payers in the 2 dividend fortresses.
- Dial back portfolio stress by focusing on sturdier businesses with the 1 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com