


- Shiseido Company recently introduced the Vital Perfection Intensive SculptDefine Serum, a lifting skincare product that applies proprietary D-AminoLift Complex™, Watercress Extract and 4MSK to target facial sagging, firmness, dark spots and dullness, with clinical data indicating visible improvements across multiple wrinkle and tone concerns within one week.
- The new serum strengthens Shiseido's higher end skincare lineup with a clinically supported lifting and brightening formula that can support premium pricing, deepen engagement with aging skin consumers and potentially reinforce the brand's focus on science led skincare within its broader portfolio.
- We will examine how Shiseido's clinically backed Vital Perfection lifting serum launch might influence the existing premium skincare investment narrative.
Scan how Shiseido Company's science led serum launch compares with other premium beauty plays by tracking the 73 high quality undiscovered gems that are still flying under most investors' radar.
Shiseido Company Investment Narrative Recap
To own Shiseido Company, you need to believe its reset toward prestige skincare and structural reform can turn a loss making business into a steadier, higher margin operator over time. The Vital Perfection Intensive SculptDefine Serum fits that story, but on its own it does not change the near term picture of modest forecast revenue growth and a still unprofitable group.
The closer in focus issue remains execution. Recovery in weaker regions such as the Americas, control of high marketing and restructuring costs, and pressure in China and Japan are still the swing factors. If those pressures persist, a 1.4x P/S multiple and expectations for margin improvement could become harder to defend.
The Vital Perfection serum launch aligns tightly with the stated catalyst of leaning into science led prestige skincare. It gives Shiseido Company another clinically supported product that can justify premium pricing, speak directly to aging skin customers, and support the broader push to raise average selling prices across the portfolio.
The risk side does not disappear, though. Premium launches require heavy promotion and could add to already high marketing spend if sales productivity disappoints. For you as an investor, the key question is whether launches like this can scale through e commerce, China and Travel Retail fast enough to offset restructuring fatigue and regional volatility.
Shiseido Company's analyst narrative points to revenues of ¥1,076.0b and earnings of ¥59.2b by 2029, which assumes yearly sales growth of 2.5% and an earnings swing of about ¥79.7b from the current loss of ¥20.5b to the projected profit.
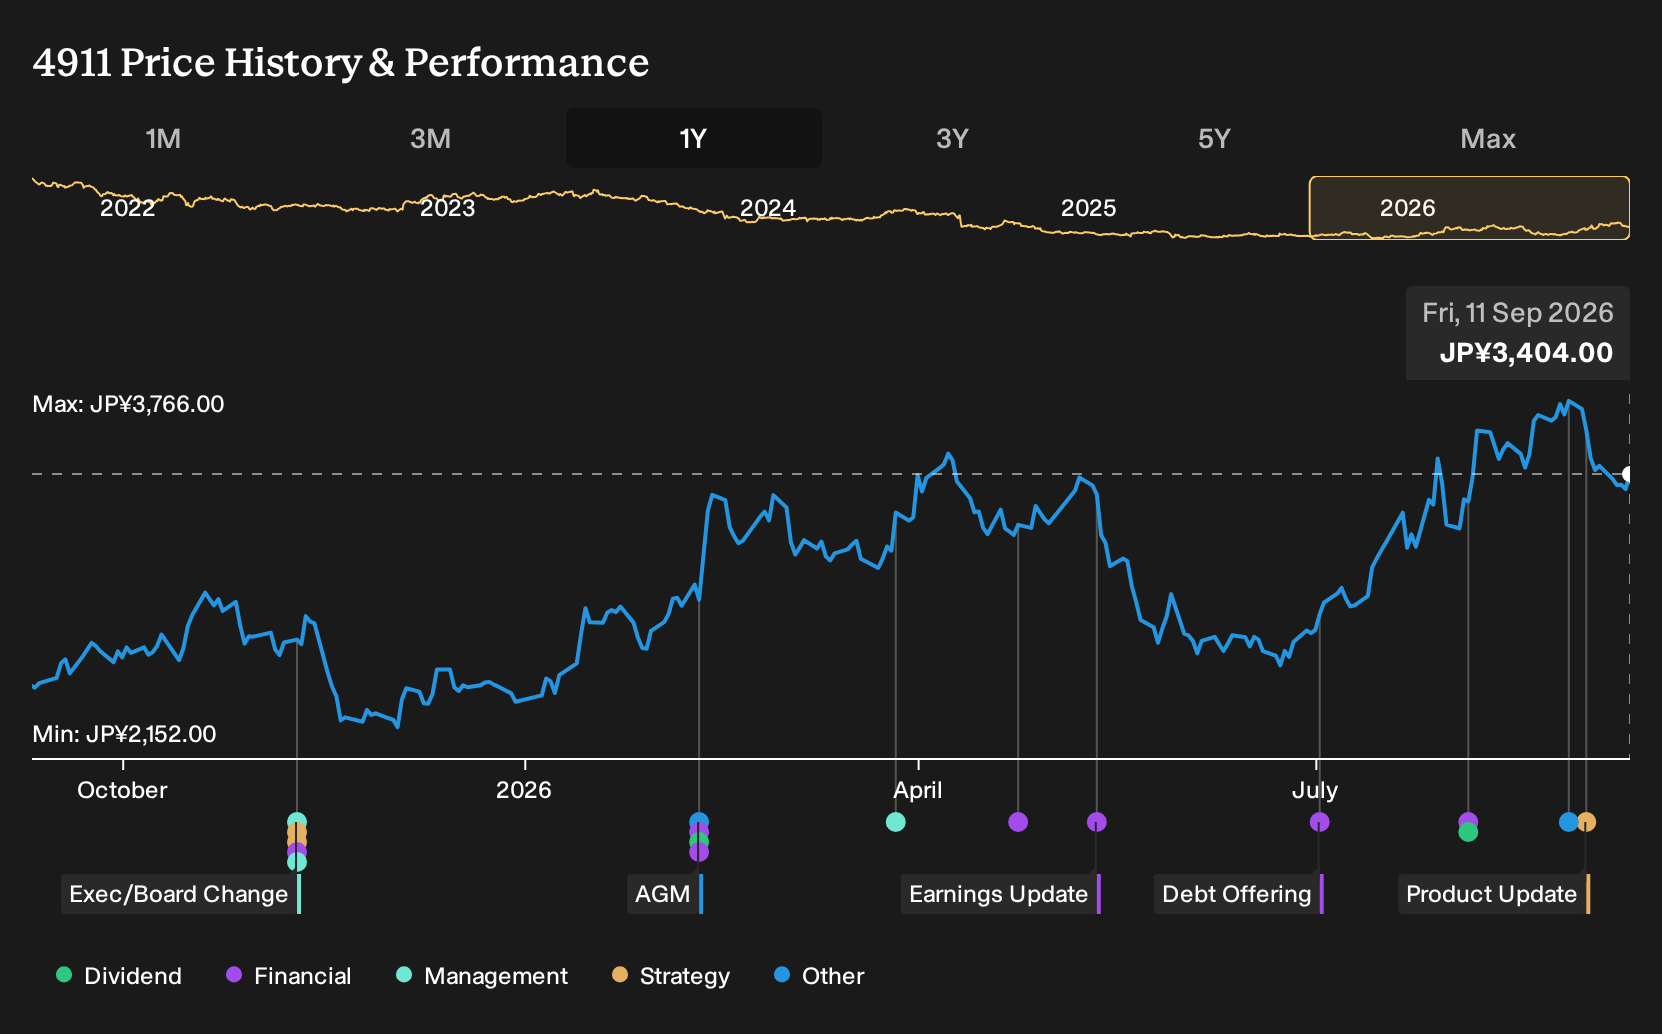
Uncover why Shiseido Company's fair value indicates a 3% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
The lowest-ranked analysts focus on one key point that the Vital Perfection launch highlights. They worry that Shiseido Company is leaning too heavily on cost cuts while sales remain relatively flat. Their models assume revenue of about ¥1,043.7b and earnings of ¥55.5b by 2029, which is meaningfully below consensus. These views were set before this serum announcement, so you may want to compare both narratives and decide which assumptions you find more realistic.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Shiseido Company research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Shiseido Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Shiseido Company's overall financial health at a glance.
Looking For More Investment Ideas Beyond Shiseido Company?
If Shiseido Company has you thinking about where premium brands and solid fundamentals intersect, it can help to compare it with other opportunities that fit clear, rules based criteria. The Simply Wall St Screener lets you do exactly that by filtering for factors that matter to you, from balance sheet strength to income potential.
- For investors who put capital preservation and financial resilience first, start by scanning companies with stronger finances using our list of solid balance sheet and fundamentals (19 results).
- If you are looking for income ideas to support a dividend focused portfolio, review the 19 dividend fortresses and see which payouts look more dependable based on the numbers.
- When you want to widen the search beyond well known tickers, use the 73 high quality undiscovered gems to identify under the radar businesses with healthier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com