


- Universal Music Group has already entered a multi year licensing and product development agreement with ElevenLabs to build an AI powered music creation platform that uses licensed catalog and artist participation to support remixes, mashups, new track versions, and personalized vocal experiences.
- The deal gives Universal Music Group a controlled way to test AI driven fan co creation while keeping licensing, artist consent, and songwriter compensation within its own commercial framework.
- We will now look at how Universal Music Group's AI music platform partnership with ElevenLabs could reshape the existing investment narrative.
Scan the AI music theme across the market and compare Universal Music Group's move with other players using our curated list of 89 AI infrastructure stocks.
Universal Music Group Investment Narrative Recap
To own Universal Music Group, an investor needs to believe the recorded music, publishing, and merchandising engine can convert a €12.8b revenue base into higher, more stable earnings over time. The ElevenLabs partnership plugs directly into that belief by testing AI driven fan engagement inside a licensed, controlled environment rather than letting that activity sit on unlicensed platforms.
In the near term, the key swing factor is whether monetization of streaming and new tiers offsets weak short form economics and margin pressure, with net profit margins currently at 2.5% and dividend cover thin. The largest risk remains that AI and user generated content dilute catalog value faster than Universal Music Group can channel that behavior into licensed, paid formats.
The ElevenLabs deal lines up most clearly with existing AI partnerships such as the Apple Music Sound Therapy work referenced in the broader catalyst set. Together, these projects show Universal Music Group leaning into technology to extend catalog usage into wellness, personalization, and co creation rather than treating AI purely as a defensive issue.
For you as a shareholder, the practical question is execution. Management now has to prove that AI powered remixing and personalized vocals sit within a royalty and licensing framework that improves ARPU and does not erode bargaining power with streaming and social platforms. If that happens, these products could support Streaming 2.0 economics and the planned €250m cost efficiency program rather than distract from them.
Universal Music Group's narrative projects €15.9b revenue and €2.0b earnings by 2029. This aligns with analysts assuming 7.4% yearly revenue growth and implies an earnings increase of about €1.7b from €323.0m today.
Uncover why Universal Music Group's fair value indicates a 63% potential upside to its current price and why that gap could narrow quickly.
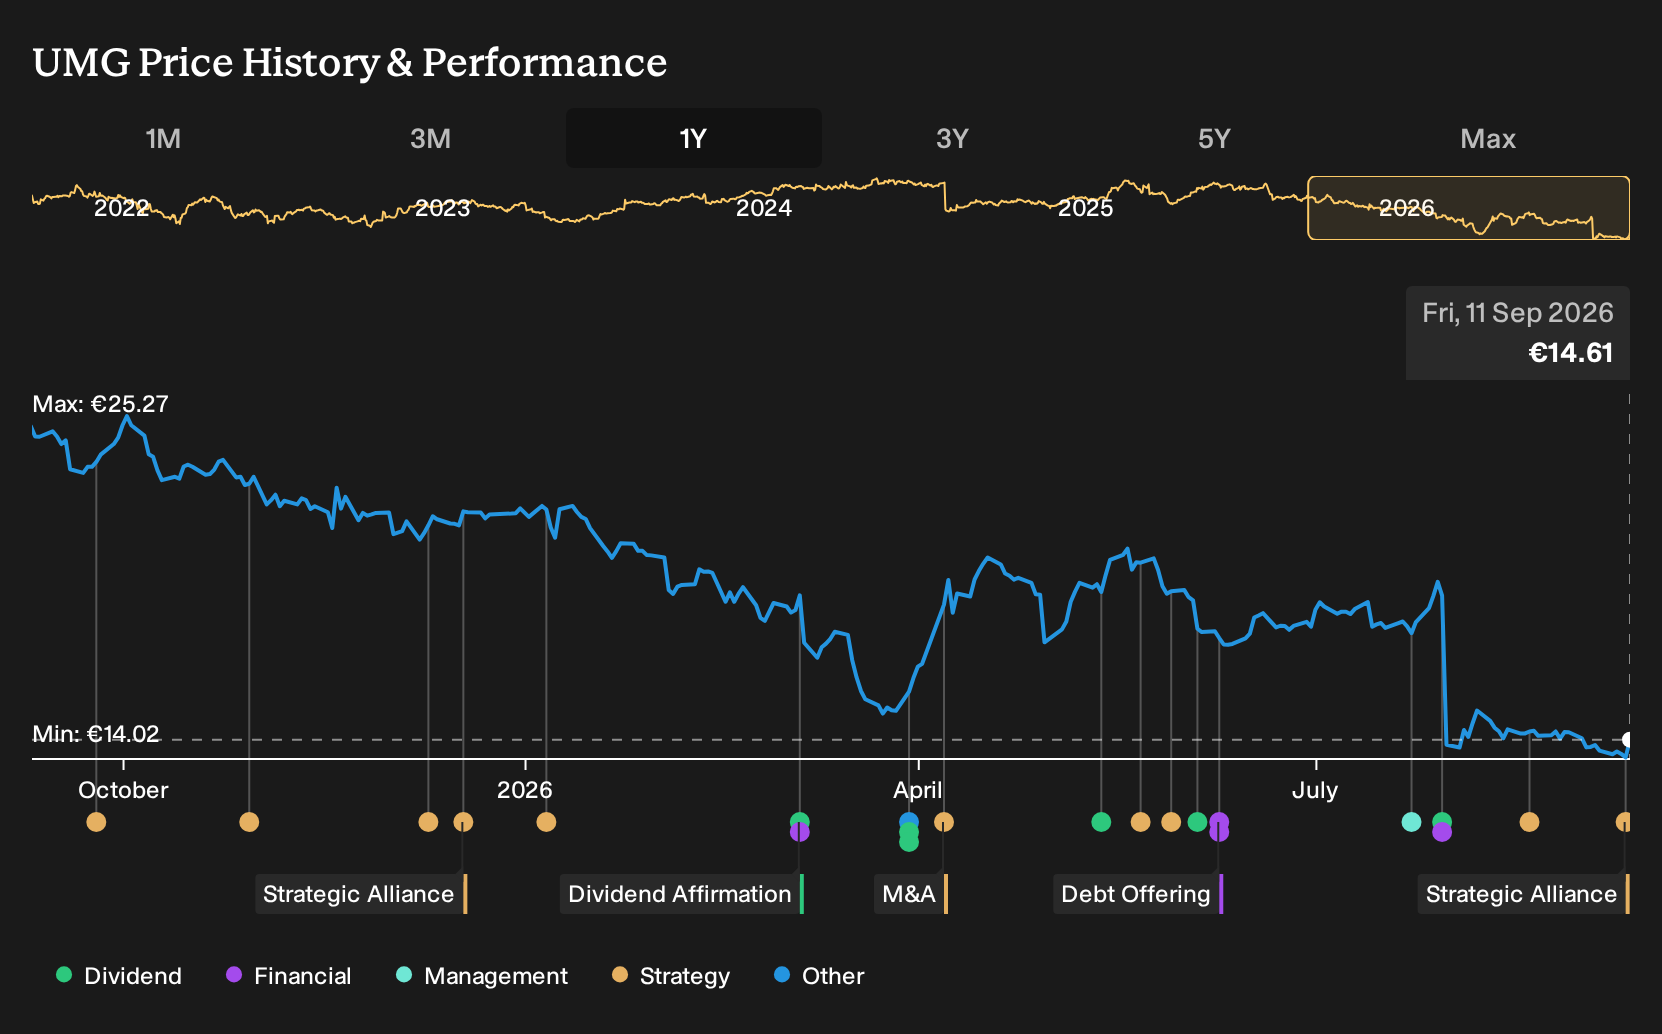
Exploring Other Perspectives
Some of the most optimistic analysts already framed Universal Music Group as an AI and experiences story, not just a streaming one. Before this ElevenLabs deal, the bullish camp was pencilling in €16.3b revenue and €2.6b earnings by 2029. You can see how this fresh AI platform might push those views further, while other investors will stay closer to the €15.9b and €2.0b consensus path. Opinions are likely to spread out rather than converge, and that spread can be used as a prompt to test your own assumptions about AI risk and reward.
Explore 6 other Universal Music Group fair value estimates, including one that suggests as much as 139% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Universal Music Group research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Universal Music Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Universal Music Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Universal Music Group?
If the Universal Music Group story has sharpened your thinking about AI, royalties, and long term earnings power, it can be useful to line that up against other opportunities that share some of the same themes or offer very different risk profiles. The Simply Wall St Screener gives you a structured way to do that comparison in minutes rather than hours.
- For investors who want potential growth with a strict focus on balance sheet strength and fundamentals, consider our list of solid balance sheet and fundamentals (194 results) to see which companies clear those hurdles.
- If your priority is stability and income, scan a focused universe of high yield payers using our 164 dividend fortresses and see how they compare to Universal Music Group on cash generation and payouts.
- For those hunting for under the radar opportunities with robust financial traits, the 619 high quality undiscovered gems can surface stocks that may not be widely followed but still pass disciplined quality filters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com