


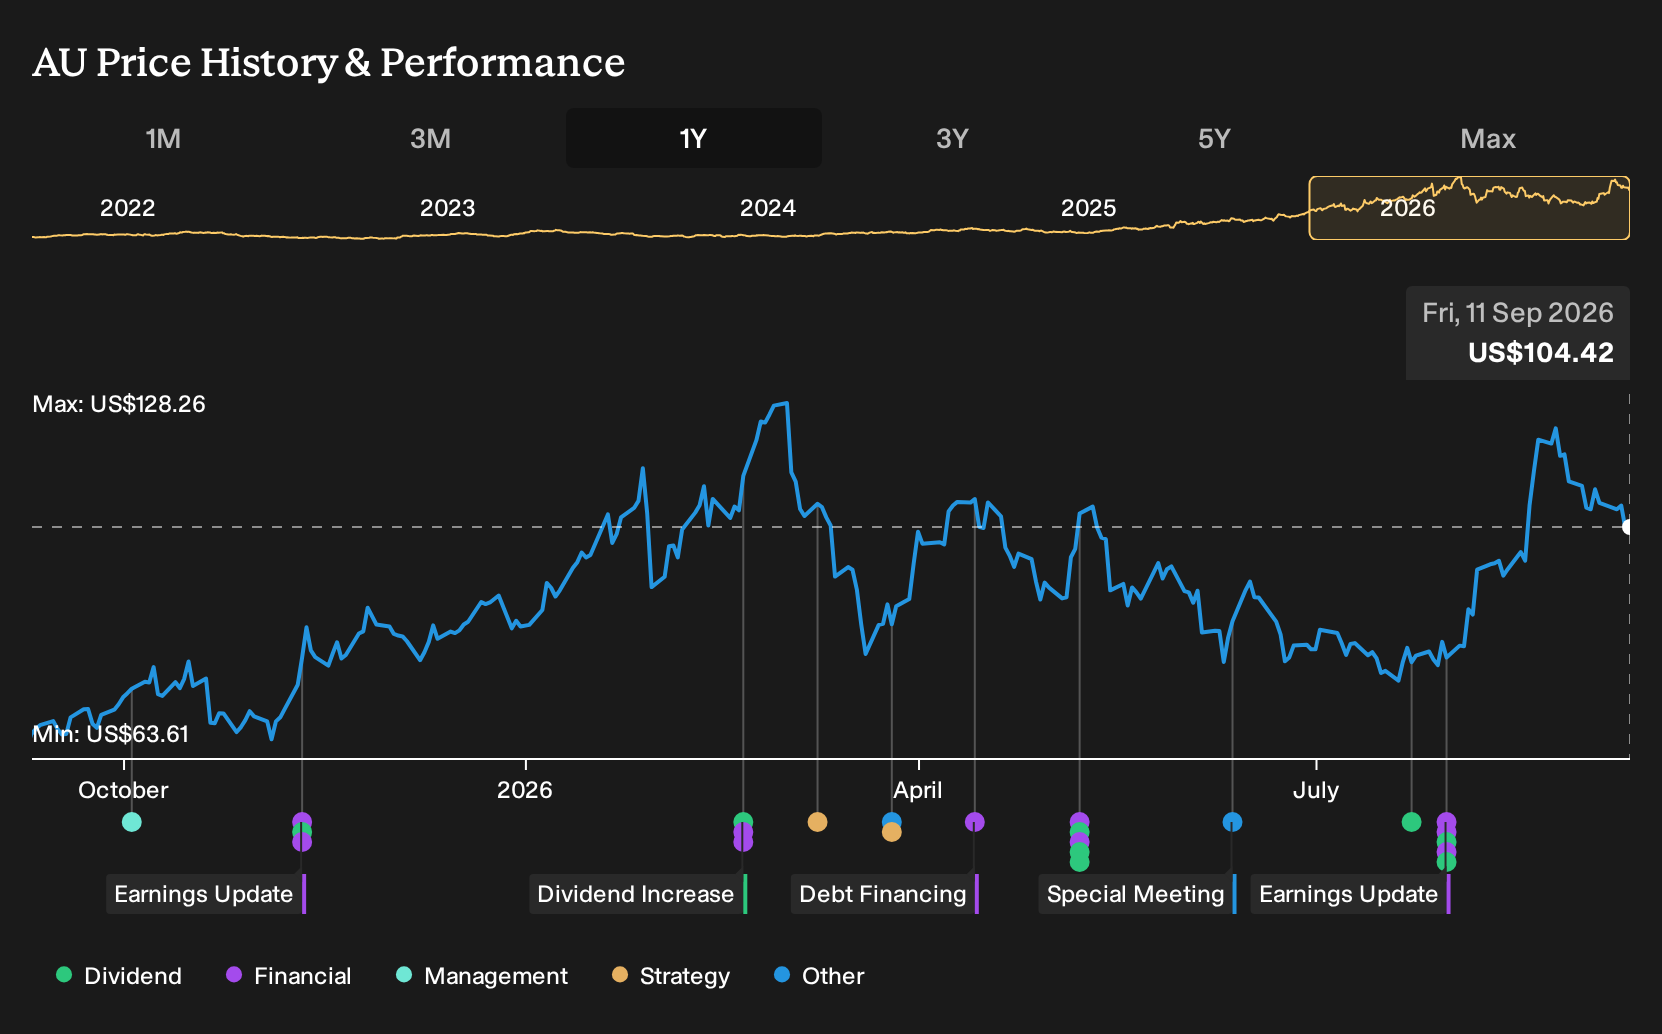
- BMO Capital Markets recently downgraded AngloGold Ashanti to Market Perform after several years of share price gains left the miner trading at a clear premium to its estimated net asset value. Operations are expected to remain broadly steady, and the Arthur Gold Project in Nevada is viewed as a longer term growth option.
- The key tension for AngloGold Ashanti now sits between a portfolio that appears set for operational stability and future Nevada driven expansion, and a valuation that some analysts see as already pricing in much of that potential.
- This article will examine how AngloGold Ashanti's investment narrative, built on stable output and Nevada growth, is challenged by concerns over stretched valuation.
Compare AngloGold Ashanti's premium rating with peers and review other potential breakout producers across 35 elite gold producer stocks before deciding where fresh capital works hardest.
AngloGold Ashanti Investment Narrative Recap
To own AngloGold Ashanti, you need to believe the current portfolio can keep production reasonably steady while projects like Arthur in Nevada add new ounces over time. The downgrade does not change that operational story. The more immediate swing factor is how well management keeps total cash costs and all in sustaining costs in check as inflation, royalties, and grade mix keep pushing on expenses.
The biggest risk right now is margin pressure if those costs bite harder while revenue stays flat or slips. Regulatory and permitting timelines for the Nevada projects also matter in the near term. If approvals take longer or compliance demands rise, the timing of any Nevada driven lift could push further out without changing the underlying project potential.
Recent commentary around the Arthur Gold Project in Nevada is the most relevant piece of news to link to this downgrade. That asset sits at the center of the long runway for AngloGold Ashanti because it anchors the move toward more exposure in lower risk jurisdictions and adds another leg to organic production growth alongside Obuasi, Cuiabá, Siguiri, and Geita.
For you, the key question is how execution on Arthur and the broader Nevada pipeline lines up with the valuation the market is already assigning. Any permitting delays, higher capital intensity, or tougher ESG requirements would raise execution risk and could soften the impact of those catalysts. If things track close to plan, the long life profile of Nevada still frames much of the forward thesis for AngloGold Ashanti.
On these analyst assumptions, AngloGold Ashanti is tied to forecasts of about $12.1b in revenue and $5.5b in earnings by 2029, with revenue expected to stay broadly flat and earnings rising by roughly $1.7b from the current $3.8b base.
Uncover why AngloGold Ashanti's fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus less on cost risk and more on what AngloGold Ashanti could earn if the growth pipeline really delivers. Before this downgrade, the bullish camp was working off revenue closer to US$20.0b and earnings around US$6.4b by 2029. Those upbeat views may shift once this new rating feeds into their models, so treat them as one of several viewpoints to explore rather than a script to follow.
Explore 5 other AngloGold Ashanti fair value estimates, including one that suggests as much as 28% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own research and judgment.
- A great starting point for your AngloGold Ashanti research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AngloGold Ashanti. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AngloGold Ashanti's overall financial health at a glance.
Looking for more investment ideas beyond AngloGold Ashanti?
If AngloGold Ashanti has sharpened your thinking about risk, valuation, and growth projects, it can be helpful to widen the lens and compare it with a broader set of opportunities using the Simply Wall St Screener.
- For investors who want potential growth without ignoring balance sheet strength, scan through a list of solid balance sheet and fundamentals (23 results) that can handle pressure when conditions change.
- If you prefer income on top of capital appreciation, review a focused set of 6 dividend fortresses that aim to keep cash returns front and centre.
- To cast a wider net across less crowded ideas, filter through a 16 high quality undiscovered gems that combine quality fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com