


Archer-Daniels-Midland has delivered a 60.1% total return over the past five years, yet its valuation checks are pulling in different directions, with the Discounted Cash Flow (DCF) pointing to undervaluation while market multiples lean the other way.
- A 60.1% gain over five years suggests Archer-Daniels-Midland has already rewarded patient holders. Fresh buyers therefore need to think carefully about what is priced in.
- Planned additional oilseed crushing capacity in the U.S. can support expectations for future cash flows, while the ongoing SEC fraud case involving the former CFO may weigh on how much investors are willing to pay for those earnings.
- A value score of 3 out of 6 signals a mixed picture rather than a clear bargain or an obviously expensive stock.
The issue now is whether Archer-Daniels-Midland's current share price already reflects its intrinsic value, or if the DCF estimate still points to room for upside over the coming years.
Spot opportunities with Archer-Daniels-Midland's peers by scanning our hand picked list of 31 high quality undervalued stocks.Is Archer-Daniels-Midland Still Cheap on Cash Flow?
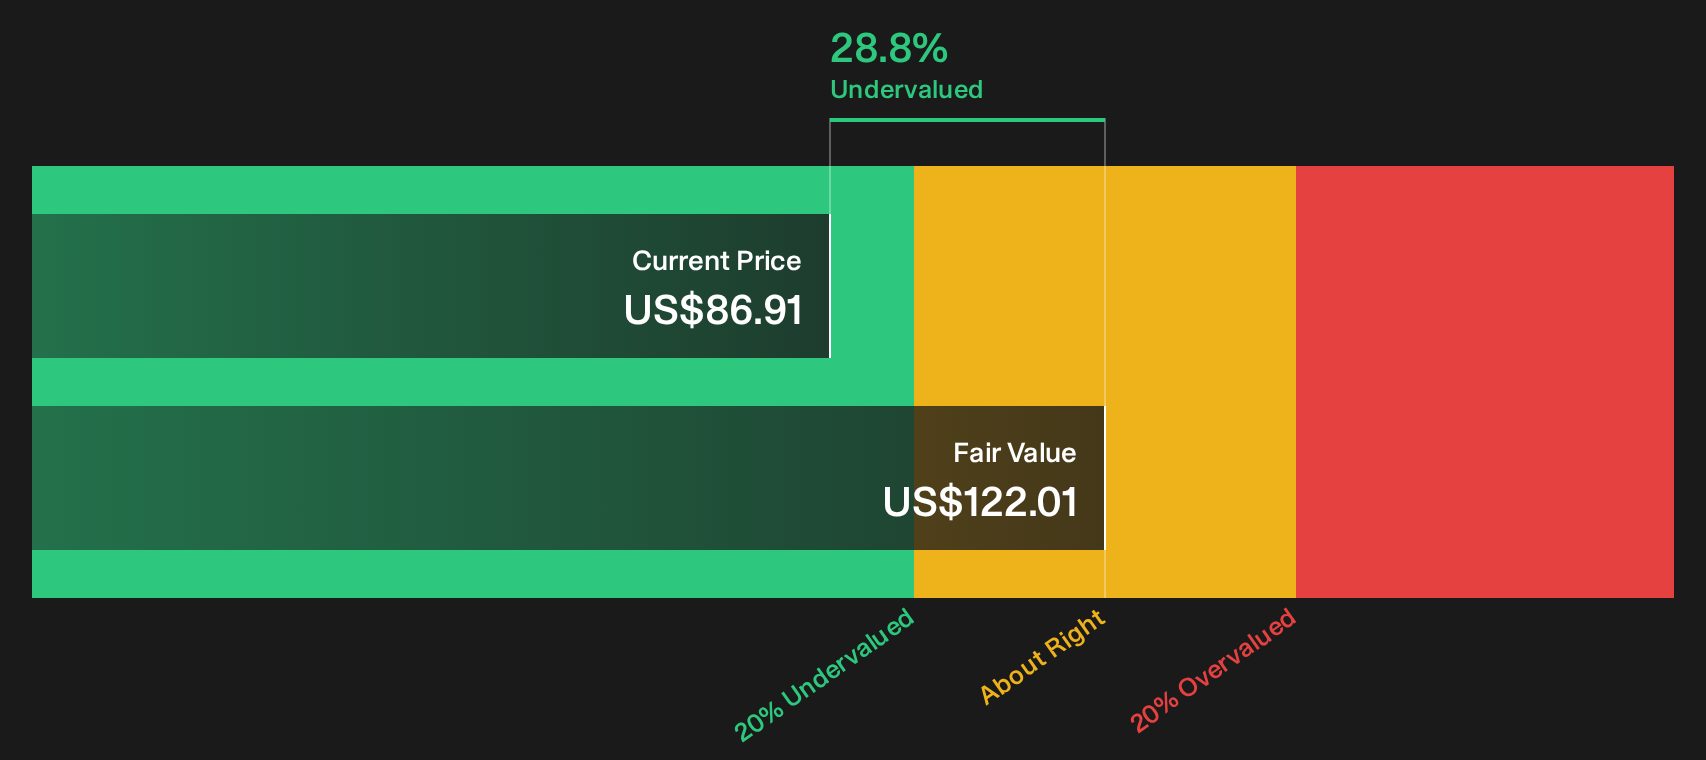
The Discounted Cash Flow (DCF) model here looks at Archer-Daniels-Midland through the lens of the cash it can return to shareholders over time. Latest twelve month free cash flow sits at about $1.45b, and the projections assume a growing but measured cash flow path rather than an aggressive surge.
Using those inputs, the model points to an estimated intrinsic value of about $122 per share. This implies the stock screens roughly 28.9% undervalued versus the current market price. That gap reflects expectations that Archer-Daniels-Midland can sustain healthy cash generation while keeping capital spending and shareholder returns in balance.
The SEC fraud case involving the former CFO, including the large document haul and the $40 million civil penalty, helps explain why the market hesitates to fully credit that DCF value today. At the same time, the planned $100 million expansion in oilseed crushing capacity supports the idea that management is still investing behind those projected cash flows.
On balance, the Discounted Cash Flow work suggests Archer-Daniels-Midland stock currently looks undervalued relative to the cash it is expected to produce.
Our Discounted Cash Flow (DCF) analysis suggests Archer-Daniels-Midland is undervalued by 28.9%. Track this in your watchlist or portfolio, or discover 31 more high quality undervalued stocks.
Does Archer-Daniels-Midland Look Pricey on Earnings?
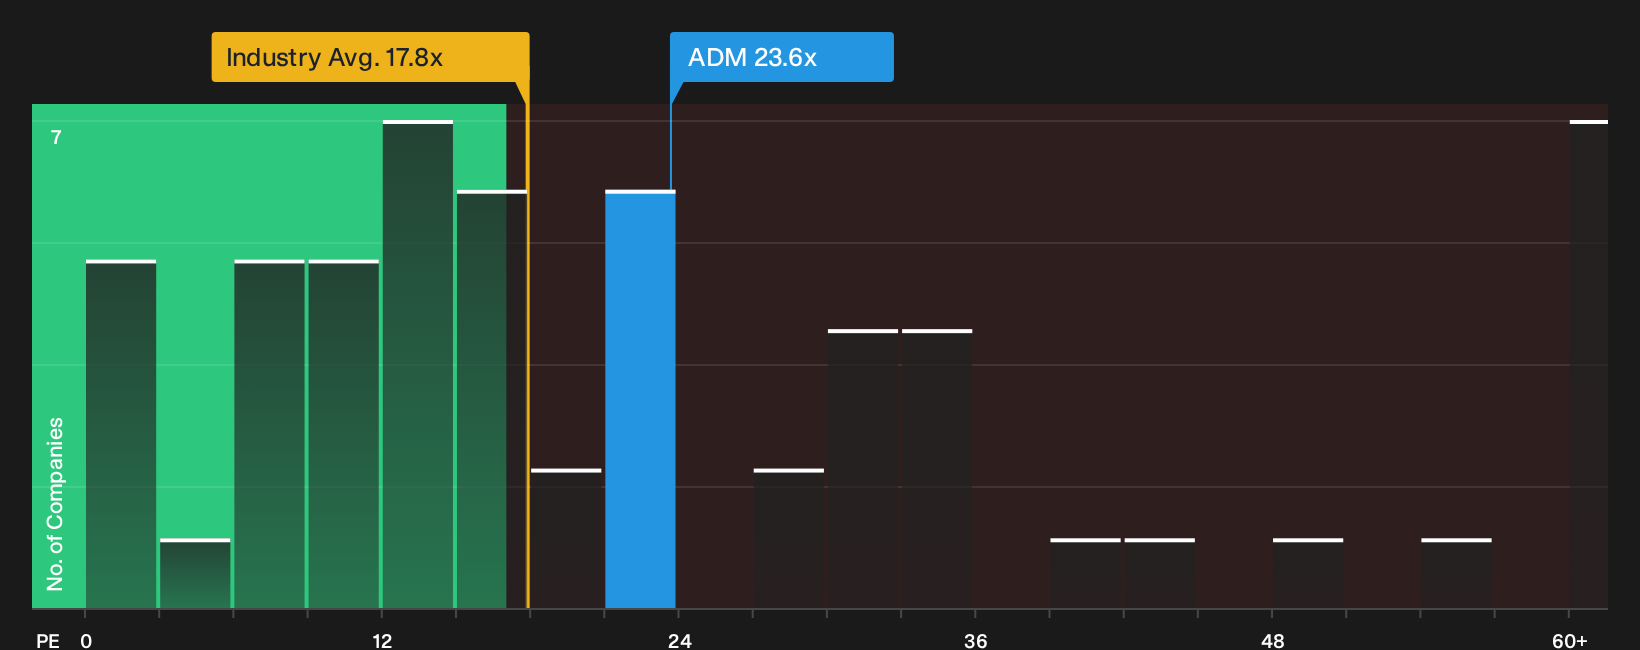
P/E works reasonably well for Archer-Daniels-Midland because earnings power is a key lens for a mature, cash generative agribusiness. On this measure, the stock trades on about 23.6x earnings, almost identical to the 23.7x peer average in the sector, but well above the broader Food industry at roughly 17.7x. That already puts the shares at a premium to the wider group of food producers.
The fair P/E implied by the model is closer to 18.7x, which is materially lower than where Archer-Daniels-Midland changes hands today. This framework factors in the company’s size, margins and risk profile, and then indicates that investors are paying more than those fundamentals would support on a pure earnings multiple view.
On this P/E yardstick, Archer-Daniels-Midland stock screens as overvalued versus what the fair multiple suggests.
See what the numbers say about this price — find out in our valuation breakdown.
The Archer-Daniels-Midland Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Archer-Daniels-Midland valuation puzzle leaves off and explain which paths for growth, margins and earnings would need to occur for the stock to be worth materially more or less than today’s price, all hosted on the Community page. Each scenario links its number to a clear view on how Archer-Daniels-Midland's growth, profitability and risk profile could change, which you can revisit as fresh information becomes available.
Community views on Archer-Daniels-Midland are pulled in opposite directions, with one camp leaning into upside potential and another seeing limited mispricing.
Bull case: 9% undervalued
"Expansion in enhanced nutrition, including allergen free pea protein, ultra high protein drinks, protein bars, fortified snacks and specialty ingredients, positions ADM to serve growing demand for value added food and beverage solutions…"
Read the full Bull Case to see why Archer-Daniels-Midland could be undervalued
Bear case: 10% overvalued
"Analysts are assuming Archer-Daniels-Midland's revenue will grow by 2.5% annually over the next 3 years…"
Read the full Bear Case to see why Archer-Daniels-Midland could be overvalued
Do you think there's more to the story for Archer-Daniels-Midland? Head over to our Community to see what others are saying!
The Bottom Line
Archer-Daniels-Midland looks cheap on a Discounted Cash Flow (DCF) view, with the intrinsic value estimate sitting comfortably above the current share price, yet the P/E view leans toward overvalued compared with what its fundamentals and peers suggest. That split comes from the DCF leaning on long term cash generation and capital spend, while the multiple view is more about current sentiment and how much investors are paying for each dollar of earnings today. Broader checks look mixed rather than decisive. The real swing factor now is whether the market eventually trusts Archer-Daniels-Midland's cash flow profile enough to narrow that gap, given the governance and legal overhang.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com