


MMG (SEHK:1208) is back in focus after the group increased its Rosebery Concentrate Sales Agreement caps, reflecting higher forecast production and current copper, gold and silver prices, which are feeding into larger contracted sales values.
Despite the latest Rosebery agreement lifting expectations for future concentrate sales, MMG’s share price has been under pressure in the very short term, declining 8.2% over the past day and edging down 1.6% over the week. This comes even as the 1 month share price return of 8.5% sits against a 1 year total shareholder return of 55.8% and a very large 3 year total shareholder return that is close to 3x, signalling longer term momentum that contrasts with the recent pullback.
Scan for other materials producers that are showing similar contract-driven momentum by reviewing the hand picked 29 top copper producer stocks.
The pullback after MMG’s Rosebery contract update could reflect investors cooling on sentiment rather than a change in the underlying business. Is the current share price aligning with the fundamentals or drifting away from them?
Most Popular Narrative: 23.1% Undervalued
On the most followed narrative, MMG’s fair value of HK$11.79 sits well above the last close at HK$9.07, which puts the recent pullback in a different light.
Ongoing production expansions including Las Bambas optimization, the ramp-up at Kinsevere, and the multi-year capacity expansion at Khoemacau (targeting 130kt by 2028) should drive meaningful volume growth and operating leverage, contributing to sustained top-line gains and improved margins.
Want to see how that expansion story feeds into revenue, earnings, and the discount rate used to reach HK$11.79? The narrative leans on a tight set of growth, margin, and valuation assumptions that materially lift estimated future cash flows. The interesting part is how those inputs line up with analyst forecasts and where they leave room for upside or disappointment.
Result: Fair Value of HK$11.79 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the MMG narrative can be knocked off course if Las Bambas faces fresh disruption, or if large capex projects run into delays or cost overruns.
Find out about the key risks to this MMG narrative.
Another View: MMG on Earnings Multiples
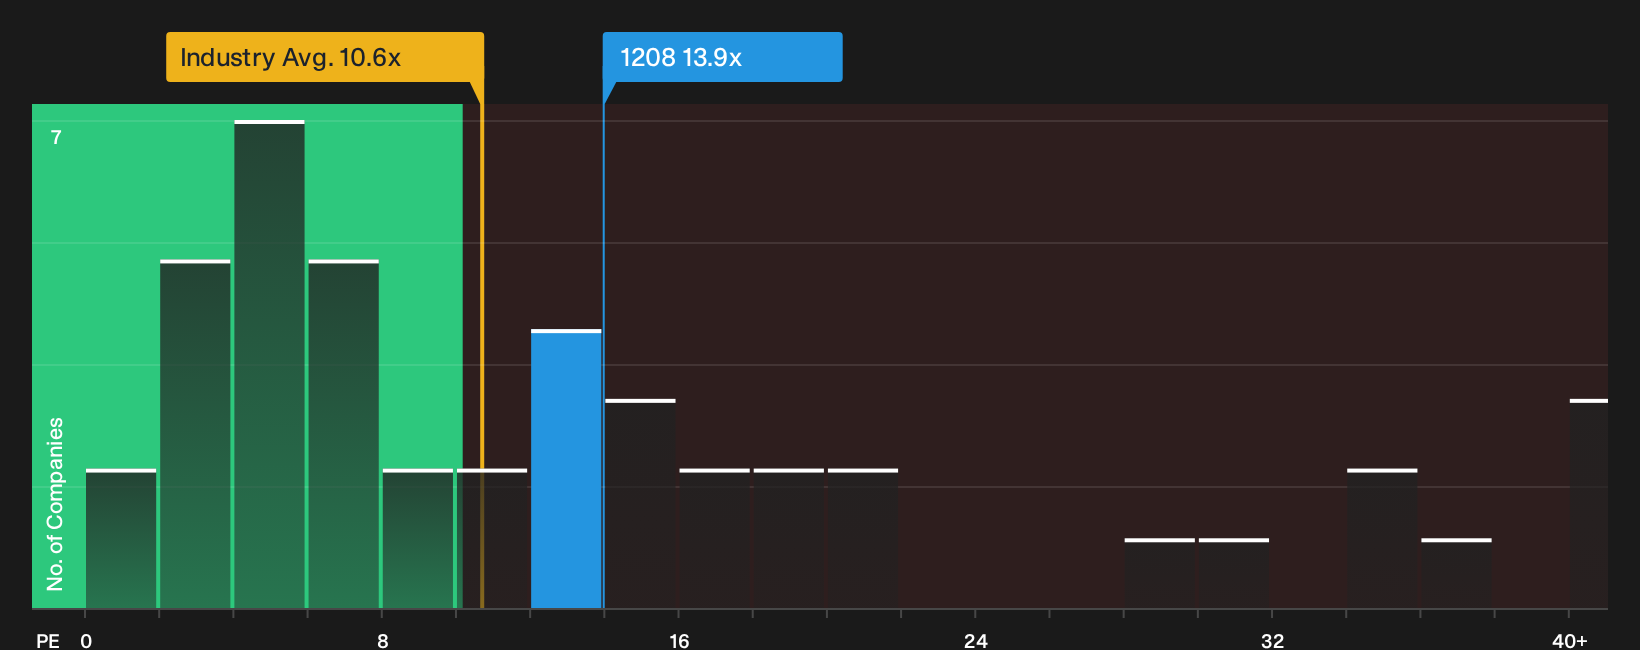
MMG looks inexpensive based on future cash flows, yet the picture shifts once you focus on earnings. The stock trades on a P/E of 13.9x, compared with 10.6x for the Hong Kong Metals and Mining industry and a fair ratio of 12.7x that the market could move toward.
This gap suggests investors are already paying a premium versus the sector and the fair ratio, even though MMG appears undervalued on the HK$18.08 future cash flow value. Which lens do you place more weight on when the market eventually chooses a side?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in this MMG story is mixed, with valuation and earnings sending different signals, so it helps to move fast and test the numbers yourself. To see which potential advantages analysts are most optimistic about, review the 4 key rewards.
Looking for more MMG investment ideas beyond this story?
Do not stop with MMG alone. Use the Simply Wall St screener to quickly surface fresh opportunities that match the kind of trade off you are comfortable with.
- Target potential mispricings by scanning a curated set of companies that currently screen as 185 high quality undervalued stocks.
- Prioritise resilience by filtering for businesses that pass tough balance sheet checks with our list of solid balance sheet and fundamentals (195 results).
- Hunt for less crowded opportunities by reviewing a focused pool of 620 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com