


CleanSpark has delivered a very strong 3 year run for shareholders, yet current valuation checks flag the stock as expensive rather than a clear bargain. For investors trying to weigh recent momentum against price, the numbers point to a company with powerful historical returns but a low value score and an overvalued market multiple profile.
- CleanSpark has returned about 209.3% over the past 3 years, which puts recent enthusiasm firmly on the side of existing shareholders.
- Fresh ERCOT power classifications in Texas and a long lease on a large Georgia data center campus can support expectations for expanded Bitcoin mining capacity, while the capital intensity and power market exposure may keep future cash flows volatile and hard to price.
- The broader valuation checks give CleanSpark a low value score of 2, which points to a stock that currently leans expensive rather than obviously mispriced.
The issue now is whether CleanSpark's share price already reflects these expansion plans and past gains, or if the current valuation still leaves room for investors to be rewarded over time.
Spot 21 cryptocurrency and blockchain stocks that combine large scale Bitcoin infrastructure stories like CleanSpark with balance sheets and business models you can actually benchmark.Has CleanSpark Run Too Far on Sales?
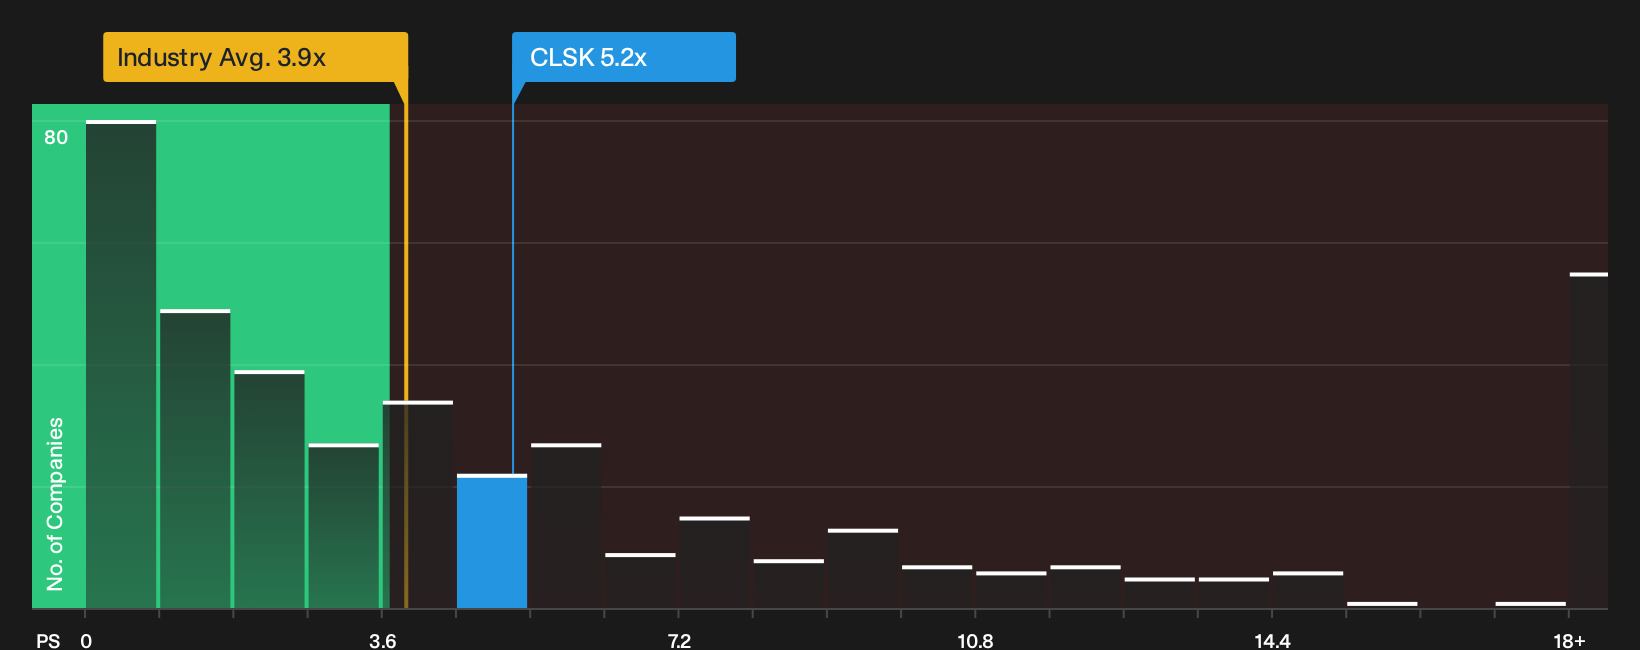
P/S is a useful lens for CleanSpark because the business is still leaning on revenue scale rather than consistent profits to justify its market value. On this metric, the stock trades at about 5.2x sales, compared with an industry average of roughly 3.9x and a peer group around 6.7x. That leaves CleanSpark priced at a premium to the broader software sector, yet at a discount to closer peers that investors often use as a comparison set for Bitcoin infrastructure plays.
The valuation model that blends factors like growth profile, margins, size and risk suggests a fair P/S ratio closer to 2.6x, which is well below where CleanSpark changes hands today. Despite the recent ERCOT power approvals and long Georgia data center lease lifting interest in the story, the share price already embeds a rich revenue multiple relative to this tailored fair ratio.
On the preferred P/S yardstick, CleanSpark stock currently screens as overvalued.
See what the numbers say about this price — find out in our valuation breakdown.
The CleanSpark Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for CleanSpark leaves off by spelling out which paths for growth, profitability and earnings would need to unfold for the current share price to look high or low. Each narrative ties its valuation anchor to a clear view on how CleanSpark's growth profile, margin structure and risk mix might evolve. This gives you a reference point you can return to as fresh information appears.
One of the top community narratives on CleanSpark: 43% undervalued
"CleanSpark's fully self-operated, scalable, and power-efficient infrastructure enables it to mine Bitcoin at a significantly lower cost than the market price..."
Read one of the top narratives on CleanSpark
Do you think there's more to the story for CleanSpark? Head over to our Community to see what others are saying!
The Bottom Line
CleanSpark now looks overvalued on the preferred market-multiple lens, so the easy part of the story is probably behind it rather than ahead. Broader valuation checks also skew weak, which means the current price already leans heavily on optimistic assumptions about future execution and Bitcoin mining economics. The key question from here is simple. Either the business grows into this richer revenue multiple, or the market eventually re-sets expectations if that progress does not materialise.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com