


Alcoa stock has delivered a strong 73.0% gain over the past three years, yet current valuation checks, including an intrinsic value estimate from a Discounted Cash Flow (DCF) approach and market multiples, both point to the shares trading below those modeled levels. Recent weakness in the price and the newly priced senior notes to fund the South32 acquisition put the focus squarely on whether that apparent discount is justified.
- Alcoa has returned 73.0% over three years, which suggests long term holders have already seen substantial gains even as the latest stretch has been choppier.
- The planned South32 asset acquisition, financed in part through US$2.6b of senior notes, can support future cash flow scale but also adds leverage that investors will watch closely.
- Across multiple methods, including the Discounted Cash Flow (DCF) intrinsic value estimate and valuation multiples, Alcoa screens as undervalued and the broader checks show a mixed picture rather than a clear bargain or clear overvaluation, with a value score of 4.0.
For investors, the debate is whether Alcoa’s current discount to intrinsic value and multiples offers enough compensation for the added balance sheet and execution risks tied to its expansion plans.
Scan beyond Alcoa and surface other potentially mispriced operators with solid fundamentals using the 31 high quality undervalued stocks that filters for quality first, then valuation.
Does Alcoa Look Undervalued on Cash Flow?
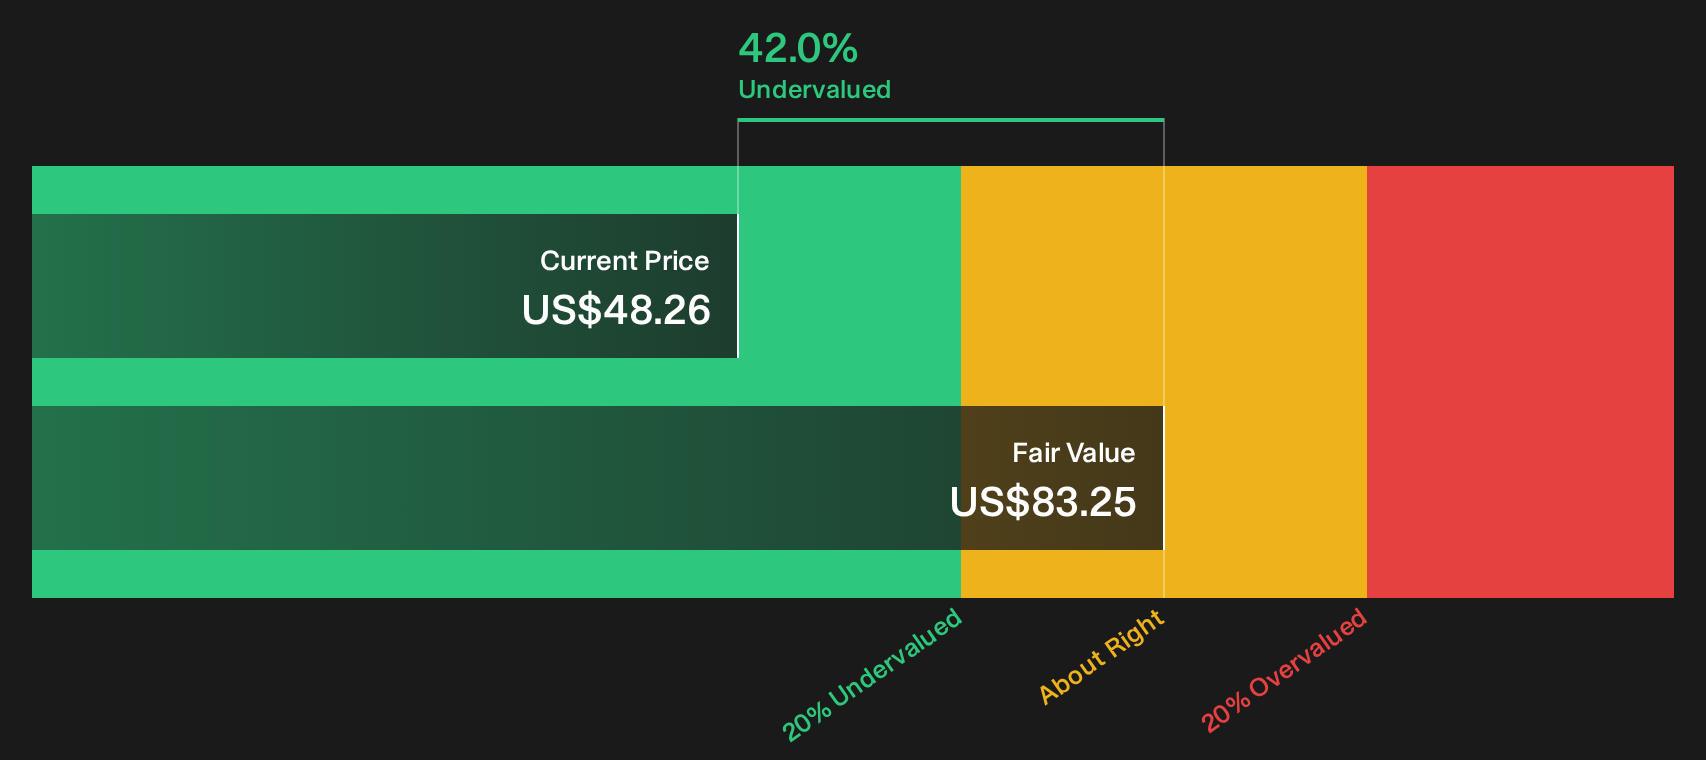
The Discounted Cash Flow (DCF) model here uses projected free cash flows to estimate what Alcoa might be worth based on its own cash generation. On the latest twelve month numbers, Alcoa produced free cash flow of about $377 million, with the model assuming that cash generation grows from this base rather than shrinking. Those projections translate into an estimated intrinsic value of about $83 per share.
Compared with the current share price, that intrinsic value implies the stock is about 42% undervalued. The recent decision to issue $2.6b of senior notes to fund the South32 asset acquisition helps explain why the market is hesitating, because higher leverage can weigh on sentiment even when modeled cash flows support a higher value.
Overall, the DCF work suggests Alcoa screens as undervalued relative to what its projected cash flows and intrinsic value imply.
Our Discounted Cash Flow (DCF) analysis suggests Alcoa is undervalued by 42.0%. Track this in your watchlist or portfolio, or discover 31 more high quality undervalued stocks.
Does Alcoa Look Undervalued on Earnings?
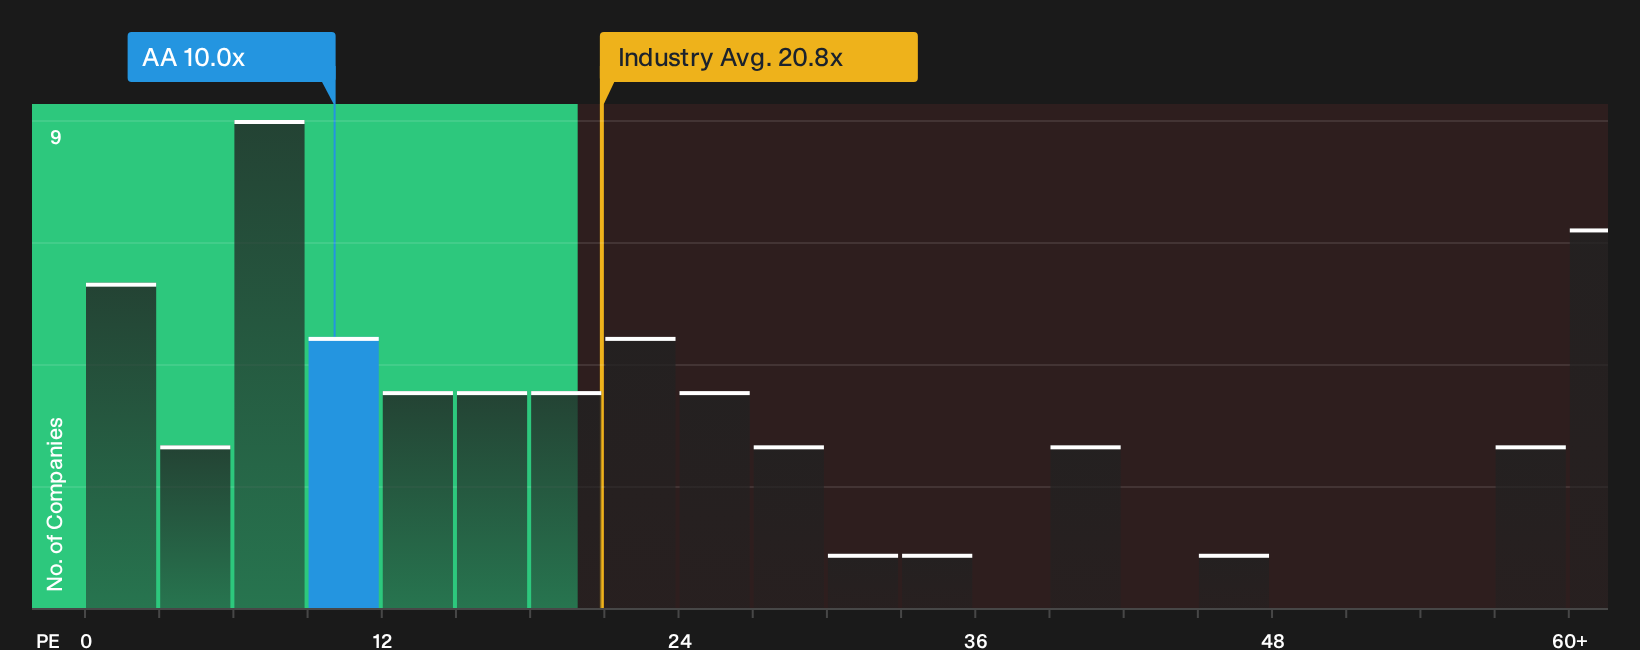
P/E is a useful lens for Alcoa because earnings drive how investors usually think about mature metals and mining businesses. On this measure, Alcoa trades on about 10.0x earnings, which is above the 8.1x peer average but well below the broader Metals and Mining industry on roughly 20.8x. The stock is not the cheapest in its direct comparison set, yet it also does not carry the richer sector level pricing that some larger diversified groups command.
The fair P/E ratio for Alcoa, based on its characteristics, comes out at about 18.7x. That is a sizable gap to the current 10.0x multiple and suggests the market is pricing in a higher level of risk or cyclicality than this framework assumes. If earnings hold anywhere close to the base that underpins this model, the current P/E leaves room for a more generous valuation than the one implied by today's quote.
On the P/E multiple alone, Alcoa appears undervalued relative to what this framework suggests investors might usually pay for its earnings profile.
See what the numbers say about this price — find out in our valuation breakdown.
The Alcoa Narrative: What Would Justify Today's Price?
Narratives for Alcoa sit between the valuation work above and the real world that will either support or challenge it, by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth far more or much less than today’s price. Rather than relying on a single model output, each Narrative lays out its own fair value assumptions so you can track those against Alcoa’s actual results as they arrive. These sit on Simply Wall St's Community page.
One of the top community narratives on Alcoa: roughly fairly valued
"Gradual deglobalization and increasing trade protectionism exemplified by sharply higher Section 232 tariffs and the risk of additional U.S. import restrictions from Brazil are structurally fragmenting aluminum markets..."
Read one of the top narratives on Alcoa
Do you think there's more to the story for Alcoa? Head over to our Community to see what others are saying!
The Bottom Line
Alcoa screens as undervalued on both the Discounted Cash Flow (DCF) intrinsic value work and on earnings multiples, which points to a genuine pricing gap rather than a quirk of one model. That said, the mixed overall value checks and the added leverage from the South32 financing keep this from being a simple mispricing story. What really matters from here is whether cash flows from the enlarged asset base prove resilient enough to make that balance sheet stretch look conservative rather than optimistic. The key debate is whether the current discount compensates you for that execution and funding risk, or whether it is the market already pricing it in accurately.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com