


Meliá Hotels International (BME:MEL) has drawn fresh attention after its recent share performance, with the stock down over the past month and past 3 months while still showing positive multi year total returns.
For context, the share price has slipped over the past week and quarter, with the 7 day share price return down 2.68% and the 90 day share price return down 15.37%. However, Meliá Hotels International still shows a 23.82% year to date share price gain and a 24.73% total shareholder return over the past year. This points to cooling short term momentum after a stronger run over a longer horizon.
Compare Meliá Hotels International's recent pullback with other potential rebound candidates by scanning our hand picked 185 high quality undervalued stocks, which pairs quality fundamentals with compressed valuations.
Bulls see Meliá Hotels International as a quality hotel group coming off a strong multi year run, while bears point to recent share price weakness and valuation risk. Which side do the numbers support as you weigh the current pricing?
Most Popular Narrative: 11.6% Undervalued
Meliá Hotels International most followed narrative estimates fair value at €11.08 per share, compared with the current €9.80 price. This frames a modest valuation gap that hinges on execution of its long term plan.
Meliá's strategic expansion in high-growth regions (such as Southeast Asia, the Caribbean, and continued penetration in Europe) and a strong pipeline of 35+ new hotels annually under an asset-light model is expected to drive higher revenue while improving net margins through lower capital intensity and fee-based income streams.
Want to see what sits behind that expansion story? The narrative leans on measured top line growth, a small uplift in profitability, and a richer earnings multiple. Curious how those moving parts combine into a single fair value number.
Result: Fair Value of €11.08 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, that narrative leans heavily on smooth execution of Meliá Hotels International's asset light rollout and on avoiding prolonged pressure from higher wage costs in key resort regions.
Find out about the key risks to this Meliá Hotels International narrative.
Another View on Meliá Hotels International’s Valuation
The narrative model points to Meliá Hotels International trading about 11.6% below its fair value, yet a different lens tells a tighter story. Our DCF model estimates future cash flows at roughly €8.44 per share, compared with the current €9.80 price, which screens as overvalued on that basis. Which framework feels more realistic to you when you plug in your own assumptions?
Look into how the SWS DCF model arrives at its fair value.
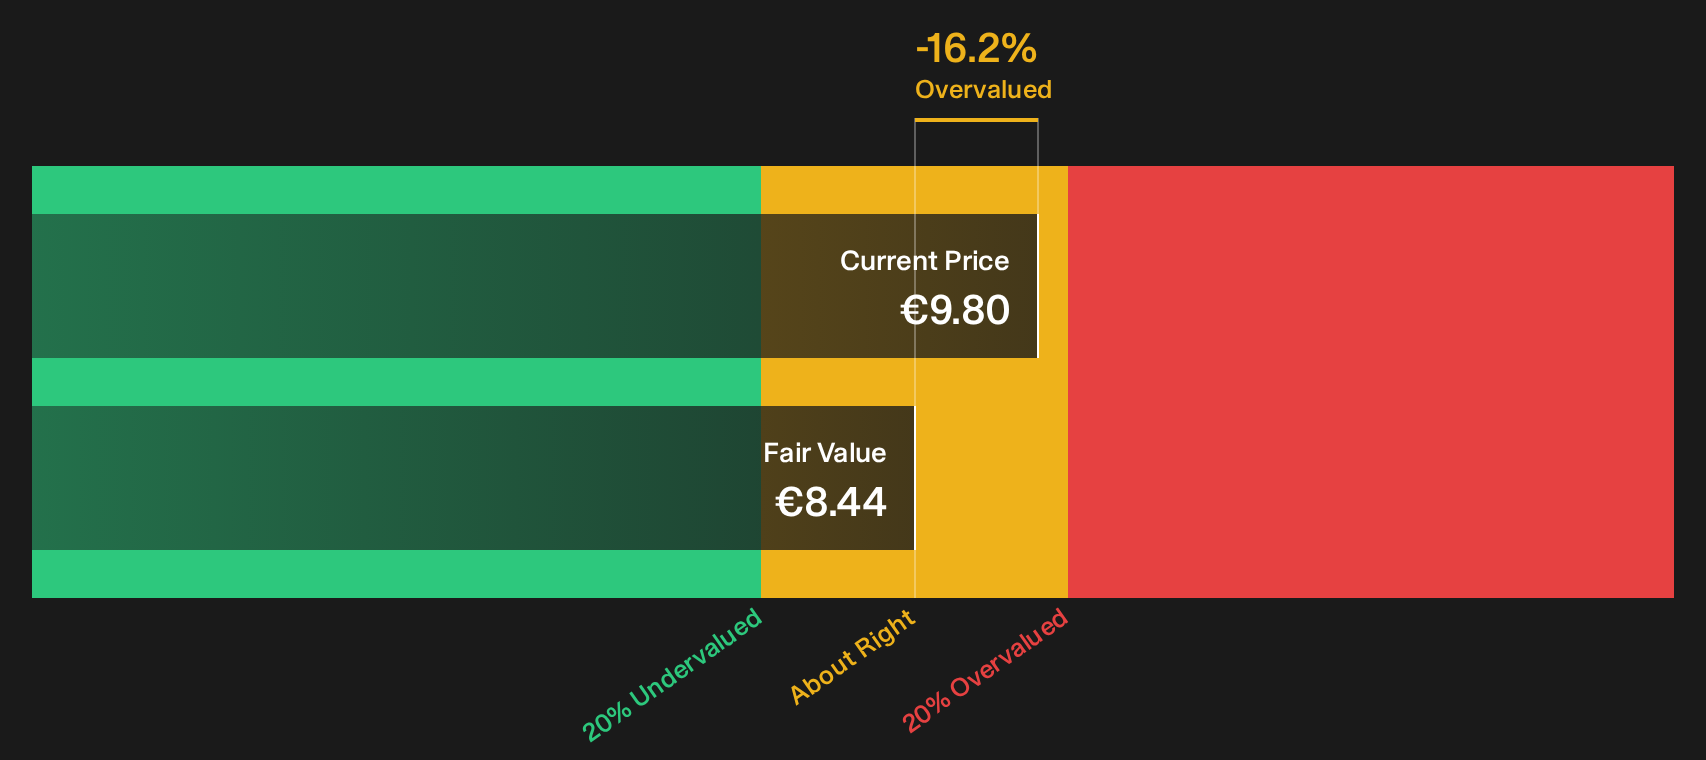
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Meliá Hotels International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 185 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Meliá Hotels International so far. Act while the data is fresh and form your own view by weighing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Meliá Hotels International?
If Meliá Hotels International has your attention, do not stop there. Use the Simply Wall Street Screener to uncover fresh opportunities that might fit your strategy.
- Target potential mispricings by scanning companies that combine strong fundamentals with compressed valuations through the 185 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that feature resilient cash flows and higher yields inside the 164 dividend fortresses.
- Broaden your opportunity set by checking quality stocks that remain off most radars using the 620 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com