


Why Roblox Wallet Matters For Roblox Investors
Roblox (RBLX) is rolling out Roblox Wallet, a new payments product that lets adult creators in the US receive real world revenue automatically on every business day and transfer funds directly to bank accounts.
Recent trading shows short term momentum building for Roblox, with a 1 day share price return of 1.38%, a 7 day gain of 5.06% and a 30 day rise of 19.02%, even though the year to date share price return is down 43.79% and the 1 year total shareholder return has declined 65.87%. The 3 year total shareholder return remains positive at 63.02%.
Scan for other Roblox style plays where user engagement, creator tools and monetization are central by zeroing in on our hand picked 74 profitable AI stocks that aren't just burning cash.
Roblox is building a powerful creator ecosystem, yet the stock is still working through a sharp drawdown despite the recent bounce. Is this renewed enthusiasm offering a fair entry point, or is it already baking in the promise?
Most Popular Narrative: 112% Overvalued
The latest narrative fair value for Roblox sits at $21.48, well below the recent $45.50 close, which creates a wide gap for investors to assess.
A realistic case is not $95. It is probably closer to $55 to $70, with the real center of gravity around $60 to $65.
The stock can work from here, but the investment case should be built around FCF growth and dilution control, not a heroic 139x P/E on 2029 earnings.
This narrative leans heavily on fast revenue expansion, a specific path for free cash flow, and a defined profit margin ramp by 2029. Curious which assumptions really move that valuation range.
According to ACV, the story hinges on Roblox converting strong top-line growth into rising free cash flow while keeping share count roughly flat through buybacks. The fair value of $21.48 in the same framework implies a material discount once a consistent discount rate, long term margin profile, and terminal expectations are applied across the full DCF style model.
The narrative also contrasts a more restrained path against an aggressive bull scenario. It pairs mid-teens annual revenue growth and gradual margin improvement with a premium multiple on future cash flows, and then stresses that execution on bookings, older user monetization, and cost discipline would be the key drivers that justify any valuation well above today's quoted fair value.
Result: Fair Value of $21.48 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Roblox faces real pressure if safety costs stay elevated or DevEx payouts absorb more economics, which could restrict the free cash flow story investors are watching.
Find out about the key risks to this Roblox narrative.
Another View On Roblox Valuation
The narrative model pegs Roblox at a fair value of $21.48, which suggests the current $45.50 price looks stretched. The SWS DCF model, using projected future cash flows, instead flags the stock as trading about 38.9% below an estimated value of $74.43. That is a wide gap for any investor to reconcile, so which story do you trust more, the narrative or the cash flow math?
Look into how the SWS DCF model arrives at its fair value.
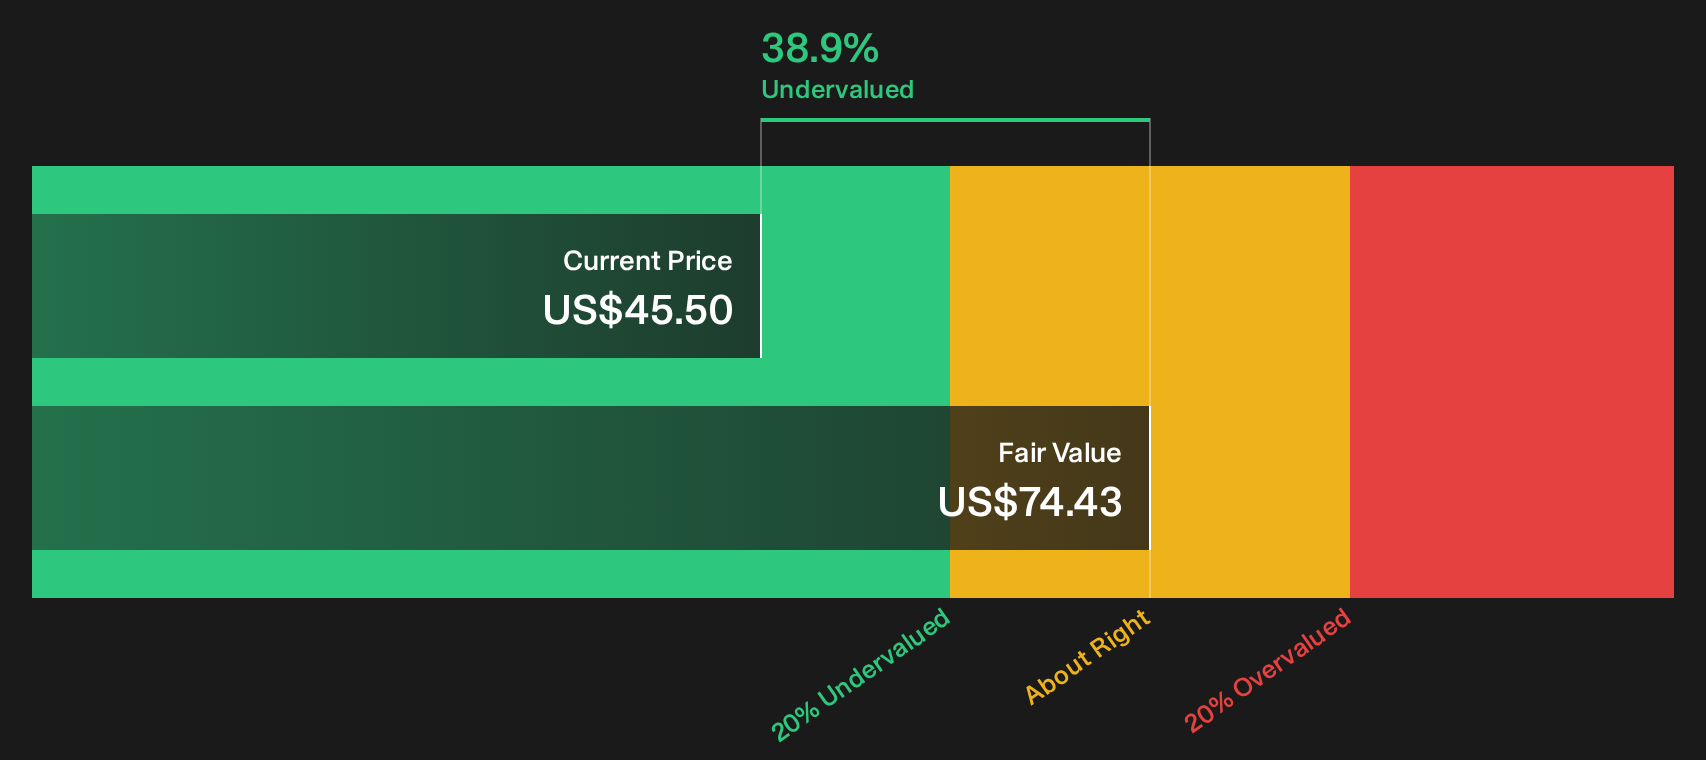
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Roblox for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty of excitement runs through this Roblox story, yet the data also flags real trade offs you should weigh on your own terms. If you want a concise view of both sides, start with the 2 key rewards and 3 important warning signs.
Looking for more Roblox style investment ideas?
Roblox might be your focus today, but the next market leader could already be lining up on your radar if you cast the net a bit wider.
Explore new angles, pressure test your thesis, and give yourself options before the crowd catches on.
- Focus on potential upside with companies that combine quality fundamentals and attractive pricing by zeroing in on our hand picked 32 high quality undervalued stocks.
- Balance your risk by filtering for businesses with steadier profiles and resilient risk scores through the focused 11 resilient stocks with low risk scores.
- Search for lesser known opportunities with strong financial traits using the curated 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com