


J. M. Smucker (SJM) has drawn fresh attention after recent share moves, with the price closing at US$121.14. Investors are weighing that valuation against mixed return figures and modest value scoring.
The recent pullback, including a 7 day share price return of down 3.9% after a strong year to date gain of 25.4%, suggests momentum in J. M. Smucker is cooling at the margin, even as the 1 year total shareholder return of 17.0% reflects a still constructive longer term picture.
Compare J. M. Smucker's recent swing in momentum with a curated set of other potential value opportunities by scanning the 32 high quality undervalued stocks that share solid fundamentals and discounted prices.
For J. M. Smucker, that mix of a cooler week and a solid year so far invites a sharper question. Are you seeing business fundamentals evolve, or sentiment simply resetting at this price tag before looking at valuation?
Most Popular Narrative: 3% Undervalued
Against J. M. Smucker's last close at $121.14, the most followed narrative pegs fair value near $124.88, framing today’s share price as modestly below that mark while leaning on a detailed set of earnings and margin assumptions.
Analysts expect earnings to reach $979.6 million (and earnings per share of $9.46) by about August 2029, up from -$138.7 million today. In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 16.7x on those 2029 earnings, up from -91.9x today. This future PE is about the same as the current PE for the US Food industry at 16.7x.
Curious what sits behind that shift from current earnings to those future profit levels? The narrative leans heavily on margin repair, steady revenue, and a valuation multiple that assumes investors stay comfortable with J. M. Smucker's long term earnings profile.
Result: Fair Value of $124.88 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the J. M. Smucker narrative relies on smoother coffee input costs and a clean Hostess integration, and any setback there could quickly challenge those margin assumptions.
Find out about the key risks to this J. M. Smucker narrative.
Another View: J. M. Smucker On Earnings Multiples
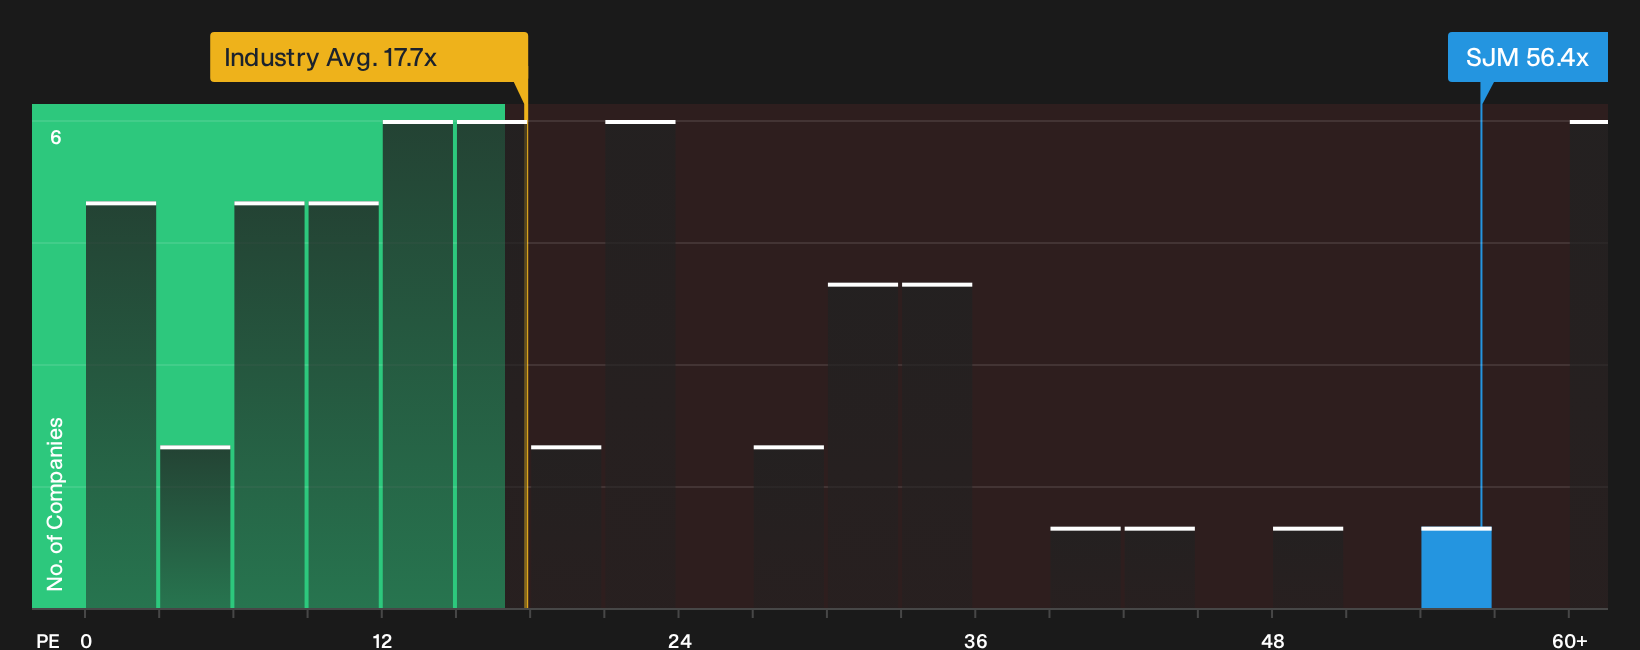
The SWS DCF model sees J. M. Smucker as trading at a large discount to an estimated future cash flow value of $268.06. At the same time, the current P/E of 56.4x is far above both the US Food sector at 17.7x and a fair ratio of 25.7x. Is the gap a mispricing or a warning on expectations?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this J. M. Smucker story points both ways, with flagged risks on one side and encouraging strengths on the other. Move quickly and test the data for yourself by weighing the 3 key rewards and 4 important warning signs.
Looking for more ideas beyond J. M. Smucker?
If J. M. Smucker has you rethinking your watchlist, use this moment to broaden your opportunity set before the next move happens without you.
- Target resilient income by reviewing the 6 dividend fortresses that could help anchor your returns when growth stories wobble.
- Hunt for quality at a discount through the 15 high quality undiscovered gems that the wider market may not be paying close attention to yet.
- Prioritise capital preservation by scanning the 11 resilient stocks with low risk scores that score well on fundamentals while keeping volatility in check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com