


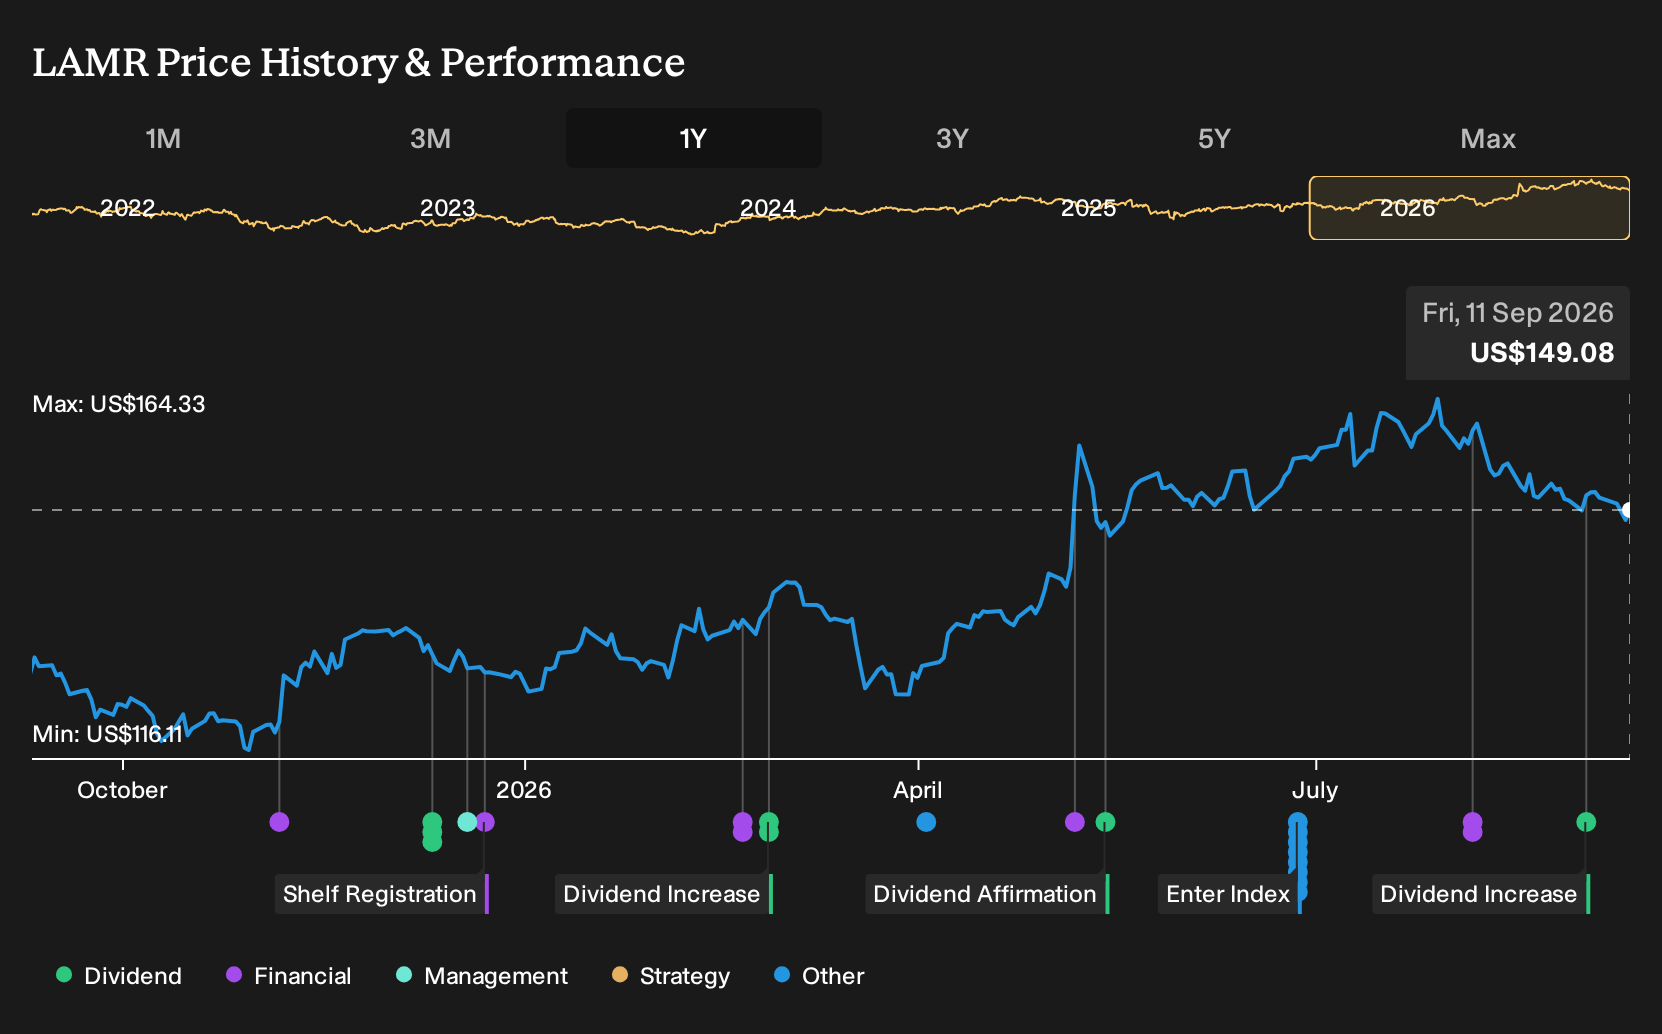
- Lamar Advertising announced that its board has declared a quarterly cash dividend of $1.65 per share, to be paid on September 30, 2026, to holders of both Class A and Class B common stock, with total 2026 distributions expected to reach at least $6.50 per share, subject to board approval.
- The higher stated dividend level highlights management’s focus on returning cash to shareholders and relies on Lamar Advertising sustaining the cash generation needed to fund both these payouts and its capital spending on digital assets and acquisitions.
- We will now look at how this higher quarterly dividend commitment could influence Lamar Advertising’s broader investment narrative for shareholders.
Lamar Advertising Investment Narrative Recap
Lamar Advertising appeals to you if you believe in steady out of home demand, continued take up of digital billboards and disciplined use of acquisitions. The bigger near term swing factor is whether advertiser budgets support the existing guidance after a softer patch in some categories and contract churn such as the Vancouver transit loss. The higher dividend guidance itself does not change that operating backdrop in a material way.
The main risk investors keep focusing on is leverage and the reliance on external borrowing, especially as the firm pursues digital expansion and M&A. A richer dividend run rate raises the bar on consistent cash generation but does not fundamentally alter the core thesis. That thesis hinges on execution in digital, programmatic and local markets while keeping debt at a level that feels manageable.
The fresh quarterly dividend declaration of US$1.65 per share, with 2026 distributions expected to reach at least US$6.50 per share, ties directly into those operating priorities. It effectively indicates that management plans to support a sizeable cash outlay while still funding digital additions, airport and logo projects and potential acquisitions enabled by the UPREIT structure.
For you as a shareholder, a useful question is whether Lamar Advertising can keep AFFO growing enough to cover that payout while dealing with slower revenue forecasts than the broader US market and contract renewal risk. If digital board performance, programmatic sales and local and regional demand hold up against those pressures, the announced dividend path could sit comfortably alongside the existing catalysts rather than compete with them.
Lamar Advertising Earnings And Revenue Assumptions
Lamar Advertising's narrative projects US$2.6b revenue and US$764.5 million earnings by 2029. This rests on analysts using a 4.3% yearly revenue growth rate and an earnings increase of about US$209 million from US$555.7 million today.
Uncover why Lamar Advertising's fair value indicates a 9% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between US$162 and about US$233 per share, which shows how far apart private investors can be on Lamar Advertising before the latest dividend news. Compare those valuation gaps with the risks around softer guidance and contract churn, then explore alternative viewpoints before relying on any single narrative.
Explore another Lamar Advertising fair value estimate, including one that suggests potential upside of as much as 57% from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Lamar Advertising research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Lamar Advertising. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lamar Advertising's overall financial health at a glance.
Looking For More Ideas Beyond Lamar Advertising?
Once you have a handle on Lamar Advertising, it can help to line it up against other businesses with different risk and income profiles using the Simply Wall St Screener.
- For investors who want resilient balance sheets to anchor a portfolio, review our list of solid balance sheet and fundamentals (23 results) that pair financial strength with fundamental support.
- If value is your priority and you prefer to focus on quality businesses trading at what may be undemanding prices, scan our curated 32 high quality undervalued stocks for potential candidates.
- For income seekers who want a broader menu of payout options than Lamar Advertising alone can offer, shortlist ideas using our hand picked 6 dividend fortresses tailored to varied dividend goals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com