


Amidst geopolitical tensions and fluctuating oil prices, Asian markets have experienced a period of volatility, reflecting broader global economic uncertainties. In such an environment, growth companies with high insider ownership can be appealing as they often indicate strong confidence from those who know the business best.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 75.5% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 116.3% |
| SEERS (KOSDAQ:A458870) | 33.8% | 35.7% |
| Ningbo Sanxing Medical ElectricLtd (SHSE:601567) | 24.9% | 56.8% |
| L&C BIOLTD (KOSDAQ:A290650) | 20.9% | 163% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| HUMAN MADE (TSE:456A) | 23.9% | 28.8% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Let's dive into some prime choices out of the screener.
Shenzhen Megmeet Electrical (SZSE:002851)
Simply Wall St Growth Rating: ★★★★★★
Overview: Shenzhen Megmeet Electrical Co., LTD operates as an electrical automation company in China with a market cap of CN¥73.11 billion.
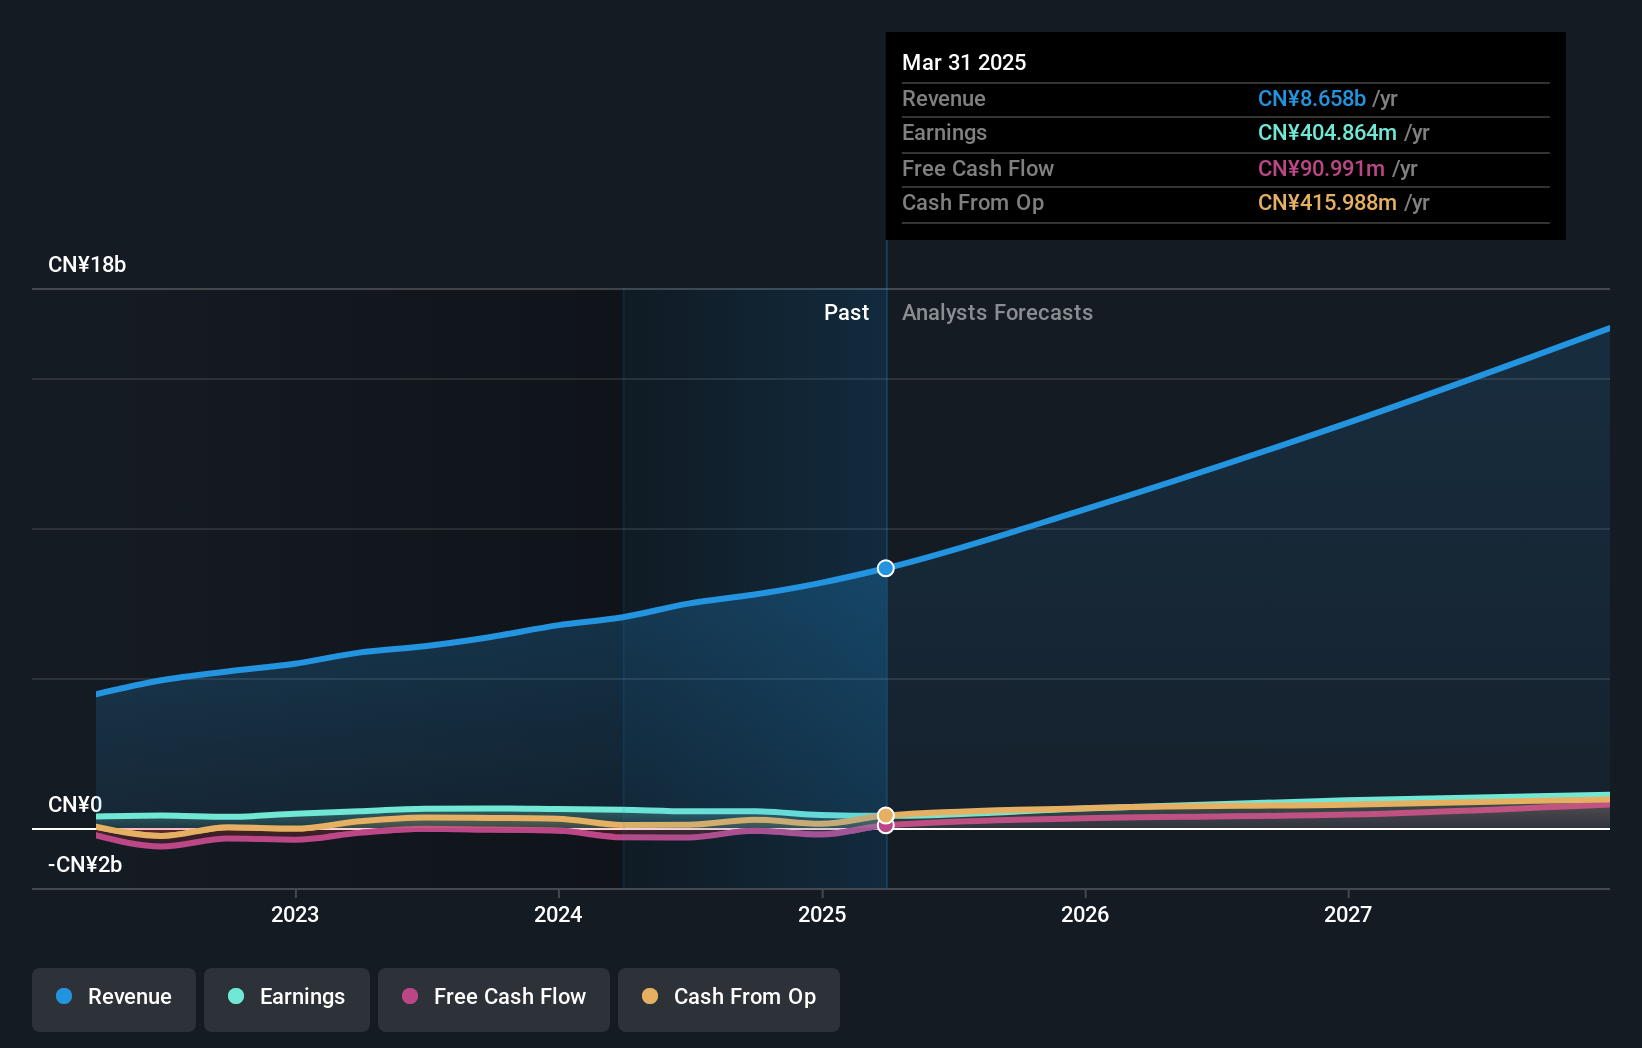
Operations: The company's revenue segments include Smart Equipment (CN¥647.10 million), Industrial Automation (CN¥938.41 million), Industrial Power Products (CN¥3.38 billion), New Energy Transportation (CN¥1.20 billion), Selected Magnetoelectric Materials (CN¥546.86 million), and Smart Home Appliances Electronic Control Products (CN¥3.99 billion).
Insider Ownership: 30.5%
Revenue Growth Forecast: 32.4% p.a.
Shenzhen Megmeet Electrical shows strong growth potential with earnings and revenue forecasted to grow significantly faster than the Chinese market. Recent earnings results highlight substantial sales and revenue increases, though profit margins have declined slightly. Despite high volatility in share price, the stock trades below its estimated fair value. Insider ownership remains stable without recent significant buying or selling activity. The company's return on equity is expected to remain robust over the coming years.
- Delve into the full analysis future growth report here for a deeper understanding of Shenzhen Megmeet Electrical.
- In light of our recent valuation report, it seems possible that Shenzhen Megmeet Electrical is trading beyond its estimated value.
Konfoong Materials International (SZSE:300666)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Konfoong Materials International Co., Ltd. (SZSE:300666) is engaged in the production and sale of high-purity metal materials, with a market cap of CN¥63.37 billion.
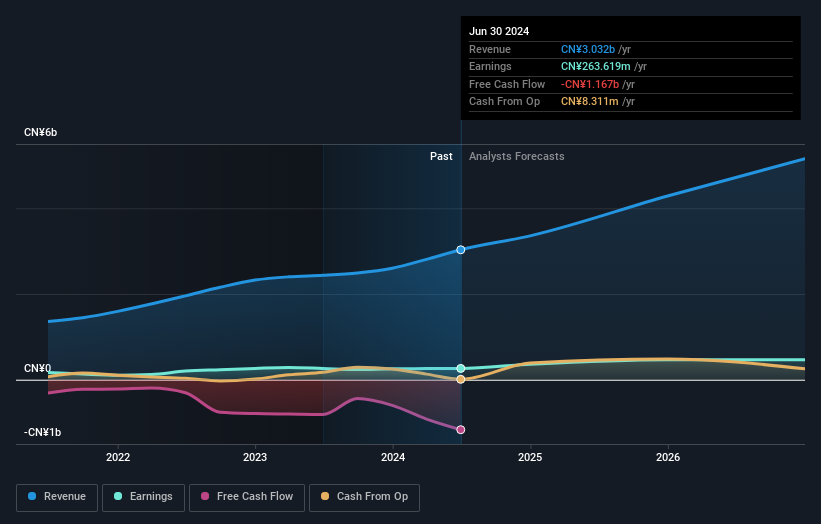
Operations: The company generates revenue of CN¥5.25 billion from its Computer, Communications, and other Electronic Equipment Manufacturing segment.
Insider Ownership: 23.1%
Revenue Growth Forecast: 19.4% p.a.
Konfoong Materials International demonstrates strong growth prospects, with earnings forecasted to grow significantly at 24.78% annually, though slightly below the Chinese market average. Recent half-year results show substantial revenue and net income increases, indicating robust operational performance. Despite high share price volatility and a Price-To-Earnings ratio of 80.6x below the industry average, insider ownership remains stable without recent significant buying or selling activity. The company's return on equity is projected to be high in three years.
- Navigate through the intricacies of Konfoong Materials International with our comprehensive analyst estimates report here.
- Our valuation report unveils the possibility Konfoong Materials International's shares may be trading at a premium.
Kinik (TWSE:1560)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Kinik Company manufactures and distributes a range of abrasives, cutting tools, and reclaimed wafers in Taiwan and globally, with a market capitalization of approximately NT$118.73 billion.
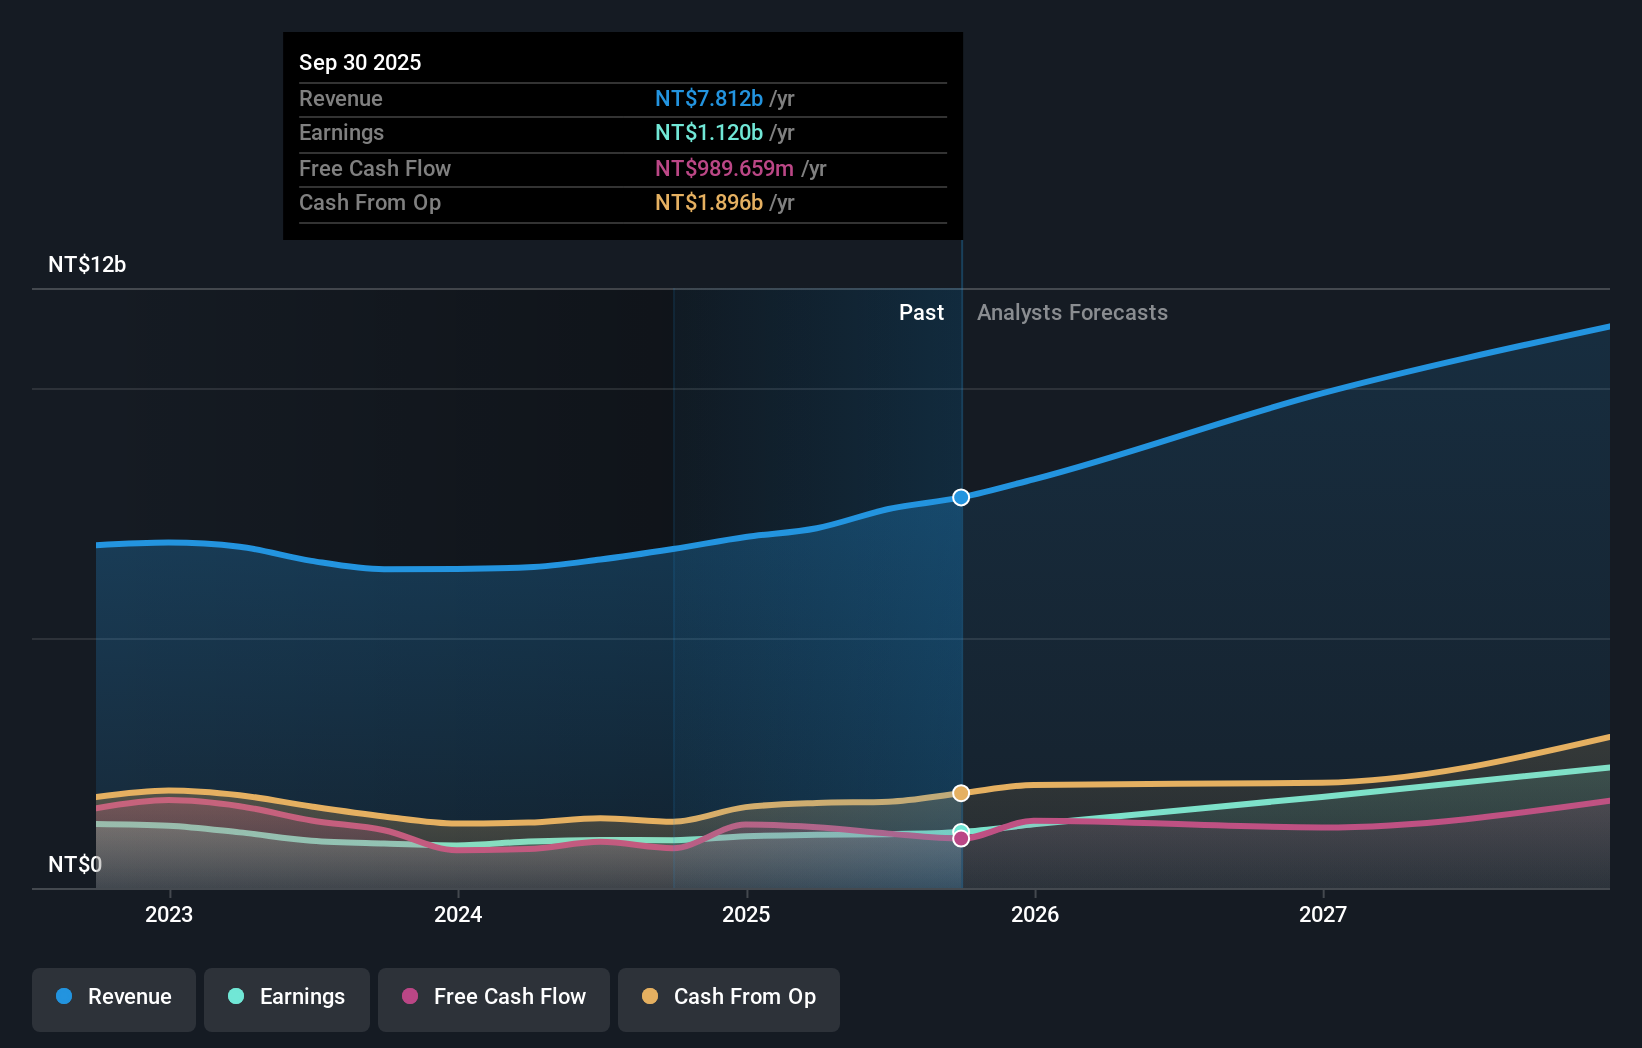
Operations: The company's revenue is derived from two main segments: the Electronics Sector, contributing NT$4.03 billion, and the Traditional Sectors, accounting for NT$5.02 billion.
Insider Ownership: 15.5%
Revenue Growth Forecast: 20.4% p.a.
Kinik's earnings are forecast to grow significantly at 30.4% annually, outpacing the Taiwan market average, though revenue growth slightly lags behind. Recent results show substantial revenue and net income increases, with Q2 sales reaching TWD 2.49 billion and net income of TWD 523.38 million. Despite high share price volatility, insider ownership remains stable without significant recent trading activity. Kinik's return on equity is projected to be robust in three years at 28.2%.
- Take a closer look at Kinik's potential here in our earnings growth report.
- Our expertly prepared valuation report Kinik implies its share price may be too high.
Turning Ideas Into Actions
- Take a closer look at our Fast Growing Asian Companies With High Insider Ownership list of 497 companies by clicking here.
- Looking For Alternative Opportunities? This technology could replace computers: discover the 25 stocks are working to make quantum computing a reality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com