


Why Novozymes Stock Is Back in Focus After Novonesis’ Patalganga Expansion Plan
Novozymes (CPSE:NSIS B) is back on investor watch after Novonesis announced a €600 million expansion in Patalganga, aimed at lifting biosolutions capacity and reinforcing its global supply setup.
Set against a recent 12.45% 90 day share price return and a 7.97% 1 year total shareholder return, the latest Patalganga move lands as Novozymes’ short term momentum improves, while its longer run track record still shapes how investors weigh growth potential against risk.
Compare Novozymes’ capacity-driven story with other hand-picked compounders by scanning our 182 high quality undervalued stocks built around resilient cash flows and solid balance sheets.
That €600 million Patalganga project now sits against a 52.5% 3 year total return and a value score of just 2. Does Novozymes still offer enough upside potential to compensate you for the risks from here?
Most Popular Narrative: 13% Undervalued
At a last close of DKK427.30 against a most-followed fair value estimate of DKK491.93, the current Novozymes price sits below what that narrative framework considers reasonable, with analysts using a 5.72% discount rate to bring future cash flows back to today.
Structural growth in bioenergy from higher blend mandates, new second generation ethanol and biodiesel capacity in India, Latin America and Europe, and technology driven efficiency gains in existing plants should support high single digit growth in Agriculture, Energy & Tech and underpin cash flow and earnings expansion.
See why 5 investors see Novozymes as 13% undervalued.
Result: Fair Value of DKK491.93 (UNDERVALUED)
Still, currency pressure on euro reported earnings and the heavy capital spend behind Novozymes and Novonesis’ emerging market build out could both trip up that fair value story.
Find out about the key risks to this Novozymes narrative.
Another View On Novozymes’ Valuation
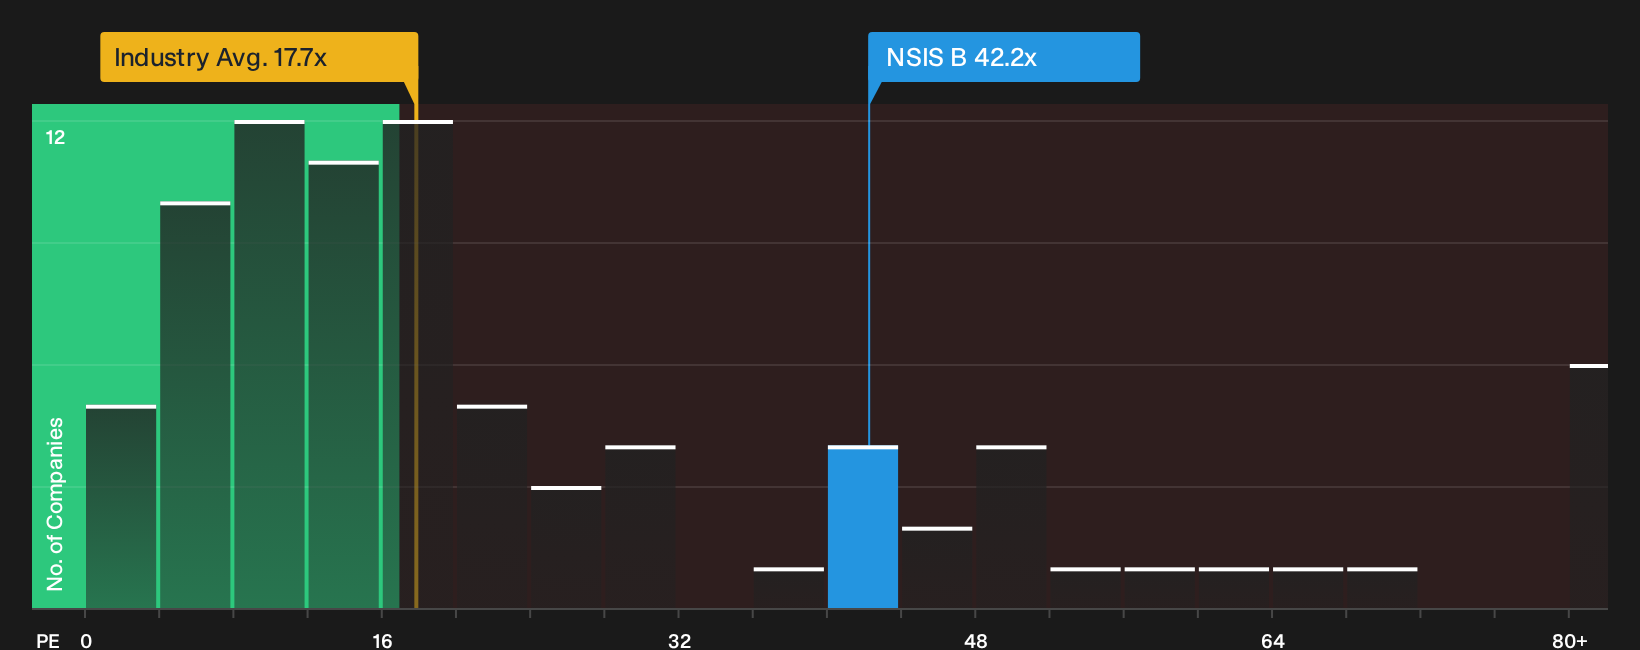
The cash flow story points one way, but the price tag tells another. On earnings, Novozymes trades on a P/E of 42.2x compared with 30.8x for peers and a fair ratio of 28.8x, which means investors are paying a clear premium. Is that gap justified for you, or is it valuation risk?
To see how that premium lines up against detailed valuation work, including where the ratio could drift over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Novozymes can be confusing, so take a moment to review the data, weigh the concerns and positives, and ground your own thesis in the 3 key rewards and 1 important warning sign.
Looking for more Novozymes style investment ideas?
If Novozymes has sharpened your thinking, do not stop with a single ticker. Broaden your watchlist now and give yourself more quality options.
- Hunt for quality at a discount by scanning our 182 high quality undervalued stocks before others price in the potential.
- Build a steadier income stream and stress test your dividend candidates using the 163 dividend fortresses while yields remain compelling.
- Prioritise resilience and capital preservation by filtering for financially robust businesses through the list of solid balance sheet and fundamentals (194 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com