


United Bankshares (UBSI) has drawn investor attention after recent trading left the share price at US$47.22, prompting fresh questions about how its valuation lines up with its longer term return record.
Recent trading has been softer, with the 1 month share price return down 4.16% and the 7 day move also lower. However, United Bankshares still shows a 90 day share price return of 4.82% and a 1 year total shareholder return of 31.76%, pointing to momentum that has cooled in the very short term after a stronger run over multi year periods, including a 3 year total shareholder return of 92.83%.
Compare United Bankshares' recent performance with other regional banks showing strong fundamentals and resilient returns using our hand picked list of solid balance sheet and fundamentals (23 results).
United Bankshares has cooled after a strong multi year run, which leaves a different question on the table. Does the current risk reward still tilt toward new buyers, or have most of the easy gains already been taken?
Preferred P/E of 12.5x for United Bankshares: Is it justified?
Valuation for United Bankshares right now leans on its P/E of 12.5x, which sits in a mixed zone that looks slightly expensive versus both its own fair ratio and the wider banks sector, even though the share price of $47.22 also screens as below some intrinsic estimates.
P/E is a simple yardstick. It compares what investors are currently paying for each dollar of earnings, which is especially closely watched for a bank like United Bankshares where profitability and credit quality shape the longer term picture.
United Bankshares trades on a 12.5x P/E. That is higher than the US Banks industry average of 11.9x, which suggests the market is assigning a premium to its earnings. At the same time, the fair P/E estimated from the SWS fair ratio framework sits lower at 11.2x, which points to a valuation level the market could move toward if sentiment cools or earnings do not keep up with expectations.
Explore the SWS fair ratio for United Bankshares.
Result: Price-to-Earnings of 12.5x (OVERVALUED)
Still, investors may want to monitor any shift in credit quality or reset in earnings expectations, as these factors could pull United Bankshares back toward its fair P/E.
Find out about the key risks to this United Bankshares narrative.
Another view on United Bankshares valuation
The SWS DCF model tells a different story for United Bankshares. On that approach, the current price of $47.22 sits around 28.3% below an estimated future cash flow value of $65.84, which frames the stock as undervalued rather than stretched.
Investors are left with a simple question: Does the higher P/E signal optimism that has run ahead of itself, or does the DCF gap suggest the market is still underpricing the bank's cash generation potential over time?
Look into how the SWS DCF model arrives at its fair value.
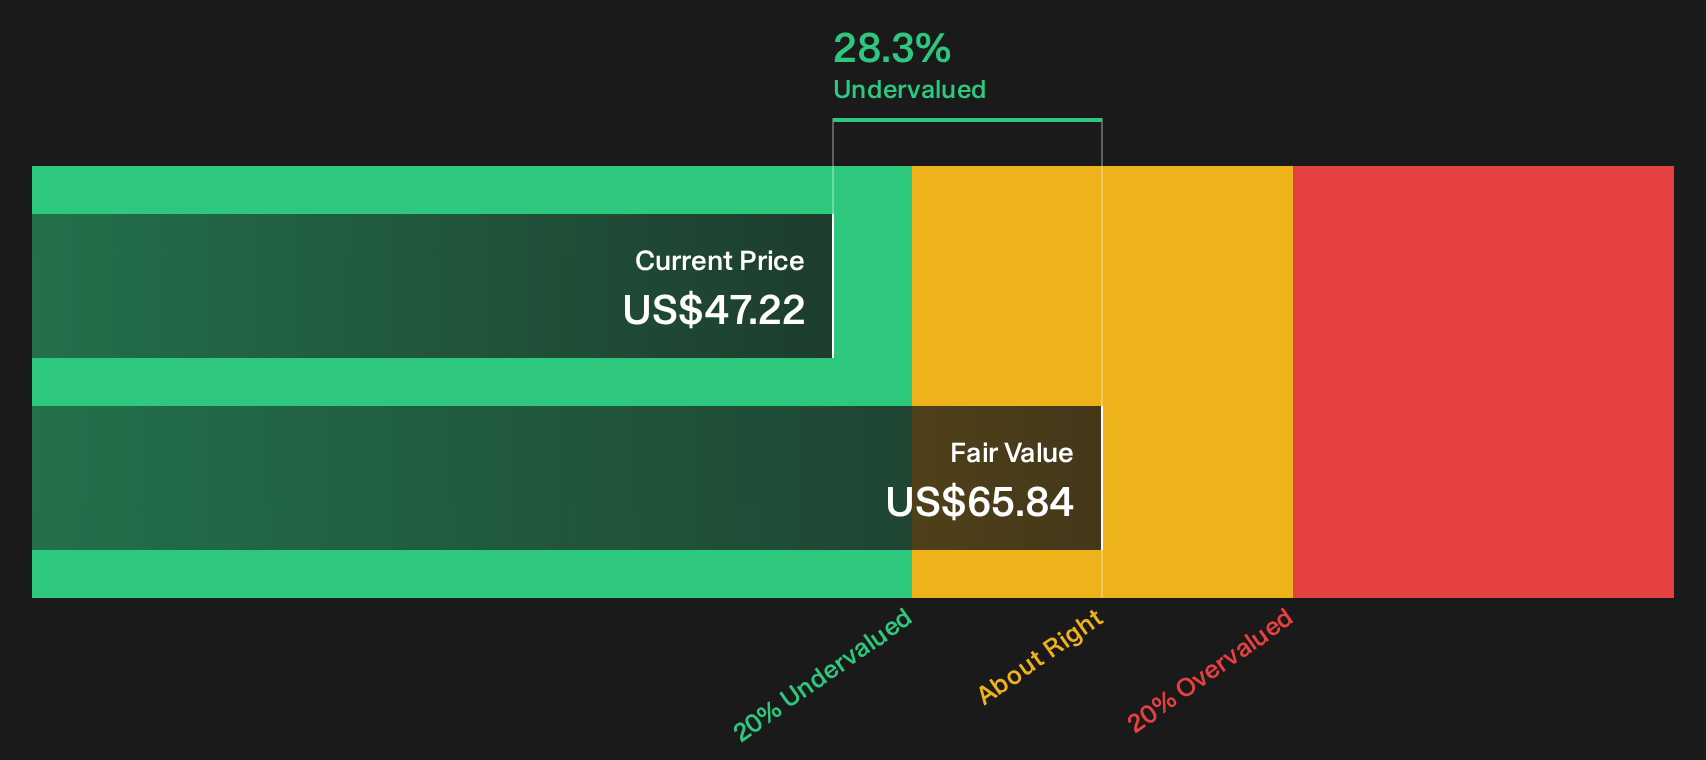
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out United Bankshares for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around United Bankshares may look mixed on the surface, yet the underlying data is clear enough for you to weigh up quickly and decide where you stand. To see what the optimism is anchored to, review the 3 key rewards
Looking for more United Bankshares investment ideas?
If United Bankshares has your attention, do not stop here. Use these focused screens to uncover fresh opportunities that match your risk and return preferences.
- Target value potential by scanning companies that combine quality fundamentals with attractive pricing using the 32 high quality undervalued stocks.
- Prioritize staying power and capital protection by reviewing a 11 resilient stocks with low risk scores that highlights businesses with more resilient profiles.
- Hunt for underfollowed opportunities by checking a 15 high quality undiscovered gems that filters for strong fundamentals with less crowd attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com