


As Canada navigates a landscape of rising oil prices and inflationary pressures, the market sentiment remains cautious yet optimistic, particularly with strong corporate earnings providing some buoyancy. Amidst this backdrop, identifying promising small-cap stocks requires a keen focus on companies that demonstrate resilience and adaptability to economic shifts.
Top 5 Undiscovered Gems With Strong Fundamentals In Canada
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| OceanaGold | NA | 23.73% | 62.86% | ★★★★★★ |
| Fortuna Mining | 7.64% | 12.54% | 45.56% | ★★★★★★ |
| Total Energy Services | 3.93% | 18.21% | 37.46% | ★★★★★★ |
| Thor Explorations | NA | 38.45% | 61.95% | ★★★★★★ |
| Alvopetro Energy | 18.59% | 7.72% | 6.43% | ★★★★★☆ |
| Hydreight Technologies | 22.28% | 71.66% | 59.41% | ★★★★☆☆ |
| Kolibri Global Energy | 20.09% | 25.10% | -21.44% | ★★★★☆☆ |
We'll examine a selection from our screener results.
Fortuna Mining (TSX:FVI)
Simply Wall St Value Rating: ★★★★★★
Overview: Fortuna Mining Corp. is involved in the mining of precious and base metals across Argentina, Côte d’Ivoire, Mexico, Peru, and Senegal with a market capitalization of approximately CA$4.91 billion.
Operations: Fortuna Mining generates revenue primarily from its Sango, Bateas, and Mansfield segments, with Sango contributing $680.37 million. The company's cost structure and financial performance details are not provided in the available data.
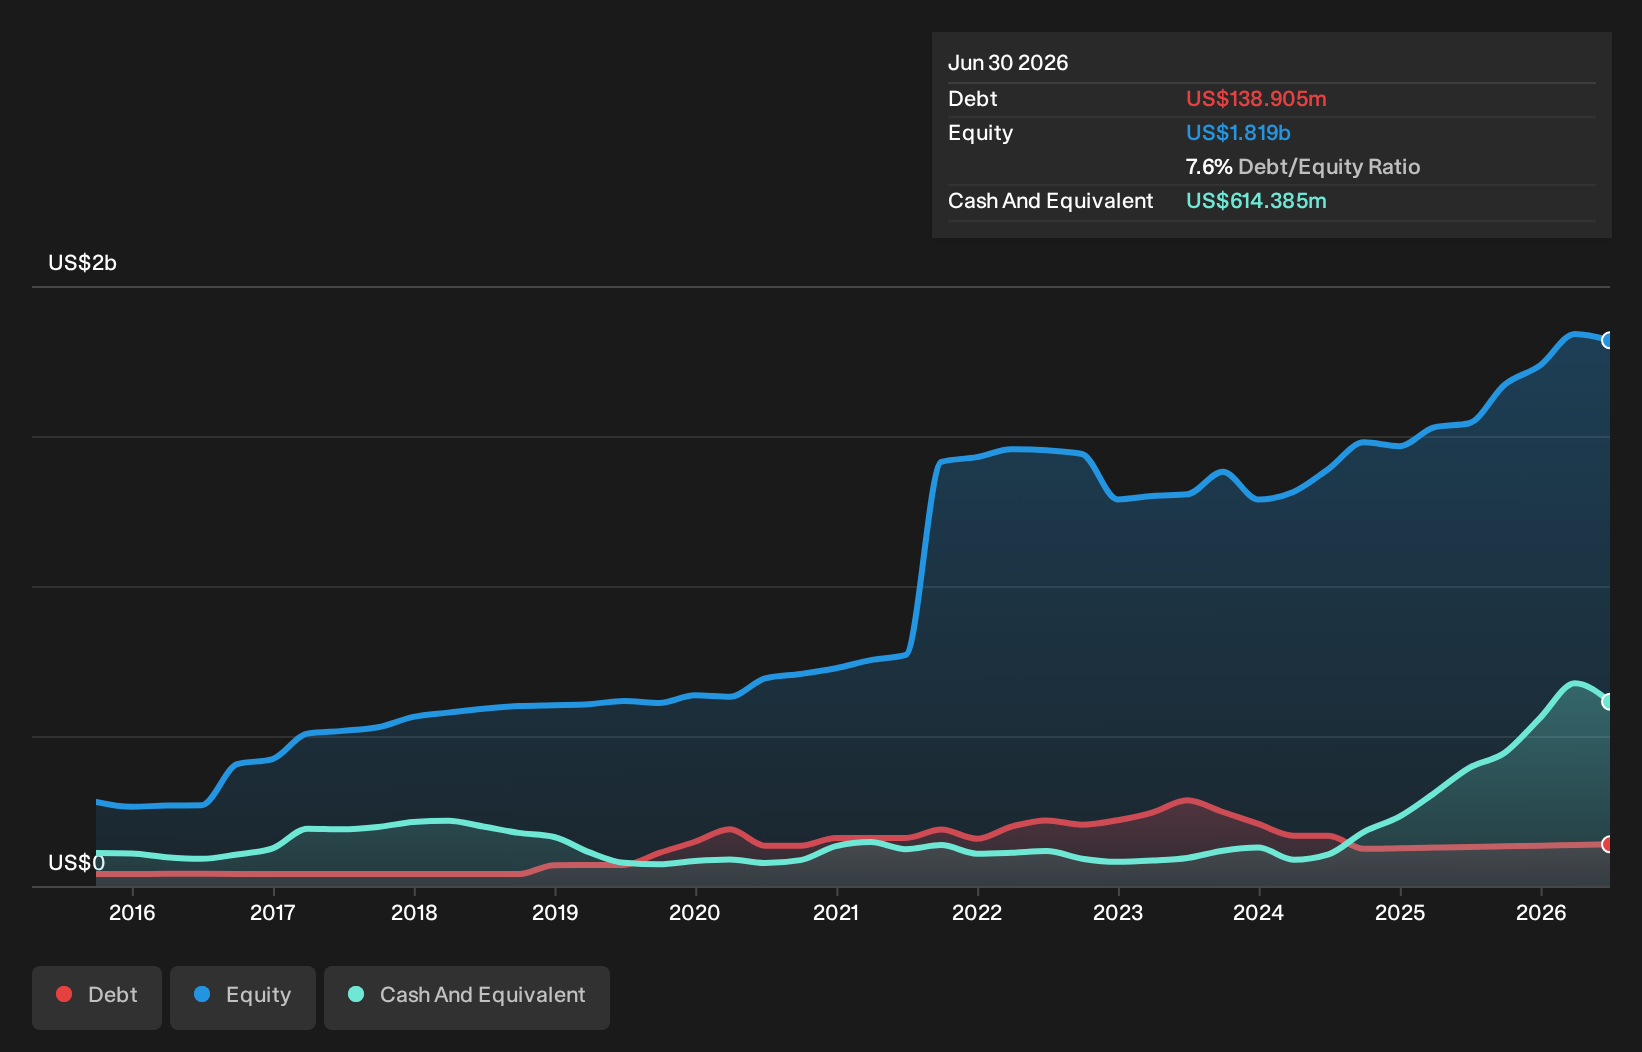
Fortuna Mining seems to be carving a niche in the mining sector with its strategic expansions and acquisitions, such as the recent $200 million purchase of the Bambadji gold project. The company reported impressive earnings growth of 216.2% over the past year, outpacing industry averages significantly. Its debt-to-equity ratio has improved from 20.8% to 7.6% over five years, indicating prudent financial management. However, while trading at a substantial discount to its estimated fair value, operational risks and geopolitical uncertainties could impact future stability despite strong cash flow generation and profitability prospects in an evolving precious metals market.
OceanaGold (TSX:OGC)
Simply Wall St Value Rating: ★★★★★★
Overview: OceanaGold Corporation is involved in the exploration, development, and operation of gold and gold/copper mines located in the United States, the Philippines, and New Zealand with a market cap of CA$9.31 billion.
Operations: The company generates revenue from its gold and gold/copper mining operations across four main segments: Haile ($795.80 million), Waihi ($337.80 million), Didipio ($548.60 million), and Macraes ($780.50 million).
OceanaGold, a notable player in the mining sector, showcases impressive financial health with earnings growth of 130% over the past year and trades at a value 33% below its fair estimate. The company is debt-free, enhancing its appeal by eliminating interest payment concerns. Recent developments include a significant $1.96 billion investment to extend operations at Didipio Mine and an application for extending Macraes' mine life into the late 2030s. Furthermore, OceanaGold repurchased about 3.8% of shares for $253 million recently, underscoring confidence in its future prospects despite fluctuating copper production figures.
- Click here and access our complete health analysis report to understand the dynamics of OceanaGold.
Evaluate OceanaGold's historical performance by accessing our past performance report.

Alvopetro Energy (TSXV:ALV)
Simply Wall St Value Rating: ★★★★★☆
Overview: Alvopetro Energy Ltd. focuses on the acquisition, exploration, development, and production of hydrocarbons in Brazil and Canada, with a market capitalization of CA$415.98 million.
Operations: Alvopetro Energy generates revenue primarily from its oil and gas exploration and production activities, amounting to $62.42 million.
Alvopetro Energy, a nimble player in the Canadian oil and gas scene, has been making strides with its strategic moves. The company reported impressive earnings growth of 25.7% over the past year, outpacing the industry average of 0.2%. Its interest payments are well covered by EBIT at 121 times coverage, pointing to robust financial health. Alvopetro's recent earning agreement in Mannville could unlock significant value with five new wells planned at a cost of CAD 8.5 million. Despite insider selling and increased debt-to-equity ratio from 12.7% to 18.6%, its cash position remains strong relative to debt levels, indicating solid operational footing for future endeavors.

Key Takeaways
- Click here to access our complete index of 7 TSX Undiscovered Gems With Strong Fundamentals.
- Have a stake in these businesses? Integrate your holdings into Simply Wall St's portfolio for notifications and detailed stock reports.
- Take control of your financial future using Simply Wall St, offering free, in-depth knowledge of international markets to every investor.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com