


Frontier AI is suddenly facing a speed limit, with Sam Altman and Dario Amodei publicly calling for a pause on the fastest systems and Washington circling with new safety rules. That kind of scrutiny can shake enthusiasm, but it also quietly shines a spotlight on businesses built around testing, auditing, and red teaming AI. This article unpacks that shift and walks through three stocks exposed to this safety story.
The three stocks below are just a starting sample, and the broader screen surfaced 15 more publicly listed AI risk and model evaluation service providers with equally compelling narratives that are not covered here.
If you want to quickly identify potential leaders in AI red teaming, audit, and assurance, head straight into the AI Risk and Model Evaluation Service Providers screener to filter the list, analyze the data, and focus on your highest conviction ideas.
Innodata (INOD)
Innodata plugs directly into the AI risk and evaluation theme by building the training, labeling, and safety data pipelines that frontier models depend on, which makes its role in how those systems are tested and monitored hard to ignore.
Innodata is a data engineering specialist focused on AI training and post training data, model evaluation, alignment, and safety services, with additional healthcare and PR platforms, and the business carries a market value of about US$1.83b.
"Surging customer demand, especially from large tech and enterprise clients pursuing advanced AI and Agentic AI/robotics, is driving significant expansion in Innodata's high-value data annotation and evaluation services, likely resulting in sustained top-line revenue growth as digital transformation accelerates."
What ultimately matters for investors is how one pressure on Innodata’s business model shapes the balance between that demand story and future margins.
That pressure point is exactly where the full narrative for Innodata traces how Innodata’s demand story, cost base, and AI safety positioning could be quietly decoupling from the headline narrative.
DBAPPSecurity (SHSE:688023)
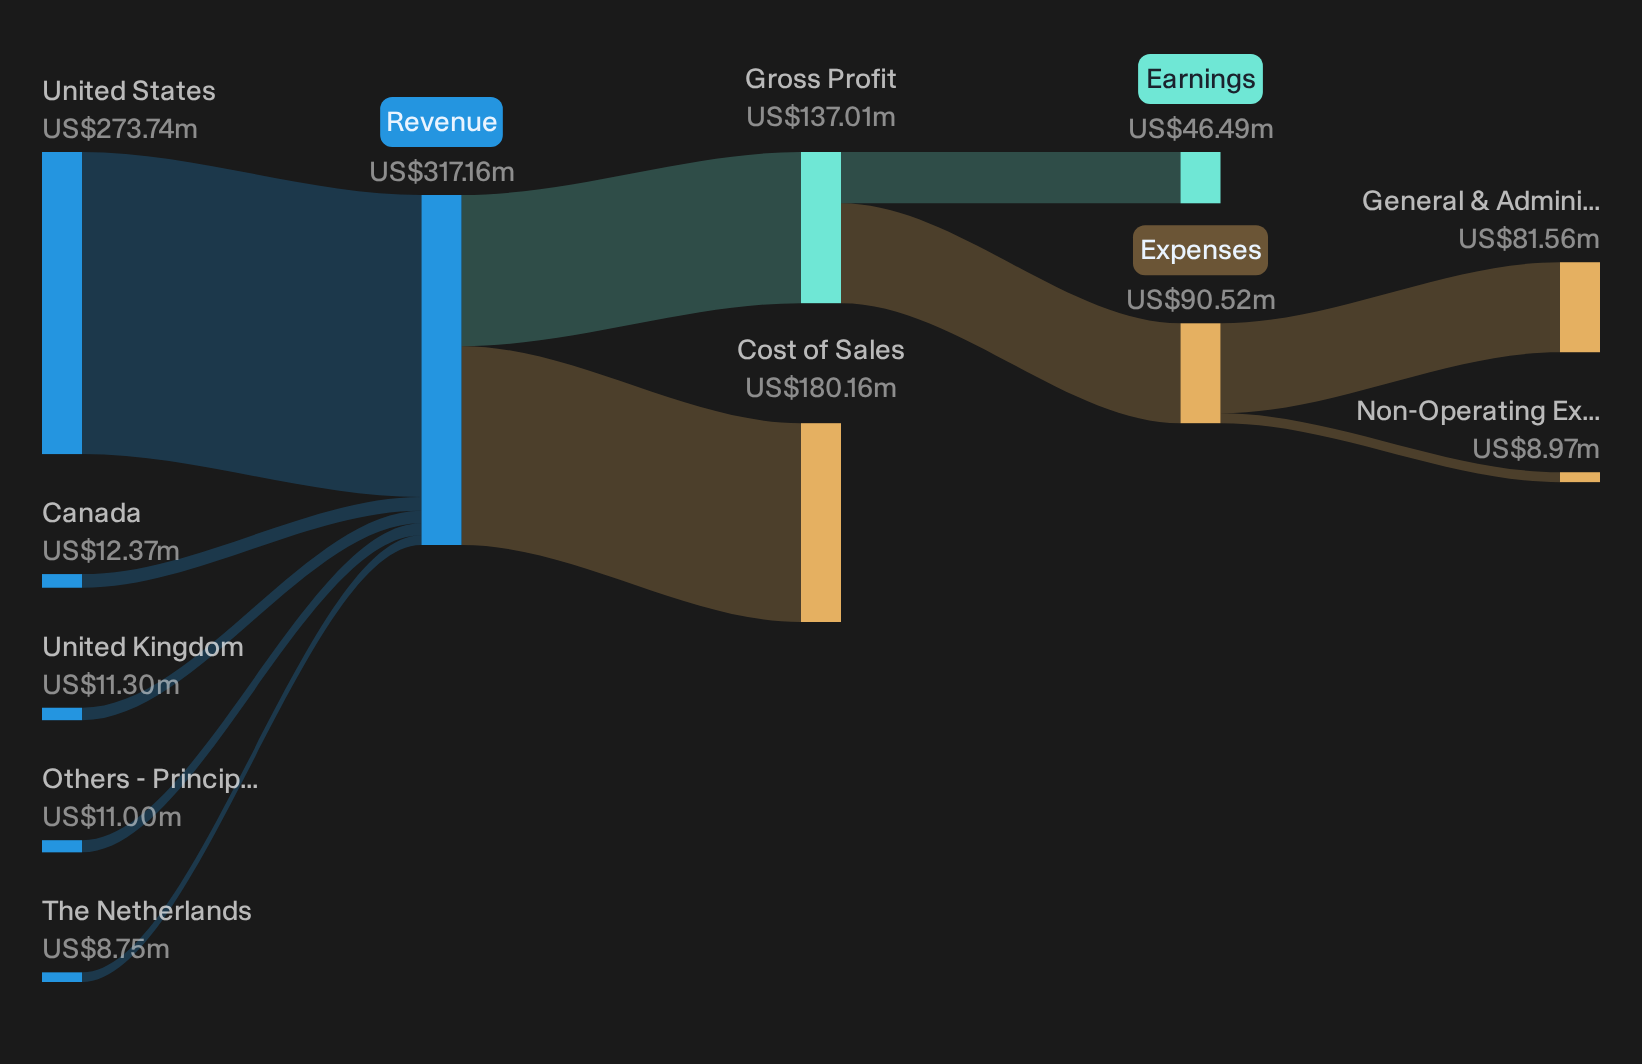
DBAPPSecurity is a Chinese cybersecurity provider whose log analysis, database audit, and red teaming services naturally extend into AI model testing and exposure risk checks, with all recorded revenue of about CN¥2.16b generated in China and a market value near CN¥4.19b.
DBAPPSecurity builds security tools that already handle log analysis, database auditing, and red teaming. Its toolkit fits the AI risk and model evaluation theme as those workflows move into frontier systems. The stock trades on a low P/S against software peers and is forecast for fast earnings growth, which leaves one unresolved funding strain that could matter a lot for how the AI assurance story translates into returns.
That unresolved funding strain is exactly why the DBAPPSecurity financial health report could be worth a look for understanding how DBAPPSecurity's balance sheet might shape the AI opportunity.
DBAPPSecurity financial health reportCEVA (CEVA)
CEVA plugs into the AI risk and model evaluation theme by providing silicon and software IP for edge chips where AI workloads need to be efficient, predictable, and testable under tight power, latency, and reliability constraints.
CEVA licenses IP that underpins wireless connectivity, signal processing, and on device AI, generating about $116 million from IP licensing and carrying a market value near $817 million.
For investors watching how AI risk concerns push more intelligence onto devices instead of giant data centers, CEVA offers a different angle on the story, with its IP quietly embedded in the chips that will need to prove reliable under closer scrutiny.
"Accelerating customer adoption of CEVA's Edge AI NPUs (as evidenced by multiple new, high-impact licensing deals and the integration of NeuPro architectures across diverse markets like audio, video, and infrastructure) lays the foundation for materially higher royalty revenue per device as these AI-enabled products ramp into mass production over the next 18 to 24 months."
What really moves the needle for CEVA is how one shift in where AI workloads run changes pricing power, royalty depth, and the value of its edge AI toolkit.
That shift is exactly what the full narrative for CEVA unpacks, connecting CEVA's edge AI royalties, competitive risks, and the areas where accelerating workloads could still reshape the payoff curve.

Seeking Alternatives Before They Fly Past
Fresh ideas move first. By the time every feed is talking about them, the easy part of the breakout can be gone. Scan these curated shortlists while it matters and look for opportunities early.
- Spot sturdier balance sheets before the crowd and sift for resilient operators using the list of solid balance sheet and fundamentals (23 results).
- Look for early momentum in smaller AI players by scanning the 32 AI small caps while many are still under the radar for now.
- Gain exposure to structural demand for essential metals by tracking producers in the 29 top copper producer stocks before capital increases.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com