


Scottsdale, Arizona-based ON Semiconductor Corporation (ON) provides intelligent sensing and power solutions supplying analog, standard logic, and discrete semiconductors. Valued at $29.6 billion by market cap, the company offers products including integrated circuits and analog ICs, as well as a variety of surface mount and standard packages.
Companies worth $10 billion or more are generally described as “large-cap stocks,” and ON fits right into that category with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the semiconductors industry. ON derives its competitive edge from its vertically integrated Silicon Carbide (SiC) supply chain, market leadership in automotive image sensors for ADAS, and sticky, long-lifecycle design wins in high-growth automotive and industrial sectors. By avoiding low-margin consumer chips and optimizing capital with a "fab-right" manufacturing strategy, it secures high customer switching costs, predictable long-term revenue, and resilient operating margins.
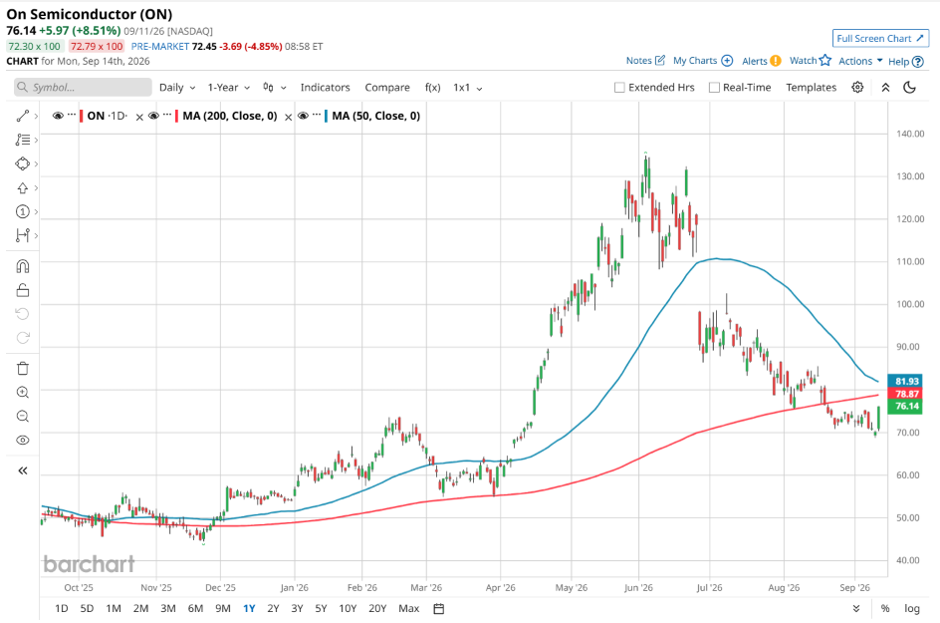
Despite its notable strength, ON slipped 43.6% from its 52-week high of $134.92, achieved on Jun. 3. Over the past three months, ON stock declined 37.9%, underperforming the iShares Semiconductor ETF’s (SOXX) 16.3% losses during the same time frame.
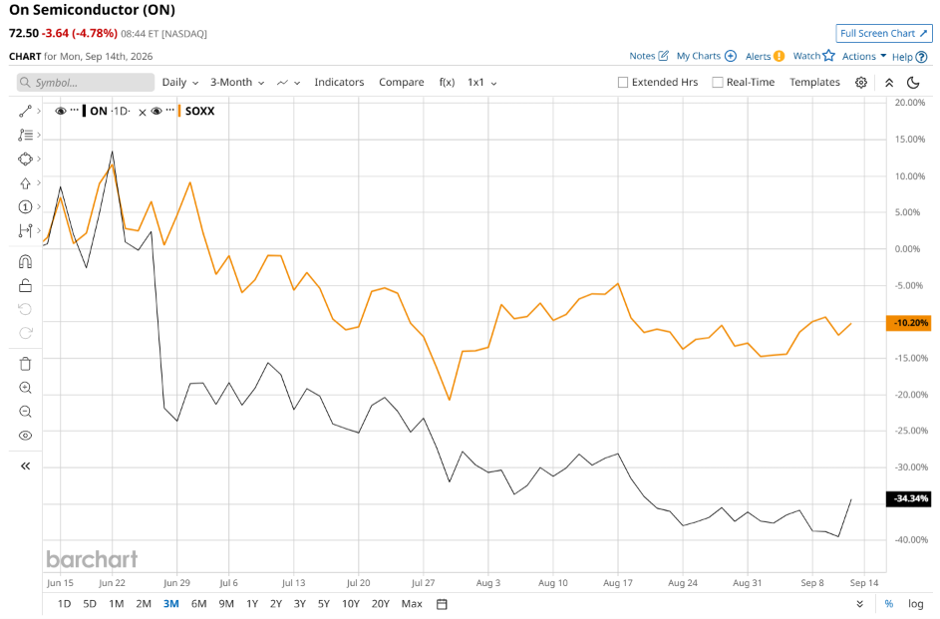
Shares of ON rose 33.9% on a YTD basis and climbed 50.2% over the past 52 weeks, underperforming SOXX’s YTD gains of 65.6% and 95.1% returns over the last year.
To confirm the bearish trend, ON has been trading below its 200-day moving average since late August. The stock has been trading below its 50-day moving average since late June.
ON has underperformed relative to broader semiconductor benchmarks due to prolonged cyclical softness across its key automotive and industrial end markets. Weakness in global EV sales growth and industrial automation led to customer inventory destocking, which depressed factory utilization rates and squeezed operating margins. Additionally, while AI data center spending accelerated rapidly across the tech sector, ON's heavy exposure to traditional analog power components left it lagging high-growth digital chipmakers, resulting in double-digit revenue declines and lower earnings before recent signs of utilization recovery began to surface.
On Aug. 3, ON shares closed down by 1.5% after reporting its Q2 results. Its adjusted EPS of $0.74 surpassed Wall Street expectations of $0.72. The company’s revenue was $1.60 billion, topping Wall Street forecasts of $1.59 billion. For Q3, ON expects its adjusted EPS to range from $0.81 to $0.93, and revenue in the range of $1.7 billion to $1.8 billion.
In the competitive arena of semiconductors, Infineon Technologies AG (IFNNY) has taken the lead over ON, with an 80.1% uptick over the past 52 weeks and 53.6% gains on a YTD basis.
Wall Street analysts are reasonably bullish on ON’s prospects. The stock has a consensus “Moderate Buy” rating from the 28 analysts covering it, and the mean price target of $104.50 suggests a potential upside of 37.2% from current price levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.